
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Elbit Systems (TASE:ESLT) Just Gave Investors Something To Think About
Elbit Systems (TASE:ESLT) just reshaped its U.S. presence by rebranding its American operating segment as Twenty-Six Defense. This move puts domestic design, engineering and manufacturing capacity in clear focus for investors.
Recent trading suggests interest in Elbit Systems is still firm, with a 7-day share price return of 3.54% and the stock now at ₪2,270.6. The 1-year total shareholder return of 40.05% and very large 5-year total shareholder return near 4x point to strong momentum built over several years rather than a short-term spike.
Scan for other defense contractors with strong manufacturing footprints and policy tailwinds by reviewing the hand-picked 39 power grid technology and infrastructure stocks alongside Elbit Systems after the Twenty-Six Defense rebrand.
Bulls see the Twenty-Six Defense rebrand as proof Elbit Systems is tightly aligned with U.S. defense priorities. Bears worry that optimism and a strong multi year return already reflect that. Which side does the current valuation support?
Most Popular Narrative: 23% Undervalued
Elbit Systems last closed at ₪2,270.6, while the most followed narrative pegs fair value closer to ₪2,965. This frames the current debate around the rebrand and recent share gains.
Record $25.2 billion backlog, with close to 70% from customers outside Israel and multi year contracts such as the 8 year, 2.3 billion dollar strategic program, provides high visibility on sustained top line growth and supports operating leverage and earnings compounding.
See why 4 investors see Elbit Systems as 23% undervalued.
Result: Fair Value of ₪2,965 (UNDERVALUED)
Still, this upside story can break if defense budgets cool or if Elbit Systems stumbles on large programs where execution and profitability assumptions are tight.
Find out about the key risks to this Elbit Systems narrative.
Another View on Elbit Systems: Cash Flows Paint a Tougher Picture
The first narrative around Elbit Systems leans on analyst targets and earnings power to argue the stock looks 23% undervalued. A different lens, our DCF model based on projected cash flows, points the other way and suggests the shares trade above an estimate of future cash flow value of ₪998.08.
That gap leaves you with a simple question. Is the market correctly paying up for earnings quality and growth expectations, or are investors stretching too far beyond what cash generation alone might justify over time?
Look into how the SWS DCF model arrives at its fair value.
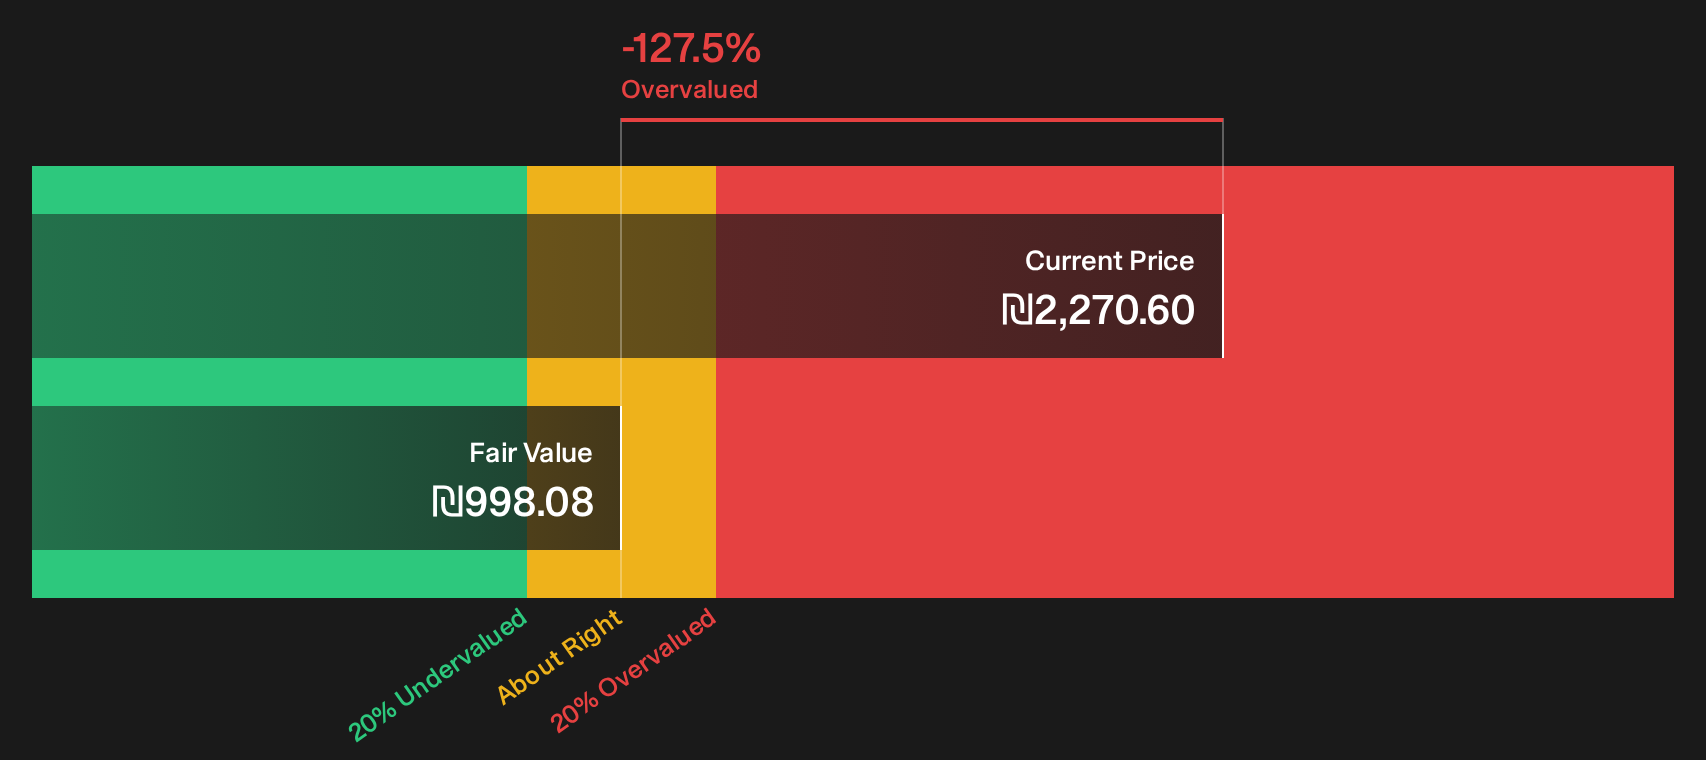
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Elbit Systems for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed messages around Elbit Systems leave you torn, check the data for yourself and decide how urgent the opportunity feels. Next, weigh those potential upsides against the detailed breakdown in 2 key rewards.
Looking for more Elbit Systems sized opportunities?
If Elbit Systems has your attention, do not stop here. Fresh ideas often come from looking just outside your current watchlist.
- Target higher income potential by scanning companies with resilient payouts through the 159 dividend fortresses.
- Hunt for quality at a discount by reviewing the 179 high quality undervalued stocks that combine robust fundamentals with attractive pricing.
- Prioritize capital protection by focusing on the 227 resilient stocks with low risk scores that score well on balance sheet strength and risk checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com