
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Kyndryl Holdings (KD) Undervalued After Its 10 Year NASPO Contract Win?
Kyndryl Holdings (KD) has just landed a 10 year NASPO ValuePoint Cloud and Software Solutions contract, giving it structured access to US public sector clients for a wide range of IT services.
For context, Kyndryl Holdings shares trade at US$12.07 after a one day share price decline of 6.8% and a seven day slide of 11.05%. The 90 day share price return is up 8.45%, but the year to date share price return is down 52.65% and the one year total shareholder return has fallen 61.71%. This suggests that, despite recent contract wins such as NASPO ValuePoint and the MAX Power Mining consulting engagement, sentiment is still recovering and investors are reassessing both execution risk and the longer term potential of the turnaround story.
Scan how Kyndryl Holdings compares with other IT and AI focused service providers that have been hand picked in our 88 AI infrastructure stocks for potential contract driven momentum.
Bulls see Kyndryl Holdings as a mispriced turnaround with fresh public sector traction, while bears focus on the steep drawdown and execution risk. Which side do the current valuation markers lean toward next?
Most Popular Narrative: 14% Undervalued
Kyndryl Holdings last closed at $12.07, while the most followed narrative anchors on a fair value of $14.10, which frames the current slide as a discount rather than a verdict on the business.
The company's focus on expanding AI, data, and cybersecurity services, supported by investments in proprietary initiatives like Kyndryl Bridge and new alliances such as Databricks, is allowing Kyndryl to address rising complexity and security requirements, supporting both higher margins and new revenue streams.
See why 50 investors see Kyndryl Holdings as 14% undervalued.
Result: Fair Value of $14.10 (UNDERVALUED)
Still, the Kyndryl Holdings story can crack if legacy, lower margin contracts take longer to roll off, or if complex deal transitions keep delaying new signings.
Find out about the key risks to this Kyndryl Holdings narrative.
Another View: Kyndryl Holdings Through Earnings Multiples
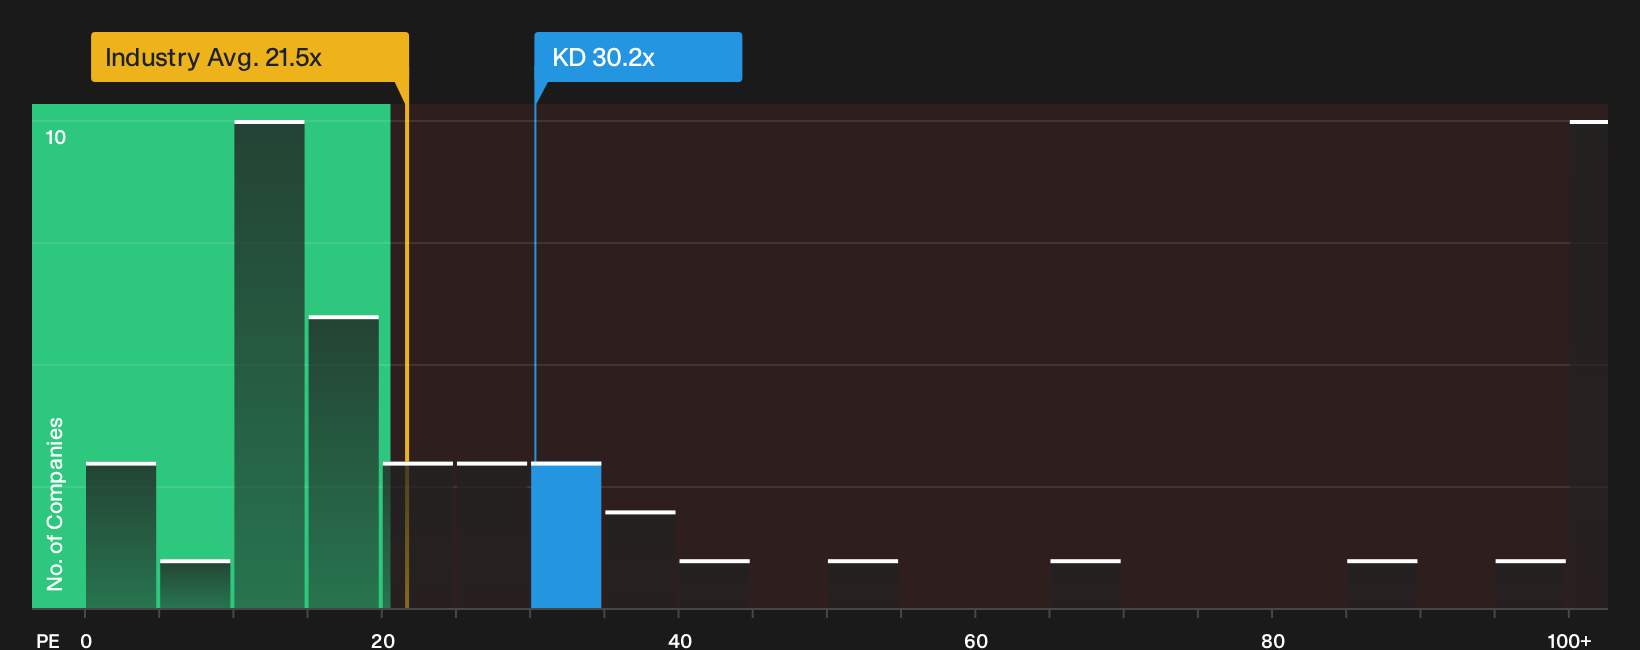
Kyndryl Holdings may look inexpensive relative to a $14.10 fair value narrative, yet its current P/E of 30.2x is more than double the 14.3x peer average and significantly higher than the 21.5x US IT industry level. The fair ratio of 53.5x highlights a wide range of possible outcomes. Which reference point do you consider most relevant?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the numbers and narratives only matter if you use them. Act while sentiment is uncertain and build your own view using 2 key rewards and 3 important warning signs.
Looking for more Kyndryl Holdings sized ideas?
Do not stop your research with Kyndryl Holdings when a wider opportunity set is just a few clicks away on the Simply Wall Street Screener.
- Target potential mispricings across the market by scanning our 35 high quality undervalued stocks for candidates with fundamentals that may not match their current share prices.
- Prioritise resilience and sleep better at night by focusing on companies in the 30 resilient stocks with low risk scores that score well on balance sheet strength and risk checks.
- Hunt for future leaders before they hit the headlines by filtering for financially strong outliers using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com