
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
European Growth Companies With Insider Ownership Up To 34%
As European markets navigate the volatility driven by escalating Middle East tensions and fluctuating energy prices, investors are keenly observing how these factors influence inflation and bond yields. Amid this backdrop, identifying growth companies with substantial insider ownership can be particularly appealing, as such ownership often signals confidence in the company's potential and alignment with shareholder interests.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.8% |
| Kuros Biosciences (SWX:KURN) | 25.9% | 58.6% |
| KebNi (OM:KEBNI B) | 16.3% | 103.8% |
| Gold Road International (OB:GOLDR) | 35.9% | 89.8% |
| CTT Systems (OM:CTT) | 17.4% | 55.3% |
| Clavister Holding AB (publ.) (OM:CLAV) | 20.5% | 41.1% |
| CD Projekt Red (WSE:CDR) | 35.2% | 47.9% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.2% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 29.8% |
Let's dive into some prime choices out of the screener.
NTG Nordic Transport Group (CPSE:NTG)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: NTG Nordic Transport Group A/S, with a market cap of DKK6.06 billion, offers asset-light freight forwarding services across road, rail, air, and ocean in Denmark, Germany, the United States, Sweden, Finland, and internationally.
Operations: The company's revenue is primarily derived from two segments: Road & Logistics, which contributes DKK9.70 billion, and Air & Ocean, accounting for DKK2.49 billion.
Insider Ownership: 14.8%
NTG Nordic Transport Group has demonstrated solid earnings growth, with net income rising to DKK 81 million from DKK 32 million year-over-year for Q2 2026. Although revenue growth is forecasted at a slower pace than the Danish market, earnings are expected to grow significantly at over 20% annually. Despite high debt levels and recent share price volatility, NTG trades well below its estimated fair value and boasts high insider ownership, indicating potential alignment with shareholder interests.
- Click to explore a detailed breakdown of our findings in NTG Nordic Transport Group's earnings growth report.
- Our comprehensive valuation report raises the possibility that NTG Nordic Transport Group is priced lower than what may be justified by its financials.
Morrow Bank (OM:MORROW)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Morrow Bank AB offers unsecured financing to consumers in Norway, Sweden, and Finland and has a market cap of SEK5.03 billion.
Operations: The company generates revenue of SEK788.91 million from its banking segment, providing unsecured financing to consumers in Norway, Sweden, and Finland.
Insider Ownership: 21.1%
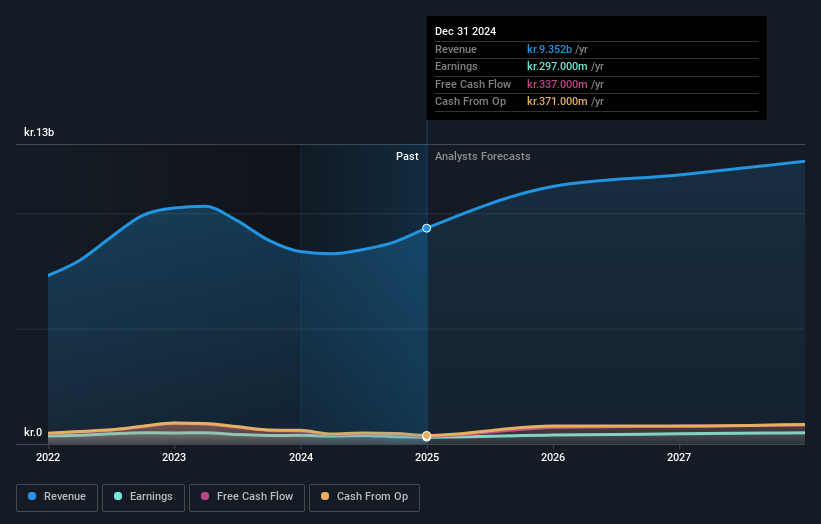
Morrow Bank is experiencing robust growth, with earnings projected to increase significantly at 39.4% annually over the next three years, outpacing the Swedish market. Despite a high level of bad loans (15.3%) and low allowance for them (59%), its revenue is forecasted to grow 34.9% per year, surpassing market expectations. Recent financial results show net interest income of SEK 683.8 million for six months ending June 2026, reinforcing its growth trajectory amid trading below fair value estimates by 15.2%.
- Dive into the specifics of Morrow Bank here with our thorough growth forecast report.
- Upon reviewing our latest valuation report, Morrow Bank's share price might be too optimistic.

New Wave Group (OM:NEWA B)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: New Wave Group AB (publ) is involved in designing, acquiring, and developing brands and products across the corporate, sports, gifts, and home furnishings sectors with operations in Sweden, the United States, Benelux, other Nordic countries, Europe, and internationally; it has a market cap of approximately SEK11.78 billion.
Operations: The company's revenue is divided into three main segments: Corporate (SEK5.44 billion), Sports & Leisure (SEK4.18 billion), and Gifts & Home Furnishings (SEK862 million).
Insider Ownership: 35%
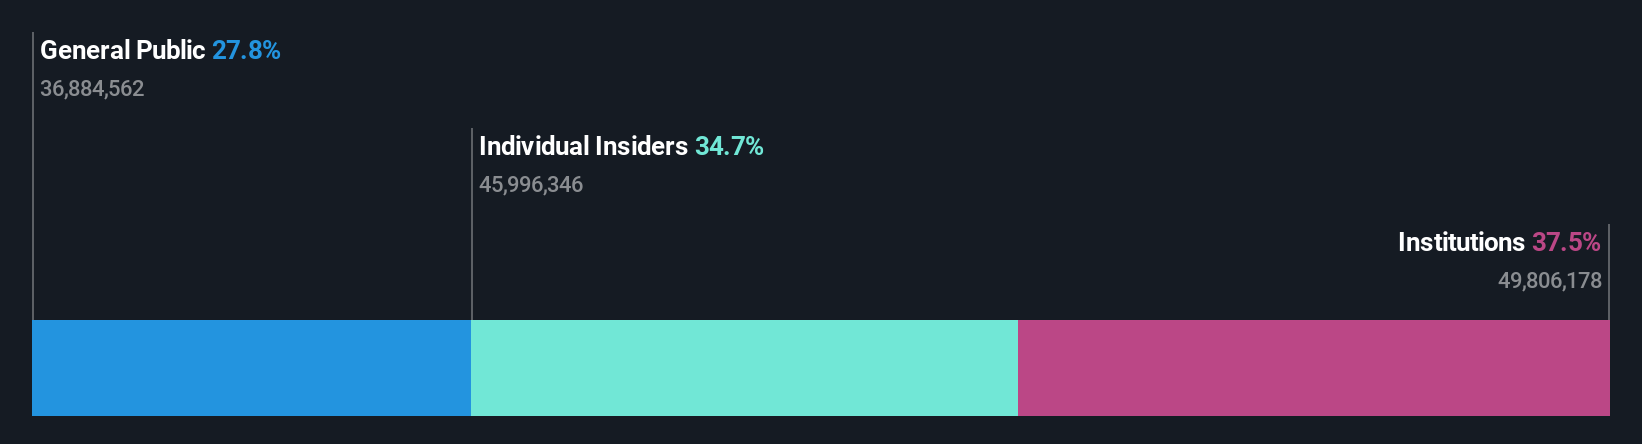
New Wave Group exhibits strong growth potential, with earnings expected to rise significantly by 20.4% annually, outpacing the Swedish market. Insider ownership is reinforced by substantial insider buying over recent months. The company trades at a good value relative to peers and below its estimated fair value by 55.2%. Recent financial results show an increase in sales and net income for the second quarter of 2026, indicating positive operational momentum despite modest revenue growth forecasts of 7.4% per year.
- Delve into the full analysis future growth report here for a deeper understanding of New Wave Group.
- Our valuation report unveils the possibility New Wave Group's shares may be trading at a discount.
Next Steps
- Embark on your investment journey to our 214 Fast Growing European Companies With High Insider Ownership selection here.
- Want To Explore Some Alternatives? The best AI stocks today may lie beyond giants like Nvidia and Microsoft. Find the next big opportunity with these 19 smaller AI-focused companies with strong growth potential through early-stage innovation in machine learning, automation, and data intelligence that could fund your retirement.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com