
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will FTSE All World Inclusion Change MasTec Stock Narrative
- MasTec was recently added to the FTSE All-World Index in US dollars, following a period of strong demand across power delivery, data centers, and renewable energy infrastructure that has supported double-digit revenue growth and a record backlog in key divisions.
- The index inclusion increases MasTec's visibility with global investors at the same time its grid modernization and clean energy work is shaping longer-term project pipelines and revenue visibility.
- We will explore how MasTec's investment narrative is influenced by FTSE All-World inclusion and its growing role in grid modernization.
Scan beyond MasTec and this FTSE All-World inclusion by reviewing peers exposed to the same grid, data center, and energy build-out using the curated 39 power grid technology and infrastructure stocks
MasTec Investment Narrative Recap
To own MasTec, you need to believe the multiyear build out of power delivery, clean energy projects, communications networks, and data centers keeps translating into a solid backlog and healthy margins. The key short term catalyst is how efficiently that backlog in Power Delivery and Clean Energy & Infrastructure converts into cash flow while heavy hiring and equipment spend are still working through the system.
The biggest near term risk is that large customers delay or resize projects after MasTec has already locked in labor and equipment, which could squeeze profitability. Inclusion in the FTSE All World Index may support liquidity and awareness, but it does not materially change those execution and concentration risks.
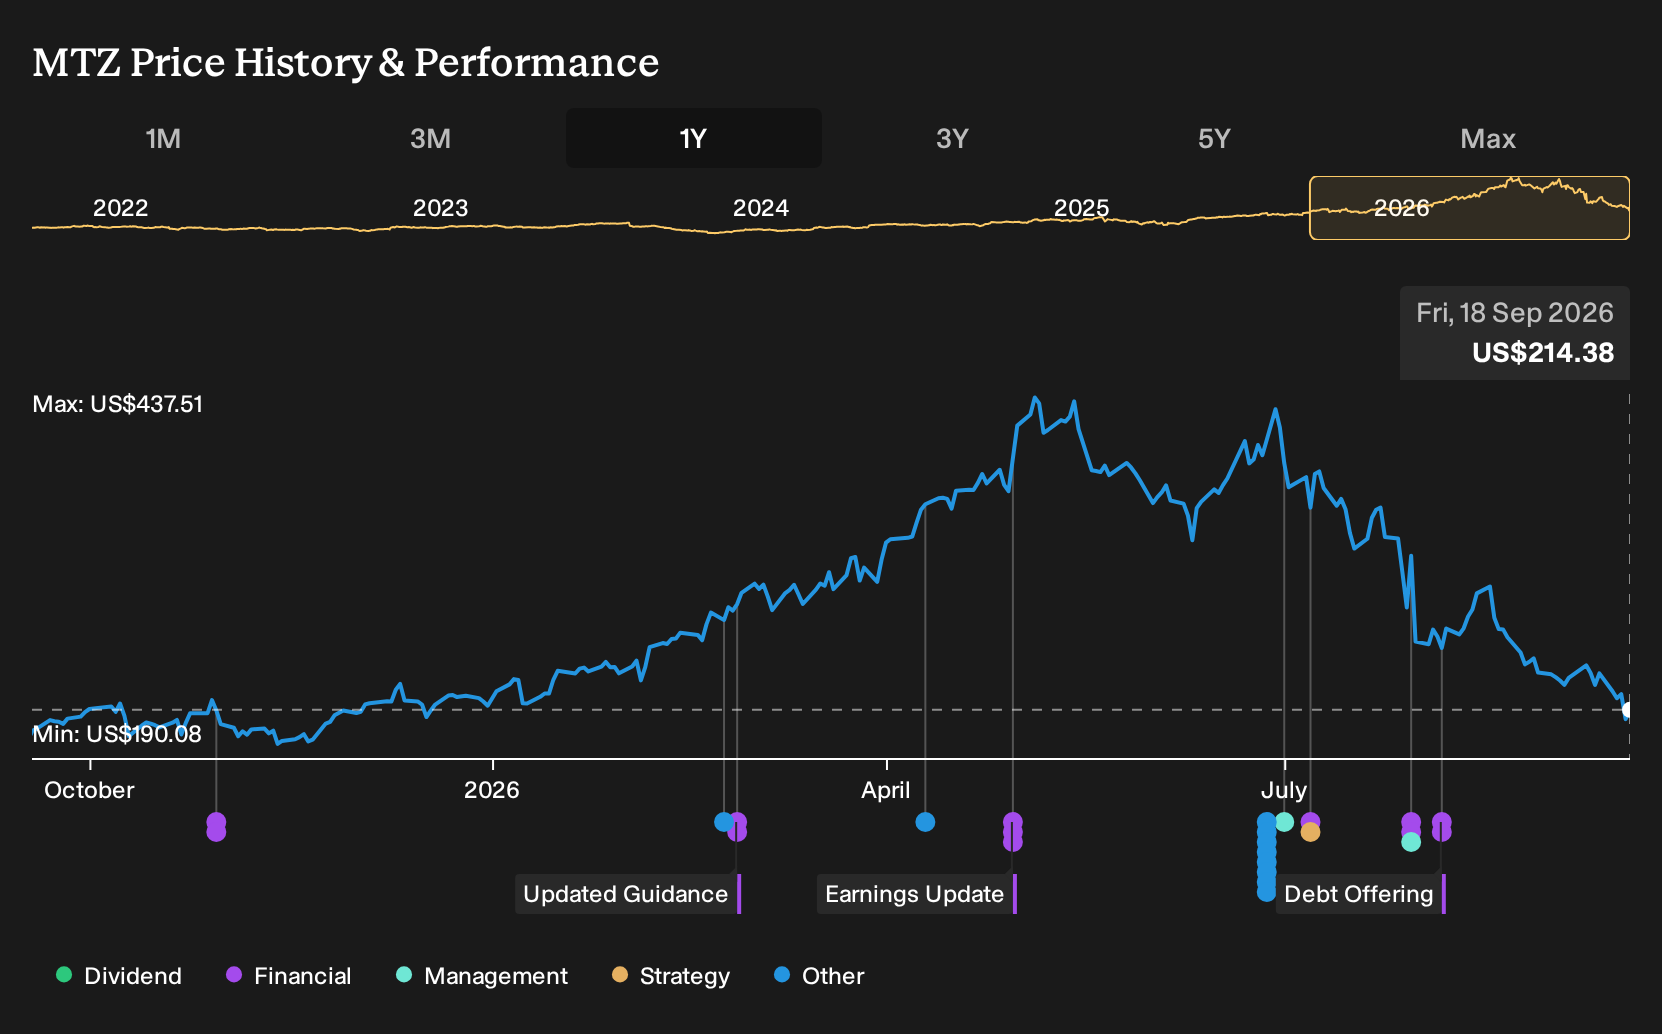
The Morgan Stanley Laguna Conference appearance on September 15, 2026 is the most relevant recent milestone for MasTec around this index news. Management now has a larger global audience just as institutional investors are focused on grid modernization, data center demand, and renewable build outs tied to MasTec’s record backlog and recent revenue trends.
For you, that conference matters as an information event rather than a headline catalyst. It gives management a forum to address concerns around high debt levels, margin variability from rapid scaling, and project execution risk. It also lets investors test whether the operational story behind MasTec still lines up with backlog quality and expected earnings growth.
MasTec's current earnings of $494.3 million are set against analyst expectations of $1.2b in earnings on $26.7b of revenue by 2029. This implies forecast annual revenue growth of 18.3% and roughly a 2.4x increase in earnings from today.
Uncover why MasTec's fair value indicates a 94% potential upside to its current price before that discount closes.
Exploring Other Perspectives
Some of the most optimistic analysts focus on MasTec’s potential earnings power if energy transition and data projects stay on track. Before this index news, the bullish camp was modeling about $29.5b in revenue and $1.6b in earnings by 2029, far above consensus. Those targets may shift, so treat them as one of several viewpoints to consider and evaluate.
Explore 6 other MasTec fair value estimates, including one that suggests as much as 142% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your MasTec research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for MasTec. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MasTec's overall financial health at a glance.
Looking for more MasTec-sized investment ideas?
Once you have a view on MasTec, it often helps to line it up against other opportunities that fit different risk and income profiles. The Simply Wall St Screener is a quick way to surface stocks that match the type of portfolio you want to build, not just the latest headline story.
- If you care most about quality at a reasonable entry point, start with a curated set of 35 high quality undervalued stocks that combine strong fundamentals with pricing that may appeal to value focused investors.
- If sleep-at-night resilience matters more than rapid upside, filter for 30 resilient stocks with low risk scores that score well on stability and balance sheet strength.
- If you are hunting for under-the-radar ideas, broaden your watchlist with a 16 high quality undiscovered gems that still show solid financial underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com