
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Top 3 Insider Growth Stocks To Watch In September 2026
The Federal Reserve just lifted interest rates again to tackle inflation that sits at 3.4%, and money is no longer cheap. Growth stories now face a simple test: Can the business justify its price when borrowing costs bite? That is exactly where fast expanding companies with leaders who own a lot of their own stock can shine. This article breaks down three such high conviction ideas from our screener.
The three stocks covered below are just a sample of this theme, with the full screen surfacing 1,299 more companies where fast growth potential lines up with high insider ownership and a similar alignment between management and shareholders. To identify and analyze your own high conviction ideas straight from this universe, head to the Fast Growing Stocks With High Insider Ownership screener.
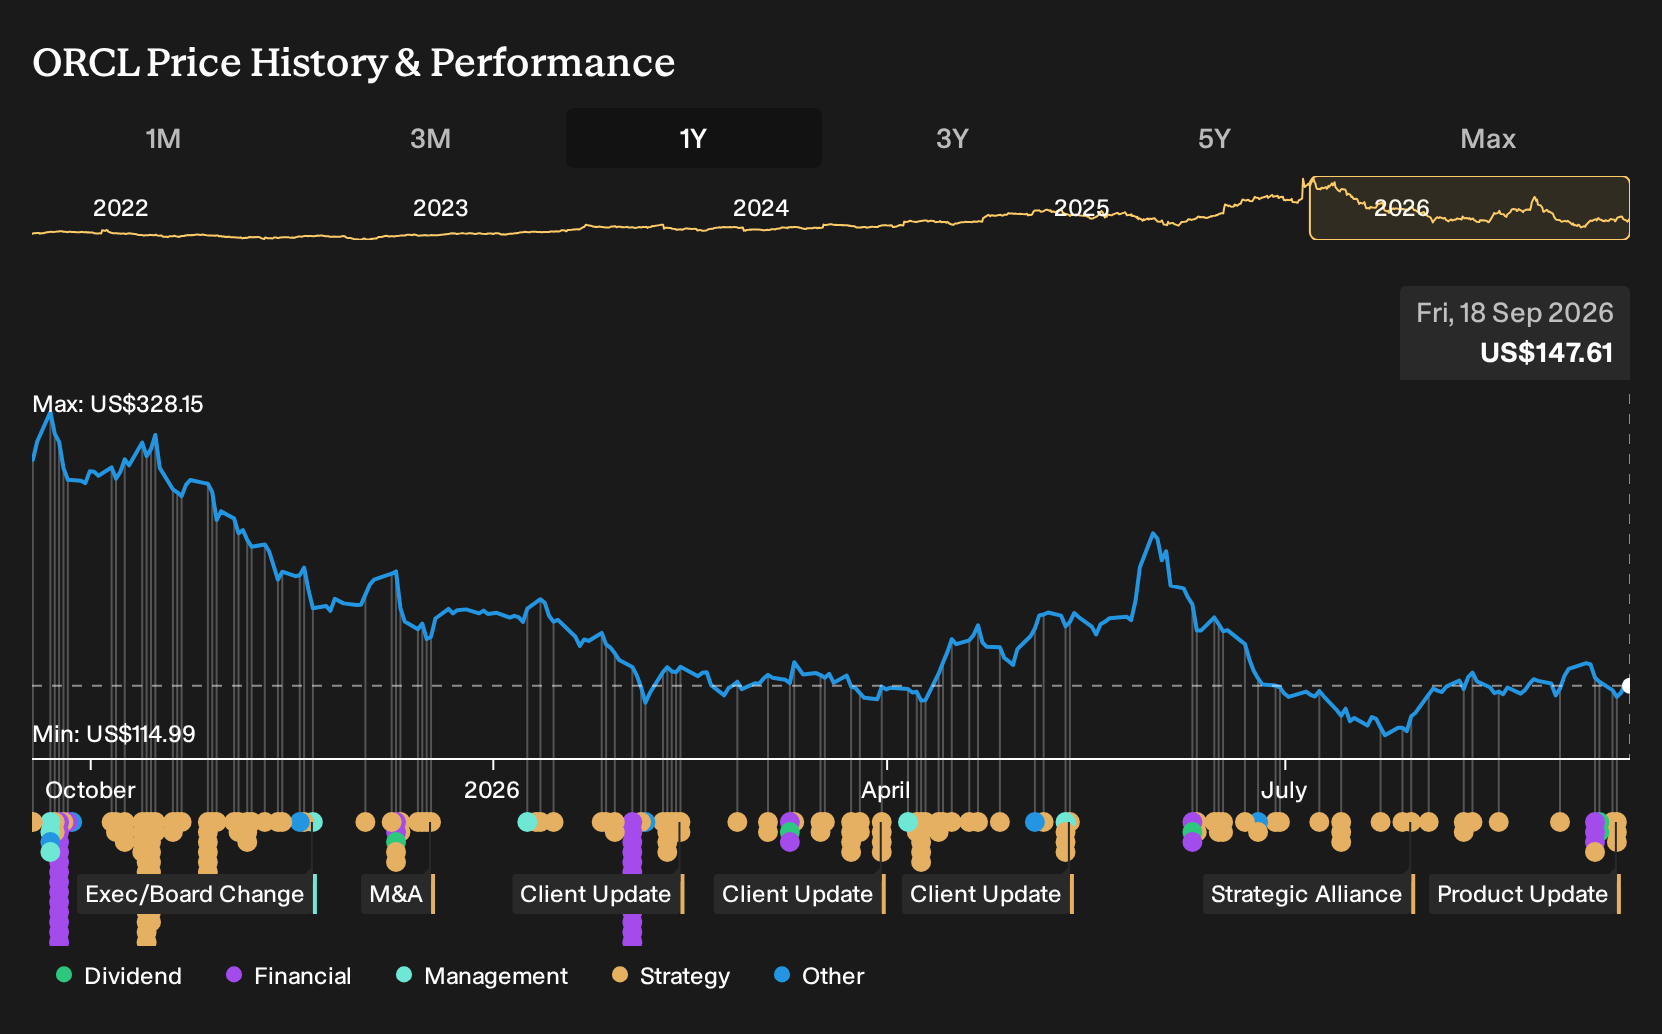
Oracle (ORCL)
Overview: Oracle is a global enterprise software and cloud provider, with Oracle Cloud and Fusion applications anchoring its fast-growing subscription business.
Operations: Oracle generates most of its revenue from Cloud and software at about US$62.8b, with smaller contributions from Services and Hardware.
Market Cap: US$446.3b
Oracle matters for this fast growing with high insider ownership theme because its cloud and AI infrastructure push is reshaping how large enterprises run critical workloads, and the scale of that shift comes through clearly in the buildout described below.
"Oracle is building gigawatt-scale data centers. One massive 1,100-acre campus in Abilene, Texas, featuring eight buildings, is dedicated initially to OpenAI workloads."
What happens to Oracle’s growth story if one unseen pressure on the economics of that buildout tightens more than markets currently expect?
If that pressure is building in the background, it makes the full narrative for Oracle essential reading for understanding how Oracle’s expansion story and risk profile could be decoupling from expectations.
AppLovin (APP)
Overview: AppLovin provides AI powered advertising tools and in app monetization platforms that help mobile and connected TV publishers grow revenue efficiently.
Operations: The business currently generates about US$6.8b from its Advertising segment, split roughly evenly between the United States and the rest of the world.
Market Cap: US$103.1b
AppLovin matters for a fast growing, high insider ownership screen because its AI driven ad stack turns user attention into measurable marketing spending at scale, putting management’s optimistic outlook to the test in real time.
"Expanded rollout of the self-service AXON ads manager and Shopify integration is expected to open AppLovin's platform to a massive new base of small and mid-sized advertisers globally, dramatically increasing advertiser count and driving sustained uplift in topline revenue."
What AppLovin’s growth profile looks like a few years from now may hinge on how that expansion filters through to profitability and cash generation.
That inflection point is exactly what the full narrative for AppLovin unpacks, revealing how AppLovin’s AXON rollout could accelerate, stall, or mask the true earnings power beneath the surface.

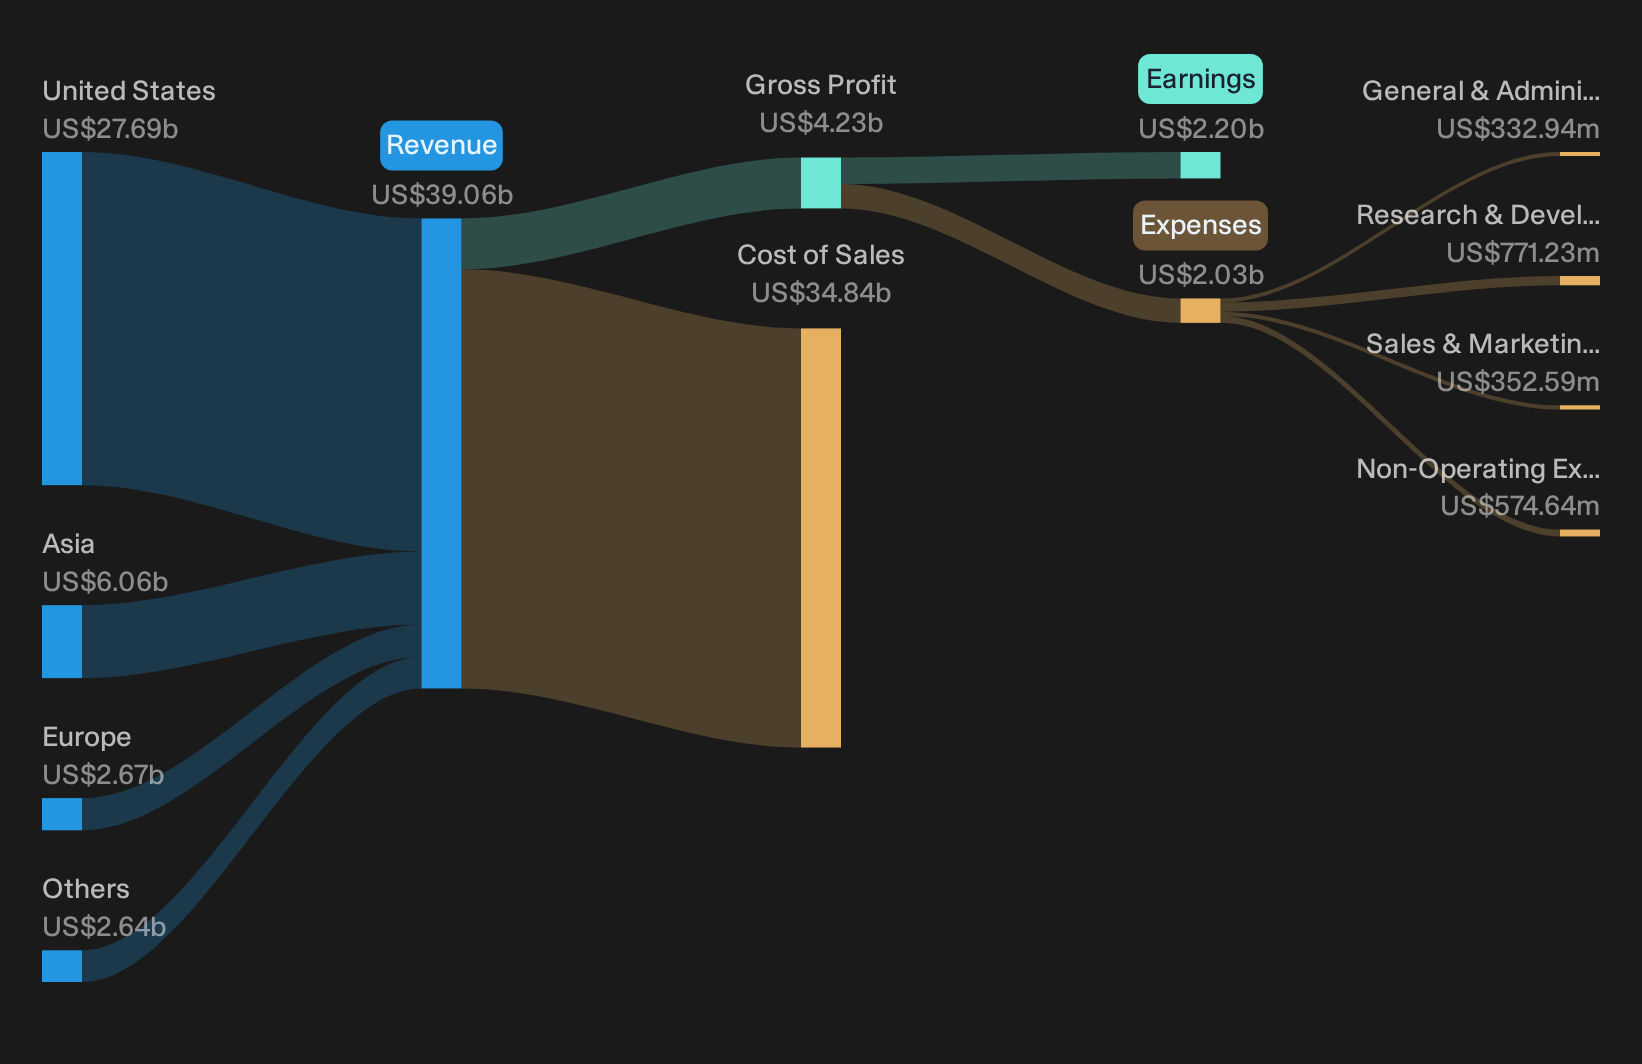
Super Micro Computer (SMCI)
Overview: Super Micro Computer builds high performance, modular servers and storage systems that power AI training, inference, cloud, and data center workloads worldwide.
Operations: Super Micro Computer generates about US$39.1b by developing and providing high performance server solutions, with most revenue reported in the United States.
Market Cap: US$25.7b
Super Micro Computer matters for this fast growing, high insider ownership screen because its AI focused server platforms sit directly in the buildout of the hardware that trains and runs modern AI models, which is a key area of focus for analysts and management.
"The accelerating global adoption of AI and analytics continues to drive demand for high-performance, scalable server and data center solutions, positioning Super Micro within the expanding buildout of AI infrastructure, which directly supports expectations for revenue outperformance."
What happens to Super Micro Computer’s growth story if one unresolved pressure on AI server margins tightens just as that demand wave reaches full speed?
That margin squeeze risk is exactly where the full narrative for Super Micro Computer steps in. It maps how Super Micro Computer could translate today’s AI surge into durable, cash backed earnings power.
Seeking Alternatives Before The Crowd?
Fresh ideas tend to move first. Breakout stories can gain momentum while they are still under the radar, and the most attractive entry windows may close quickly, so consider moving early.
- Target resilient cash generators by scanning the list of solid balance sheet and fundamentals (23 results) that filters for sturdier fundamentals before they are fully reflected by the broader market.
- Explore the AI infrastructure theme by reviewing the 88 AI infrastructure stocks packed with companies involved in data centers, chips, and tooling while attention is still catching up.
- Position around the energy transition using the 19 nuclear energy infrastructure stocks featuring nuclear infrastructure players that may experience changing momentum as interest develops.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com