
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 US Grid Stocks Riding The Data Center Power Buildout
AI data centers now absorb more real money than new homes in the U.S., and hyperscalers are planning around US$1.3b in annual capex by 2027 to feed that buildout. Power, grid gear, and electrification sit right on that fault line between opportunity and potential overbuild. This article breaks down how that backdrop touches three U.S. Power Grid and Electrification Providers to Data Centers stocks that are exposed to the same news shock.
The three stocks in focus below are only a small sampling, and the full screen surfaced 42 more companies with equally compelling infrastructure stories that are not covered here. To go straight to the source and identify your own highest conviction plays, head into the U.S. Power Grid and Electrification Providers to Data Centers screener.
Fluence Energy (FLNC)
Overview: Fluence Energy provides grid scale battery storage systems and optimization software that help keep power reliable for energy hungry AI data centers and electrified networks.
Operations: Fluence Energy generates virtually all of its US$2.6b revenue from batteries and battery systems, with reported sales across APAC and EMEA regions.
Market Cap: US$1.4b
Fluence Energy matters for this screener because its storage hardware and software sit where AI driven data center demand meets grid reliability concerns.
"Rapid global electrification and surging power demand, driven by data centers, transportation, and industrial sectors, are expected to sharply increase the need for grid resilience and flexibility, leading to substantial projected growth for large-scale battery storage. Persistent tariff and trade policy uncertainty, especially the sharp rise in U.S. tariffs on Chinese battery imports to 155%, has resulted in paused contract execution and a $700 million reduction in near-term revenue guidance, introducing risk to the timing and realization of future revenue and compressing EBITDA."
For Fluence Energy, much of the long term upside on offer will depend on how one unresolved cost pressure shapes eventual margins.
That pressure point is where the story gets interesting, and the full narrative for Fluence Energy pulls together how Fluence Energy’s storage footprint, contract pipeline, and policy risks might be decoupling.

SOLV Energy (MWH)
Overview: SOLV Energy designs, builds, and maintains large scale solar, battery storage, and grid infrastructure in the U.S. for utilities and power producers.
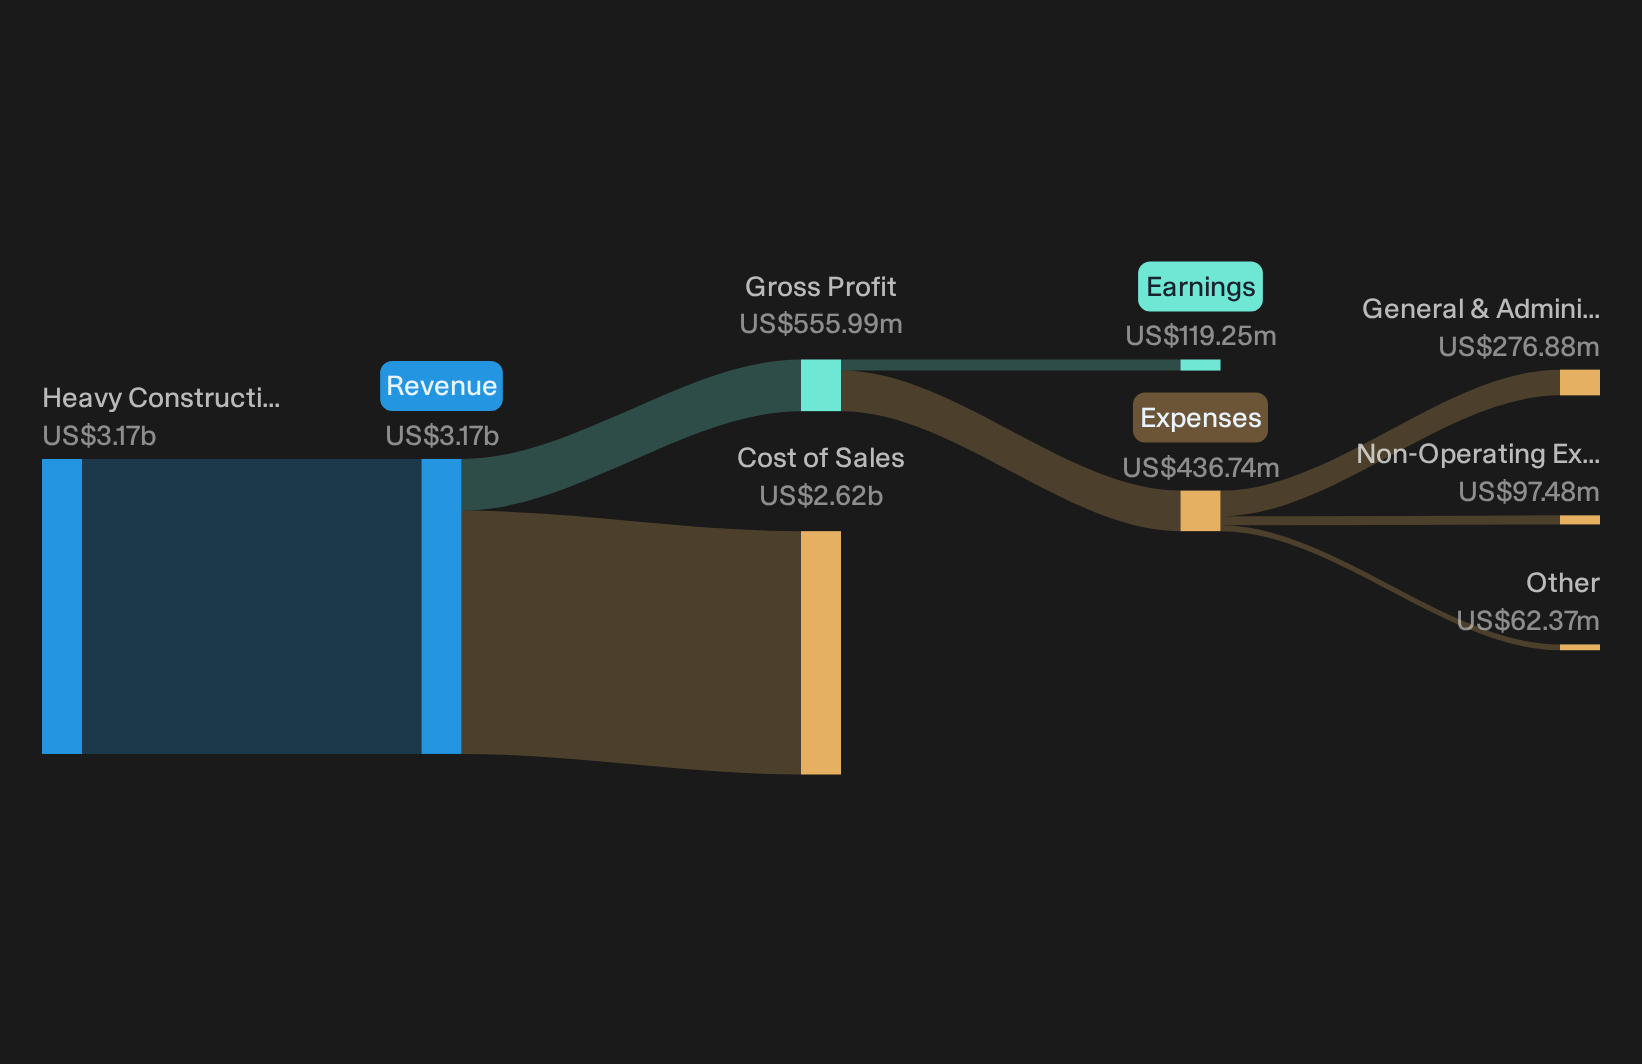
Operations: SOLV Energy generates all of its US$3.2b revenue from heavy construction services in the United States, focused on power infrastructure.
Market Cap: US$5.4b
SOLV Energy is tightly linked to the screener theme because its heavy construction work covers U.S. substations, transmission lines, and distribution projects that feed power hungry data centers. The business reports US$3.2b of U.S. revenue and recently pointed to rising electricity demand tied to AI infrastructure and industrial reshoring, with contract profitability hinging on how one unseen pressure in large, fixed price grid projects plays out.
That contract risk is where the analysis report for SOLV Energy could help you see whether SOLV Energy’s AI grid work is accelerating faster than the pricing pressure.
Primoris Services (PRIM)
Overview: Primoris Services builds and maintains natural gas and electric utility lines, transmission systems, and energy projects that support power hungry data centers.
Operations: Primoris Services generates about US$4.6b from Energy segment work and US$2.8b from Utilities projects, almost entirely in the United States.
Market Cap: US$4.2b
Primoris Services matters for this power grid screener because its crews are in the trenches building the transmission, distribution, and power projects that keep large U.S. data centers and electrification efforts supplied with reliable electricity.
"Surging demand from data center development, including $1.7 billion of potential contracts being pursued, is creating incremental, higher-margin project opportunities across site prep, power generation, utility, and fiber network services, which is likely to lift future revenues and segment profitability."
For Primoris Services, what happens to those higher-margin projects if one pressure on future project profitability moves the wrong way will really matter.
If that pressure shifts in your favour, the full narrative for Primoris Services shows how Primoris Services’ data center pipeline could accelerate while contract risk stays contained.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Stocks gaining momentum, breaking out, or dropping into value territory rarely stay under the radar for long, so act now and get in early.
- Spot early breakouts in niche miners before momentum is fully priced by scanning the curated 36 best rare earth metal stocks while they are still under the radar for now.
- Track cash generating AI leaders that are already past the burn phase by running the focused 38 profitable AI stocks that aren't just burning cash while the window for mispricing still matters.
- Target resilient businesses with room to compound by reviewing the hand picked list of solid balance sheet and fundamentals (23 results) before that financial strength is fully caught in the price.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com