
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Asian Growth Companies With High Insider Ownership In September 2026
In September 2026, the Asian markets have been navigating a complex landscape marked by fluctuating oil prices and evolving monetary policies, with Japan's recent rate hike drawing particular attention. Amidst these broader economic shifts, growth companies with high insider ownership continue to capture investor interest due to their potential for alignment of interests between management and shareholders.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 126% |
| Ningbo Sanxing Medical ElectricLtd (SHSE:601567) | 24.9% | 56.8% |
| Meiko Electronics (TSE:6787) | 19.2% | 33.8% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| HUMAN MADE (TSE:456A) | 23.9% | 29.8% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's explore several standout options from the results in the screener.
Sigenergy Technology (SEHK:6656)
Simply Wall St Growth Rating: ★★★★★★
Overview: Sigenergy Technology Co., Ltd focuses on developing and manufacturing energy storage systems, inverters, and smart energy solutions for various applications, with a market cap of approximately HK$83.86 billion.
Operations: The company generates revenue from its Batteries / Battery Systems segment, which amounts to CN¥16.14 billion.
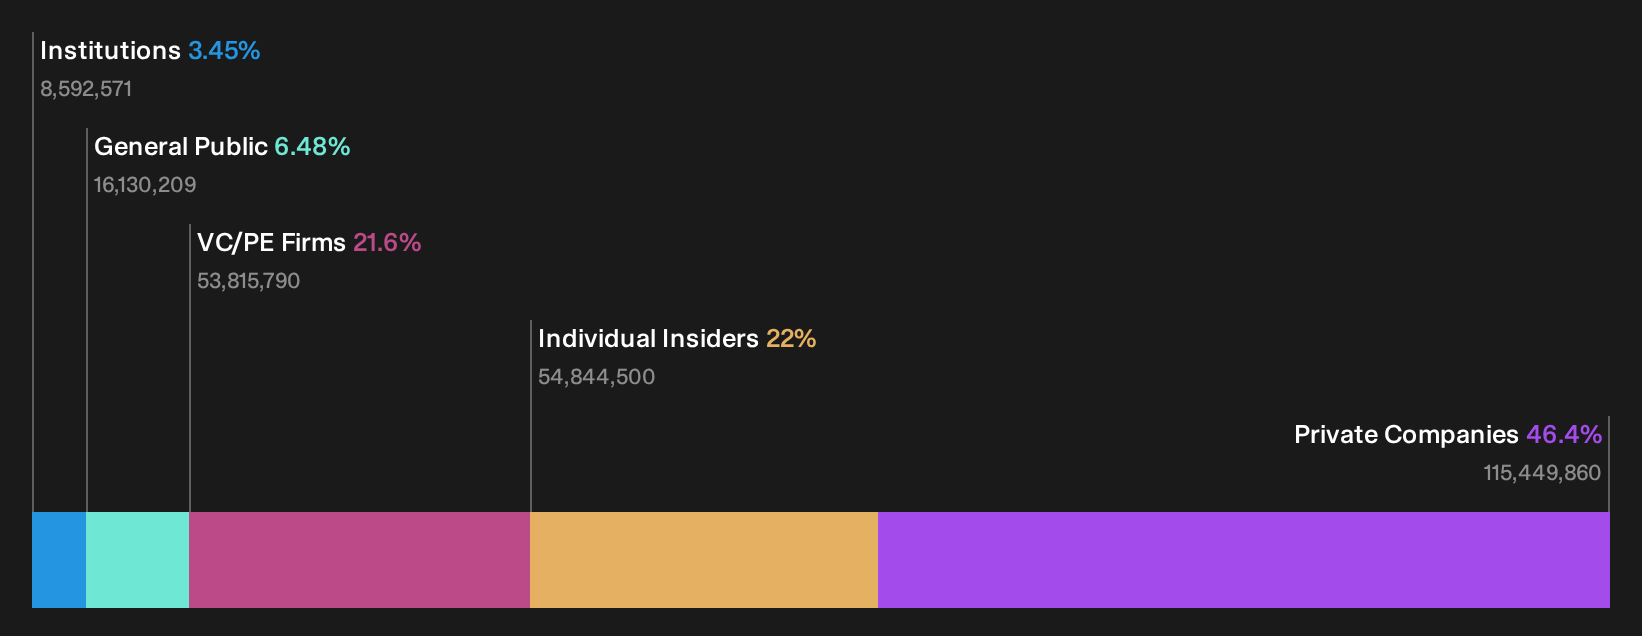
Insider Ownership: 22%
Return On Equity Forecast: 39% (2029 estimate)
Sigenergy Technology, a growth company with significant insider ownership, is poised for robust expansion. Its revenue and earnings are forecast to grow significantly faster than the market, with expected annual revenue growth of 35.3% and earnings growth of 26.1%. Recent strategic expansions into commercial and utility-scale applications demonstrate its commitment to diversifying beyond residential energy storage. However, investors should note the company's highly volatile share price over the past three months.
- Get an in-depth perspective on Sigenergy Technology's performance by reading our analyst estimates report here.
- According our valuation report, there's an indication that Sigenergy Technology's share price might be on the cheaper side.
Farsoon Technologies (SHSE:688433)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Farsoon Technologies Co., Ltd. manufactures and supplies industrial polymer and metal laser powder bed fusion systems across various regions, including China, North America, the Asia Pacific, Europe, the Middle East, and Africa; it has a market cap of CN¥39.19 billion.
Operations: Farsoon Technologies generates revenue from its Machinery & Industrial Equipment segment, amounting to CN¥816.63 million.
Insider Ownership: 10.4%
Return On Equity Forecast: N/A (2029 estimate)
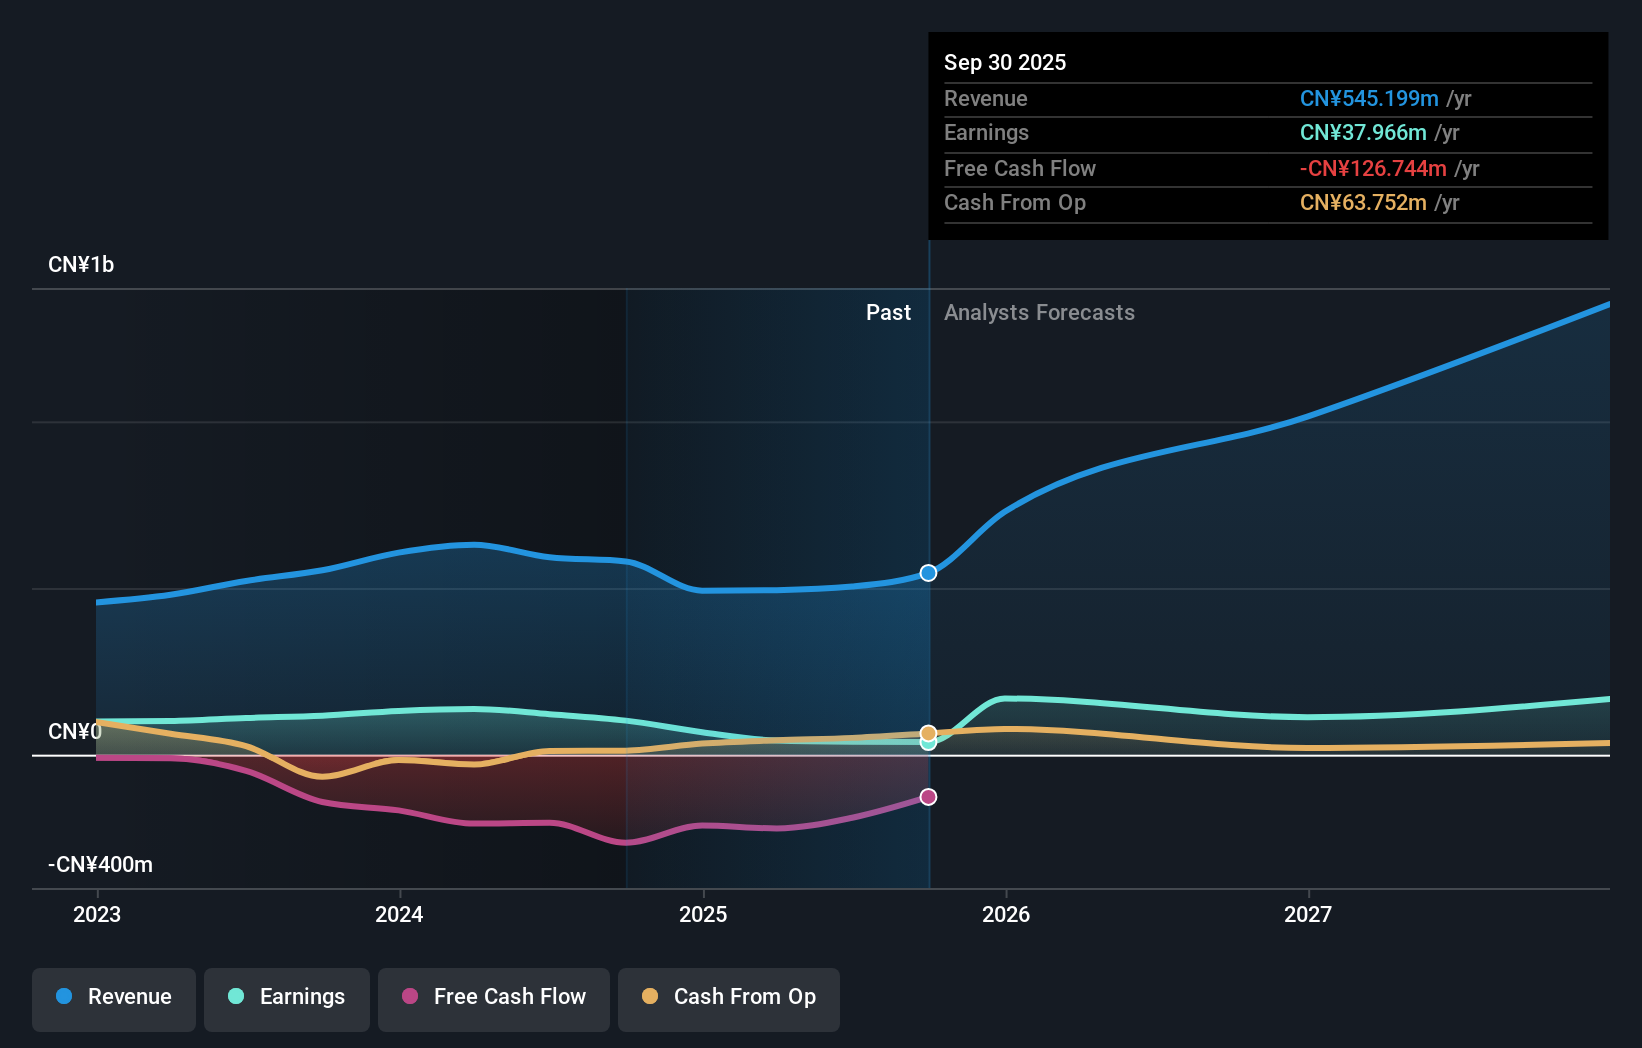
Farsoon Technologies is experiencing substantial growth, with earnings rising by 87.9% over the past year and revenue forecast to grow at 29.2% annually, outpacing the broader Chinese market. Recent H1 2026 results show a significant increase in sales and net income compared to the previous year, highlighting its strong performance trajectory. However, investors should be cautious of its highly volatile share price in recent months despite limited insider trading activity.
- Navigate through the intricacies of Farsoon Technologies with our comprehensive analyst estimates report here.
- Our comprehensive valuation report raises the possibility that Farsoon Technologies is priced higher than what may be justified by its financials.
Yushu Technology (SHSE:688836)
Simply Wall St Growth Rating: ★★★★★★
Overview: Yushu Technology Co., Ltd. focuses on the research, development, production, and sale of consumer- and industry-class general-purpose legged and humanoid robots, with a market cap of CN¥208.29 billion.
Operations: Yushu Technology Co., Ltd.'s revenue is primarily derived from the research, development, production, and sale of both consumer- and industry-class general-purpose legged and humanoid robots.
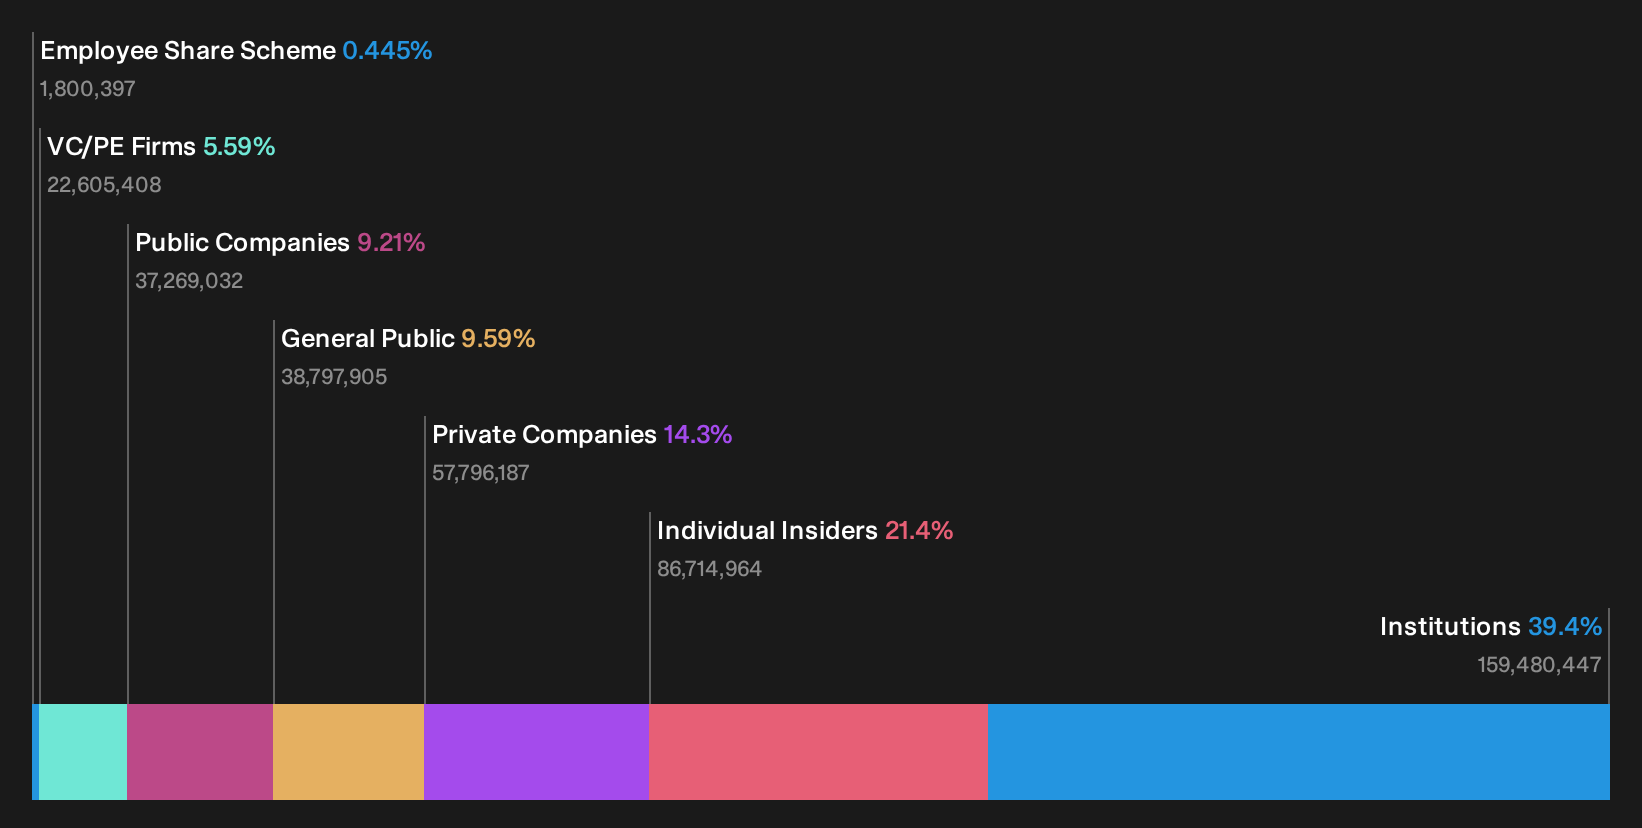
Insider Ownership: 21.4%
Return On Equity Forecast: 21% (2029 estimate)
Yushu Technology has shown impressive growth, with recent H1 2026 results revealing a net income of CNY 274 million compared to a loss last year. Revenue surged to CNY 1.15 billion from CNY 775.72 million, indicating strong performance. The company's earnings and revenue are forecasted to grow significantly faster than the market, yet shares remain highly illiquid. A recent IPO raised CNY 6.10 billion, reflecting confidence but also highlighting potential liquidity issues for investors.
- Take a closer look at Yushu Technology's potential here in our earnings growth report.
- Our valuation report unveils the possibility Yushu Technology's shares may be trading at a premium.
Next Steps
- Get an in-depth perspective on all 495 Fast Growing Asian Companies With High Insider Ownership by using our screener here.
- Contemplating Other Strategies? The end of cancer? These 35 emerging AI stocks are developing tech that will allow early idenification of life changing disesaes like cancer and Alzheimer's.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com