
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Undiscovered Asian Gems To Explore This September 2026
As September 2026 unfolds, the Asian markets are navigating a complex landscape marked by fluctuating oil prices and central bank rate hikes, with Japan's stock indices experiencing gains amid easing concerns over Middle East supply disruptions. In this environment of volatility and opportunity, identifying promising stocks requires a focus on companies that demonstrate resilience and adaptability in the face of economic shifts.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Apex Mining | 22.02% | 24.39% | 37.14% | ★★★★★★ |
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Management SolutionsLtd | 7.61% | 23.78% | 29.72% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 70.93% | 9.87% | 28.79% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Let's explore several standout options from the results in the screener.
Binjiang Service Group (SEHK:3316)
Simply Wall St Value Rating: ★★★★★☆
Overview: Binjiang Service Group Co. Ltd. operates in the People's Republic of China, offering property management and related services, with a market capitalization of approximately HK$5.72 billion.
Operations: The company generates revenue primarily from property management services (CN¥2.68 billion) and value-added services (CN¥1.19 billion), with additional income from value-added services to non-property owners (CN¥0.50 billion).
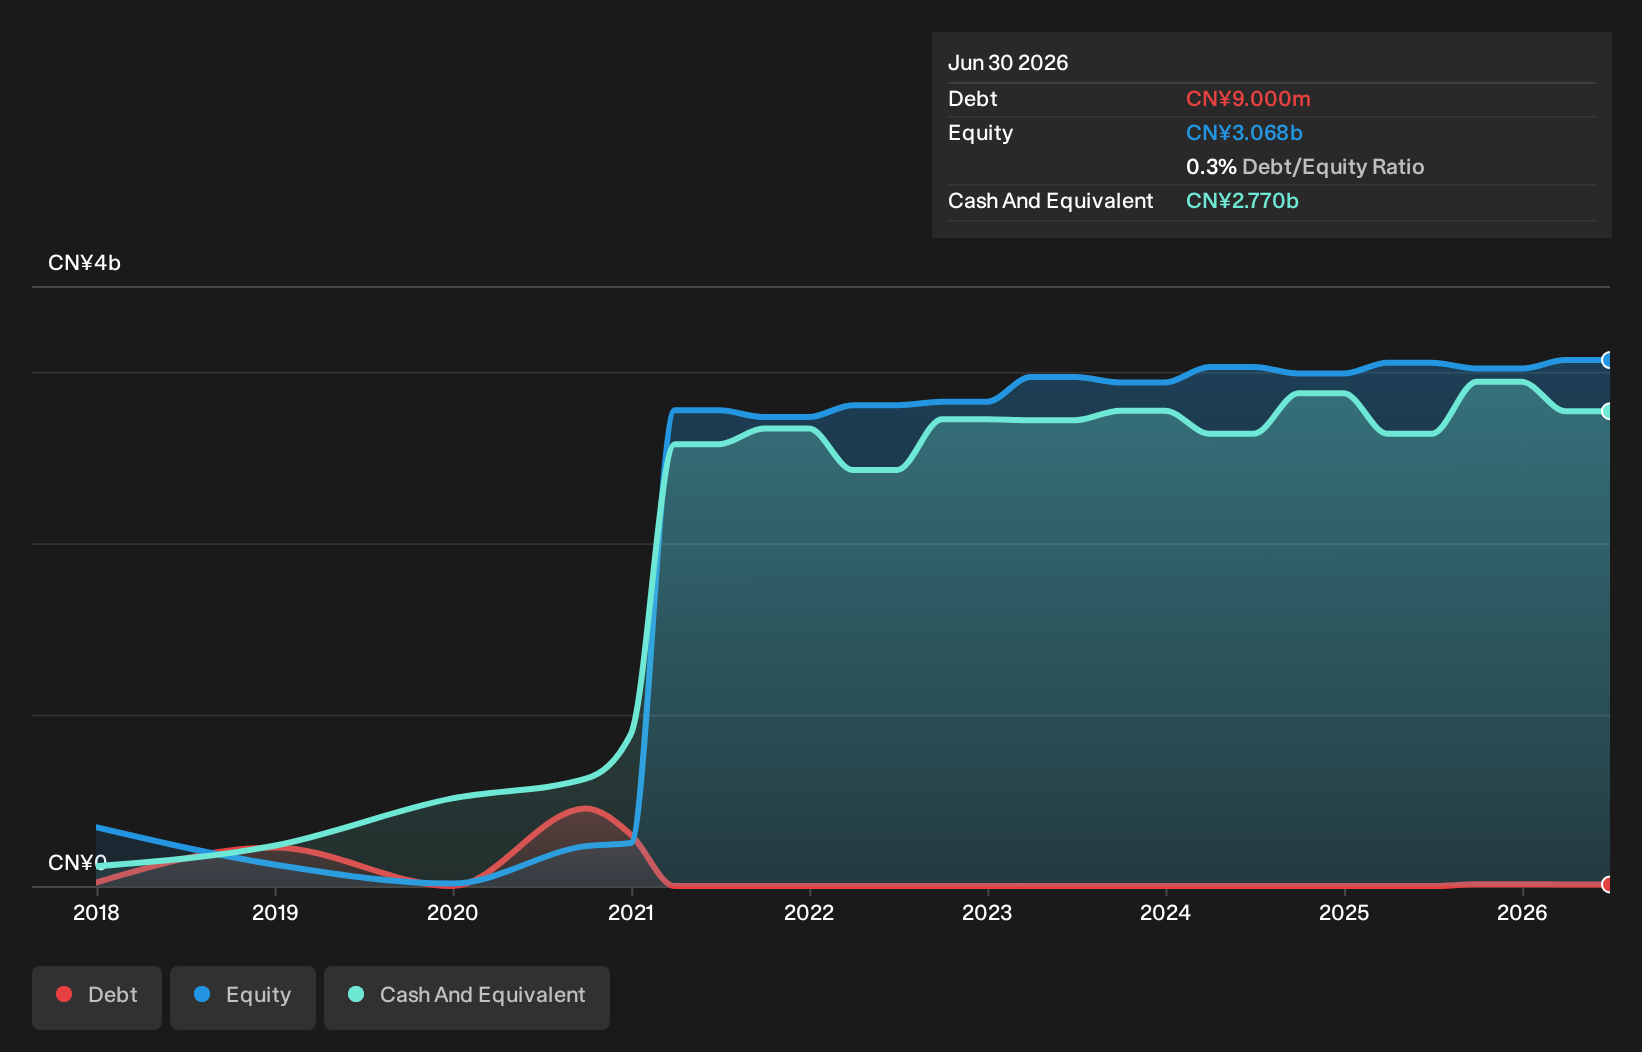
Binjiang Service Group, a notable player in its sector, reported impressive earnings growth of 5.9% over the past year, surpassing the Commercial Services industry's -7.7%. The company trades at 35.4% below its estimated fair value and maintains high-quality earnings with positive free cash flow. Its debt-to-equity ratio slightly increased to 0.2% over five years but remains manageable with more cash than total debt on hand. Recently, Binjiang announced an interim dividend of HKD 0.922 per share and reported half-year sales of CNY 2,298 million alongside net income of CNY 315 million, reflecting steady performance improvements from last year.

Cheerwin Group (SEHK:6601)
Simply Wall St Value Rating: ★★★★★☆
Overview: Cheerwin Group Limited is an investment holding company that manufactures and trades a range of products including household insecticides, repellents, cleaning products, air care, personal care items, and pet products in China with a market cap of HK$3.11 billion.
Operations: The company's primary revenue stream comes from Household Care, generating CN¥1.99 billion, followed by Pet Stores and Pet Products at CN¥236.29 million, and Personal Care at CN¥48.94 million. The net profit margin shows a notable trend in its financial performance over recent periods.
Cheerwin Group, a notable player in the household products sector, has demonstrated strong financial health with earnings growth of 32.8% over the past year, outpacing industry averages. The company's net income for the first half of 2026 reached CNY 212.16 million, up from CNY 173.56 million a year earlier, reflecting its robust performance and high-quality earnings profile. Trading at an attractive valuation—85.8% below estimated fair value—Cheerwin seems poised for continued growth with forecasted annual earnings increase of 13.15%. Recent dividend announcements further underscore its commitment to shareholder returns while maintaining more cash than total debt enhances financial stability.
- Get an in-depth perspective on Cheerwin Group's performance by reading our health report here.
Examine Cheerwin Group's past performance report to understand how it has performed in the past.
Inner Mongolia Xingye Silver & Tin Mining (SZSE:000426)
Simply Wall St Value Rating: ★★★★★★
Overview: Inner Mongolia Xingye Silver & Tin Mining Co., Ltd operates in the mining and beneficiation of non-ferrous and precious metals across China, Hong Kong, and Mongolia with a market capitalization of CN¥62.98 billion.
Operations: Xingye Silver & Tin Mining generates its revenue primarily from the mining industry, amounting to CN¥7.36 billion. The company's financial performance is highlighted by a notable net profit margin, which reflects its ability to convert sales into actual profit efficiently.
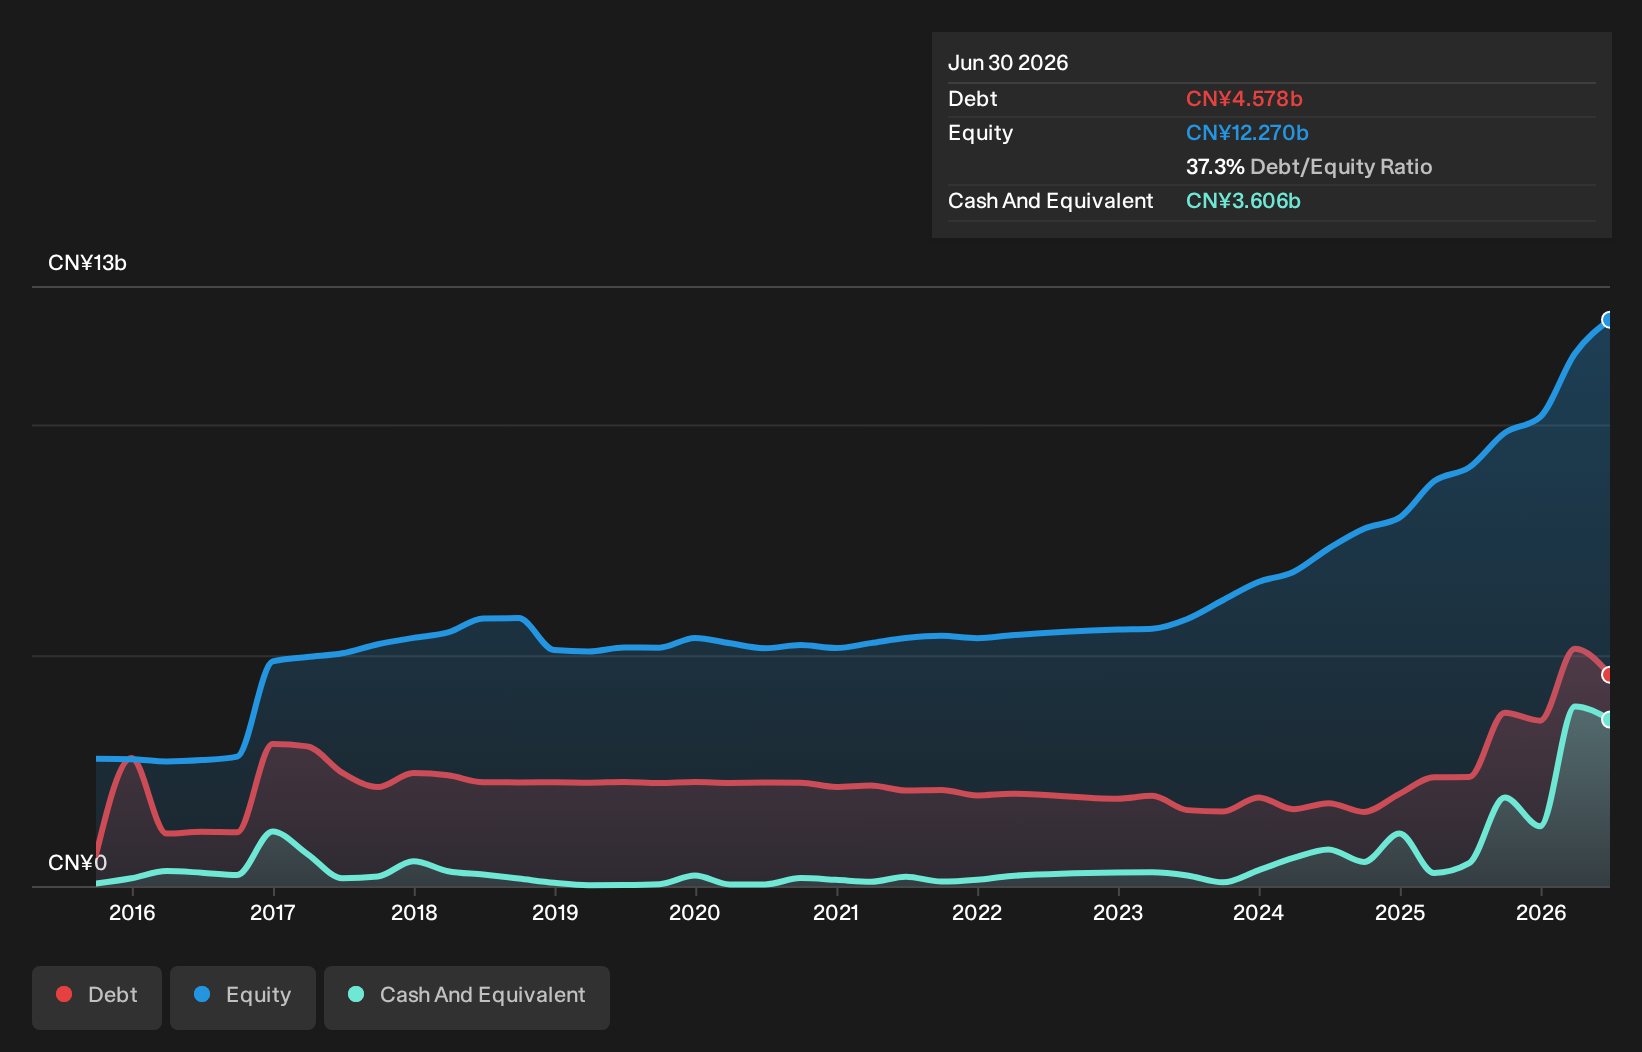
Inner Mongolia Xingye Silver & Tin Mining, with its recent earnings surge of 119.9% in the past year, stands out in the metals and mining sector. The company has a net income of CNY 2.26 billion for the half-year ending June 2026, up from CNY 795.68 million a year ago, reflecting strong operational performance. Trading at nearly 60% below estimated fair value suggests potential upside for investors seeking undervalued opportunities. Despite volatility in share price over three months, its debt to equity ratio improved slightly from 38.5% to 37.3% over five years, indicating prudent financial management amidst growth prospects forecasted at an annual rate of around 19%.
Turning Ideas Into Actions
- Click this link to deep-dive into the 117 companies within our Asian Undiscovered Gems With Strong Fundamentals screener.
- Are you invested in these stocks already? Keep abreast of every twist and turn by setting up a portfolio with Simply Wall St, where we make it simple for investors like you to stay informed and proactive.
- Streamline your investment strategy with Simply Wall St's app for free and benefit from extensive research on stocks across all corners of the world.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com