
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Gaming And Leisure Properties (GLPI) Stock Could Be Worth A Closer Look
Gaming and Leisure Properties has seen a mixed share price record, with the stock giving investors a positive 15.8% total return over the past 5 years but slipping over the shorter term. That combination highlights a straightforward question for you as a shareholder or prospective buyer: whether today's valuation can be explained by the earnings the business produces.
- The 15.8% gain over 5 years shows that long term holders have seen progress, which now raises the issue of whether the current earnings justify staying invested at this price.
- As a real estate investment trust focused on gaming properties, the group leans on rental income that can support relatively predictable earnings, so any change in lease structures or funding costs may feed directly into what you are effectively paying for each dollar of profit.
- The analysts covering Gaming and Leisure Properties have run their own numbers. See what analysts think Gaming and Leisure Properties's shares could be worth.
The stock's next move may depend on whether the current share price around US$39.59 is in line with what its earnings suggest is reasonable.
If you want to put Gaming and Leisure Properties' earnings based valuation question in context, you can compare it with a wider set of companies using the 35 high quality undervalued stocks.
Does Gaming and Leisure Properties Look Undervalued on Earnings?
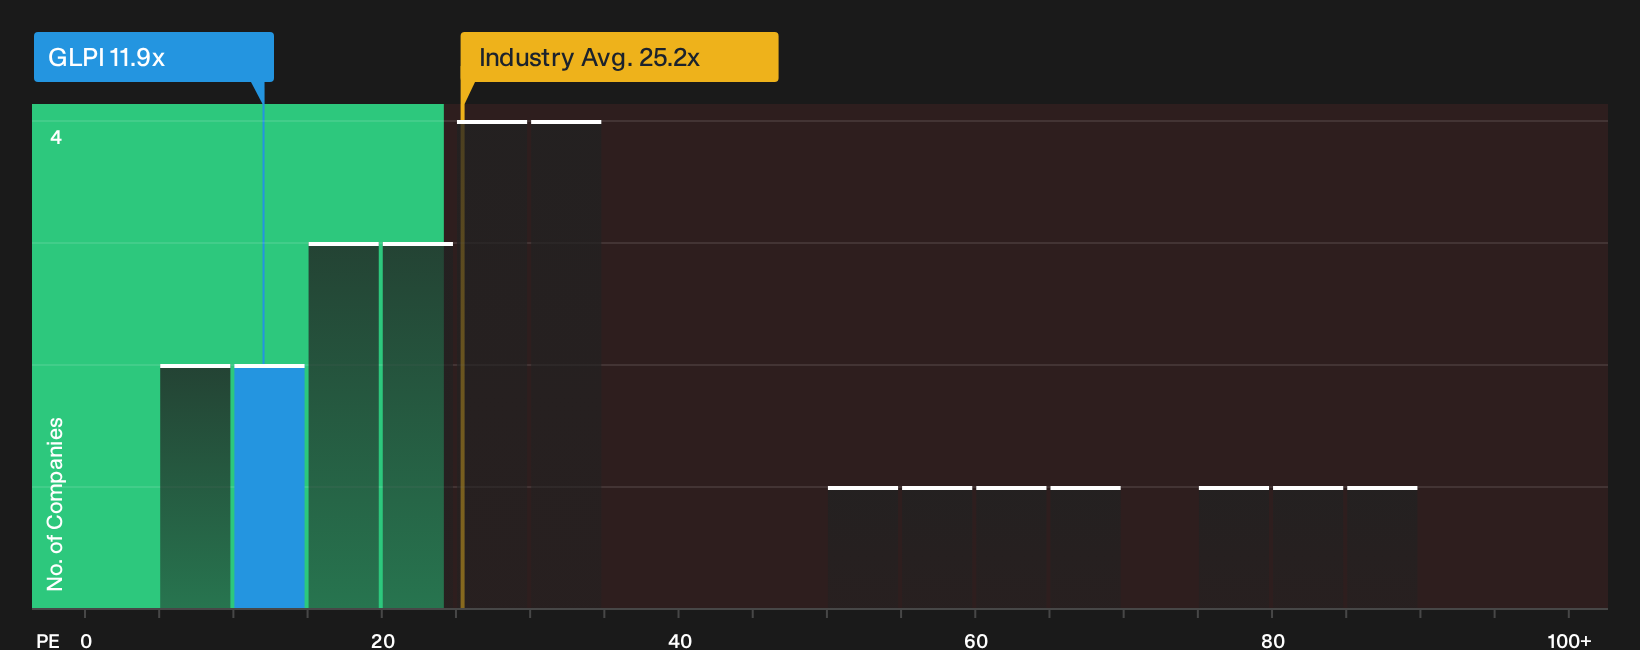
The P/E ratio is a useful lens for Gaming and Leisure Properties because it already factors in depreciation and interest, which matter a lot for a REIT that owns capital intensive assets. At a P/E of about 11.9x, the stock trades below both the Specialized REITs industry average of roughly 15.5x and the broader peer group on about 16.7x. That gap indicates the market is paying fewer dollars for each dollar of earnings than it does for many comparable property owners.
The Fair Ratio, which blends in Gaming and Leisure Properties' sector, business quality and risk profile, points to a higher P/E than the current level. That suggests the shares screen undervalued on this earnings based yardstick, although any conclusion still needs to factor in your view on future rent coverage, refinancing costs and the durability of its gaming tenant base. Explore the numbers behind Gaming and Leisure Properties's P/E valuation.
The Gaming and Leisure Properties Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Gaming and Leisure Properties valuation puzzle leaves off by spelling out which paths for future growth, margins and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than today. Rather than focusing on a single multiple or one model output, each narrative lays out the key building blocks behind its implied value so you can compare those assumptions with the company’s actual results over time.
A clear, number driven narrative on Gaming and Leisure Properties helps you pin down what you are really assuming about its growth, margins and execution over the next few years. Putting those expectations in writing makes it easier to test them against future earnings and adjust your view as new data arrives.
Share your own Narrative for Gaming and Leisure Properties and set out the assumptions behind your valuation.
One more critical piece for Gaming and Leisure Properties
Numbers only tell part of the story for Gaming and Leisure Properties, since the people setting priorities and how they are rewarded can strongly shape what those earnings look like over time. See who runs Gaming and Leisure Properties and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com