
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Aevis Victoria (SWX:AEVS) Undervalued On Half Year 2026 Results?
Aevis Victoria (SWX:AEVS) drew fresh attention after reporting half year 2026 results, with sales of CHF 639.1 million, revenue of CHF 547.02 million and net income of CHF 5.42 million.
Aevis Victoria’s latest figures have landed alongside a sharp swing in the share price, with a 7-day share price return of 24.9% and a 30-day move of 23.44% pushing the stock to CHF15.8. This comes even though the 3-year total shareholder return is down 15.06%, while the 5-year total shareholder return of 32.48% points to a longer, uneven journey where momentum has only recently started to rebuild.
See how Aevis Victoria compares to other healthcare and real asset operators that are attracting fresh interest after earnings with the hand picked list of solid balance sheet and fundamentals (198 results).
The jump to CHF15.8 has narrowed the gap to analyst and intrinsic value estimates, yet a spread still sits between the trading price and those benchmarks. Where does fair value really land for Aevis Victoria after this move?
Most Popular Narrative: 7% Undervalued
Against the latest close at CHF15.8, the most followed narrative pegs Aevis Victoria’s fair value at CHF17.0. This implies a modest valuation gap that rests on specific structural trends in healthcare and real assets.
The integrated care and VIVA capitation model sits directly on top of an aging population and rising chronic disease burden, and early evidence of cost optimization in existing regions suggests that growing membership beyond the breakeven level could support higher revenue visibility and contribute to improved earnings.
See why 1 investors see Aevis Victoria as 7% undervalued.
Result: Fair Value of CHF17.0 (UNDERVALUED)
Still, the Aevis Victoria story depends on lifting margins at acquired hospitals and improving low profitability in ambulatory care, both of which may prove slower or weaker than analysts expect.
Find out about the key risks to this Aevis Victoria narrative.
Another View on Aevis Victoria’s Valuation
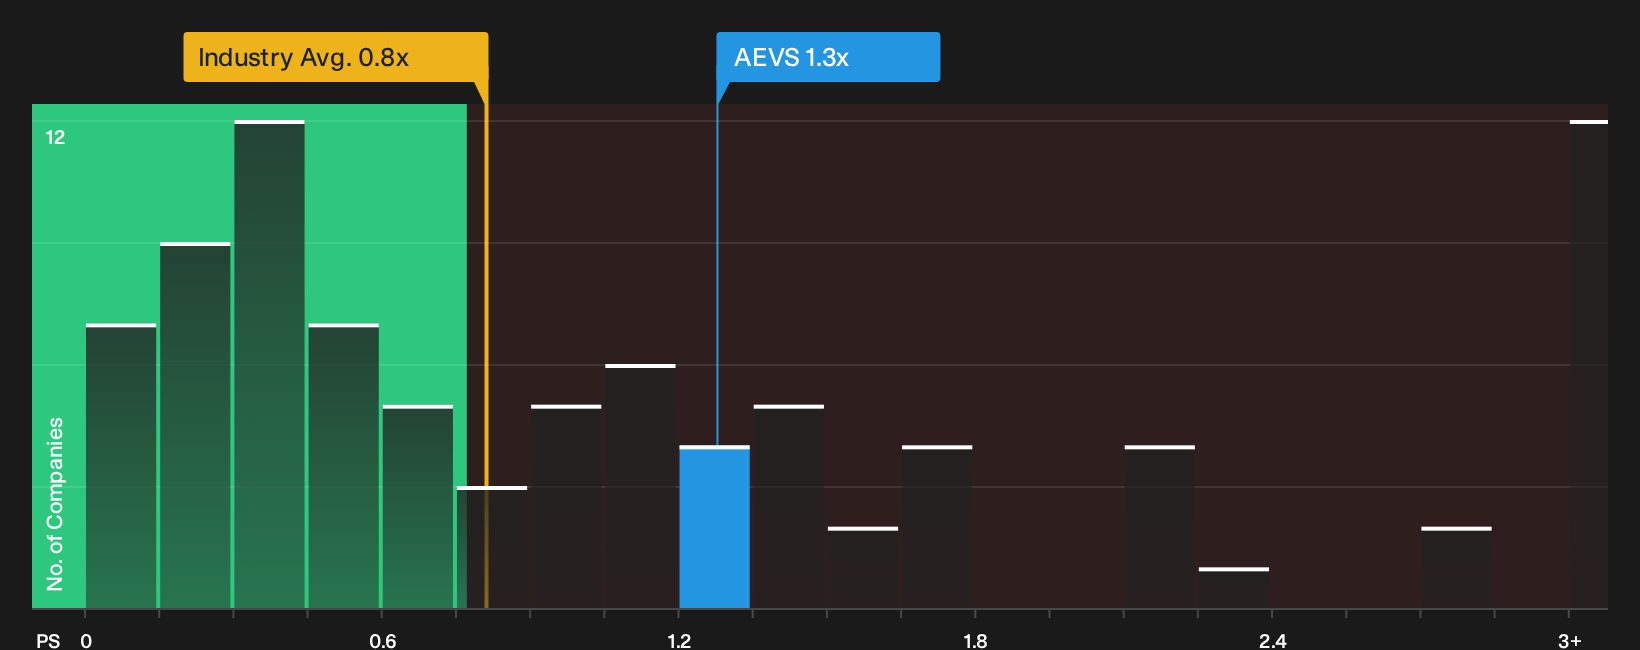
The first narrative leans on fair value at CHF17.0, yet the preferred sales multiple tells a different story. Aevis Victoria trades on a P/S ratio of 1.3x, while the fair ratio is 0.8x and the European healthcare group averages 0.8x. That gap points to valuation risk rather than a clear bargain. What matters more to you: the narrative or the numbers?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Aevis Victoria is mixed, so this is a moment to move fast, check the underlying numbers yourself, and stress test your view with the 3 important warning signs.
Looking for more investment ideas beyond Aevis Victoria?
Do not stop at Aevis Victoria alone. Broaden your watchlist and give yourself more options by checking ideas filtered for quality, resilience, and potential mispricing.
- Target businesses that combine solid fundamentals with attractive pricing using the 179 high quality undervalued stocks.
- Prioritize stability and sleep better at night by reviewing the 226 resilient stocks with low risk scores.
- Hunt for overlooked opportunities with strong financial profiles through the 614 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com