
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Nippon Yusen Kabushiki Kaisha (TSE:9101) Shares Sit 14% Above Fair Value On Consensus View
Nippon Yusen Kabushiki Kaisha (TSE:9101) has drawn renewed attention after a strong past 3 months, with the share price up about 44% and the year to date return near 46%.
That recent surge comes on top of a solid run for Nippon Yusen Kabushiki Kaisha, with the 90 day share price return of about 44% feeding into a 1 year total shareholder return of roughly 43% and a 5 year total shareholder return above 200%, which points to momentum that is still building rather than fading.
Scan the momentum story around Nippon Yusen Kabushiki Kaisha, and then broaden your watchlist with a curated set of 17 high quality undervalued stocks that also pair strong cash flows with solid balance sheets.
Nippon Yusen Kabushiki Kaisha has the profile of a broad, cash generating logistics group, and the share price has just sprinted ahead. The real test now is whether that strength is already fully reflected in the valuation.
Most Popular Narrative: 14% Overvalued
The most followed narrative currently places Nippon Yusen Kabushiki Kaisha’s fair value at about ¥6,585, which sits below the last close of ¥7,490 and frames the recent rally as moving ahead of that fair value line.
The analysts have a consensus price target of ¥6,585.45 for Nippon Yusen Kabushiki Kaisha based on their expectations of its future earnings growth, profit margins and other risk factors. However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of ¥8,800.0, and the most bearish reporting a price target of just ¥3,440.0.
See why 1 investors see Nippon Yusen Kabushiki Kaisha as 14% overvalued.
Result: Fair Value of ¥6,585 (OVERVALUED)
Still, Nippon Yusen Kabushiki Kaisha faces two clear swing factors: weaker freight rates from late in the fiscal year and any disruption linked to Middle East routes.
Find out about the key risks to this Nippon Yusen Kabushiki Kaisha narrative.
Another View: Nippon Yusen Kabushiki Kaisha Through Earnings Ratios
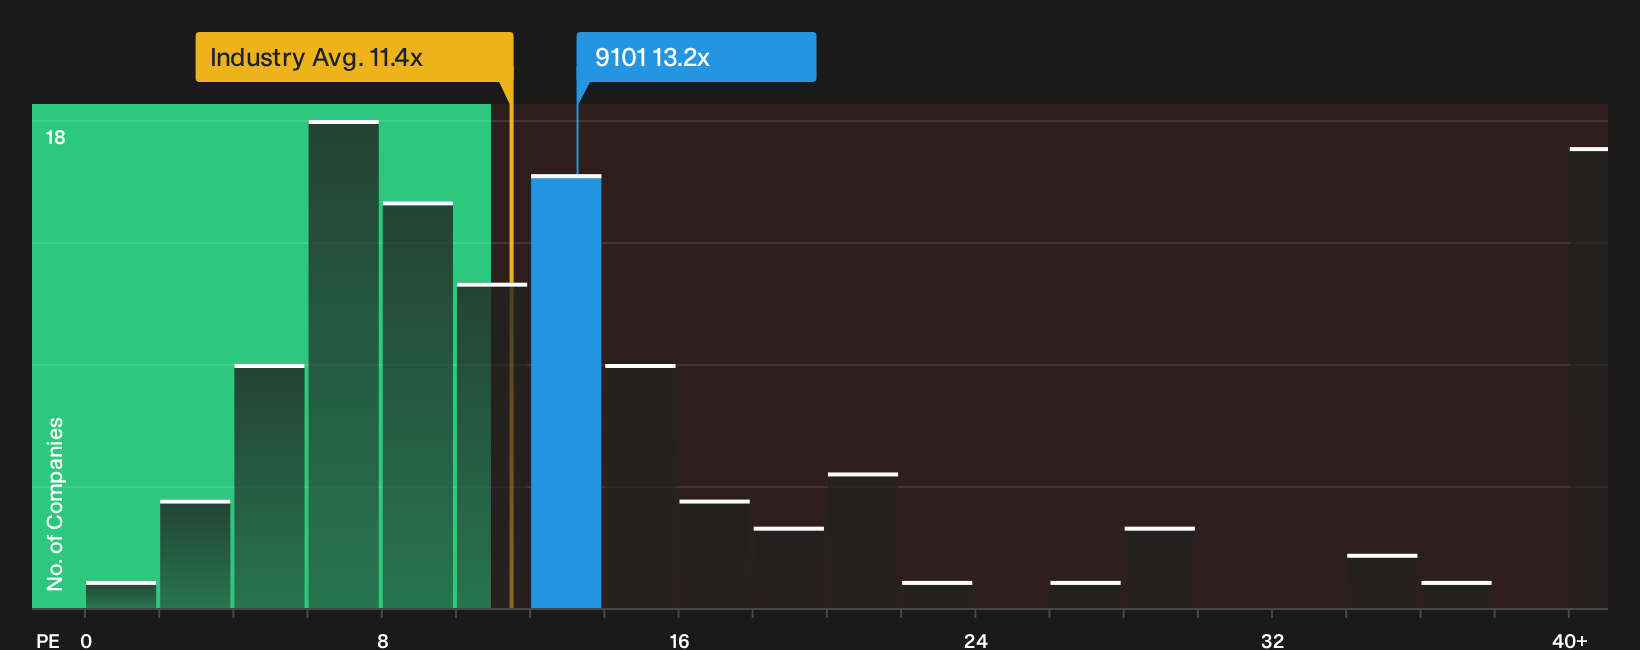
On simple earnings ratios, Nippon Yusen Kabushiki Kaisha looks less demanding. The stock trades on a P/E of 13.2x, compared with an estimated fair ratio of 17.3x, while the Asian Shipping group and direct peers sit closer to 11.4x and 11.5x. That mix of discount to fair ratio yet premium to sector raises a practical question for you: Is the higher tag a quality premium worth paying or a valuation risk if sentiment cools?
See what the numbers say about this price in more detail in the valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Nippon Yusen Kabushiki Kaisha is mixed, with clear risks on one side and meaningful positives on the other. Move quickly and weigh both angles for yourself using the 2 key rewards and 3 important warning signs.
Looking for more Nippon Yusen Kabushiki Kaisha style ideas?
If Nippon Yusen Kabushiki Kaisha is already on your radar, use this momentum as the spark to scan for other opportunities that fit your playbook.
- Target resilient compounding potential by reviewing companies screened for strong cash flows and attractive pricing through the 17 high quality undervalued stocks.
- Build reliable income streams by focusing on businesses highlighted as 14 dividend fortresses that may help anchor your portfolio when markets feel choppy.
- Protect your downside first by filtering for financially robust candidates in the list of solid balance sheet and fundamentals (21 results) before committing fresh capital.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com