
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Patterson-UTI Energy (PTEN) Draws Fresh Valuation Focus, Is It Still Below Fair Value?
Patterson-UTI Energy (PTEN) has come into focus after its shares closed at US$11.78, with a reported 129.8% total return over the past year despite the company posting a loss.
In the short term, the share price has pulled back, with a 7 day share price return of down 8.33% and a 1 month share price return of down 4.54%. However, Patterson-UTI Energy still shows strong momentum, with an 82.07% year to date share price return and a 129.77% 1 year total shareholder return.
Scan beyond Patterson-UTI Energy's recent surge and pullback by reviewing a curated list of oilfield and energy peers through the 35 high quality undervalued stocks, which may share similar momentum and valuation traits.
For Patterson-UTI Energy, a year of triple digit shareholder returns alongside a loss raises a simple tension. Are buyers responding to a sturdier business model, or just chasing sentiment around the recent move? And what does the current valuation suggest?
Most Popular Narrative: 14% Undervalued
Against the last close at $11.78, the most followed narrative on Patterson-UTI Energy points to a fair value of $13.75. This frames the recent share price pullback as a move that still leaves a valuation gap on the table.
Accelerating demand for U.S. natural gas due to new LNG export facilities coming online in 2026 and beyond is expected to drive higher drilling and completions activity, directly benefiting Patterson-UTI's topline revenue and rig utilization in gas-focused regions. Adoption and commercialization of differentiated automation, digital drilling, and emissions-reducing technologies (including the PTEN Digital Performance Center, Cortex automation suite, and Emerald 100%-natural-gas fleets) position Patterson-UTI to capture premium contract pricing and achieve structurally higher EBITDA margins.
See why 27 investors see Patterson-UTI Energy as 14% undervalued.
Result: Fair Value of $13.75 (UNDERVALUED)
Still, two pressure points could quickly challenge that 14% undervalued story for Patterson-UTI Energy, including softer drilling activity and heavy ongoing capital spending needs.
Find out about the key risks to this Patterson-UTI Energy narrative.
Another View on Patterson-UTI Energy’s Value
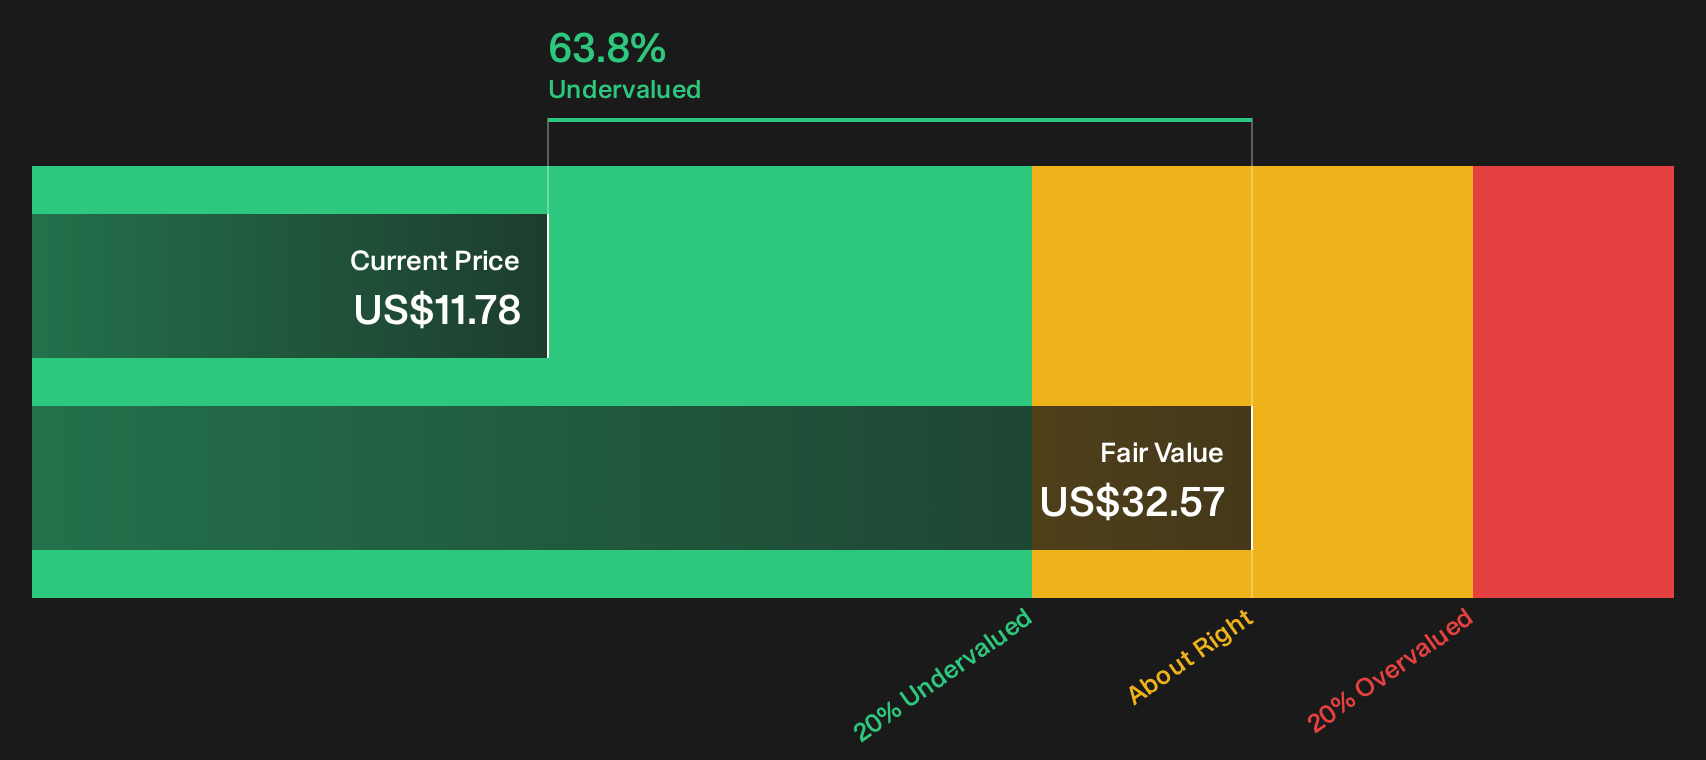
The DCF story points to a potential valuation gap, with Patterson-UTI Energy trading at $11.78 compared with an SWS DCF model estimate of $32.57. That is a very wide difference for any ticker built on forecasts and discount rates. The key question is how much confidence you place in those long range cash flow assumptions.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed sentiment around Patterson-UTI Energy’s recent move and valuation gap can cut both ways, so act while the data is fresh and form your own view with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Patterson-UTI Energy?
Do not stop with Patterson-UTI Energy alone. Broaden your watchlist using focused screeners that surface stocks aligned with the kind of opportunities you want to pursue.
- Target potential turnaround stories by scanning 9 elite penny stocks with strong financials. These can pair smaller market caps with stronger reported fundamentals than many investors expect.
- Prioritize value by using the 35 high quality undervalued stocks to spot companies where fair value estimates sit meaningfully above current market pricing.
- Focus on resilience and sleep-better-at-night positions through the 30 resilient stocks with low risk scores. This highlights businesses flagged with lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com