
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Community Microgrids Just Shift PG&E (PCG) Stock Narrative?
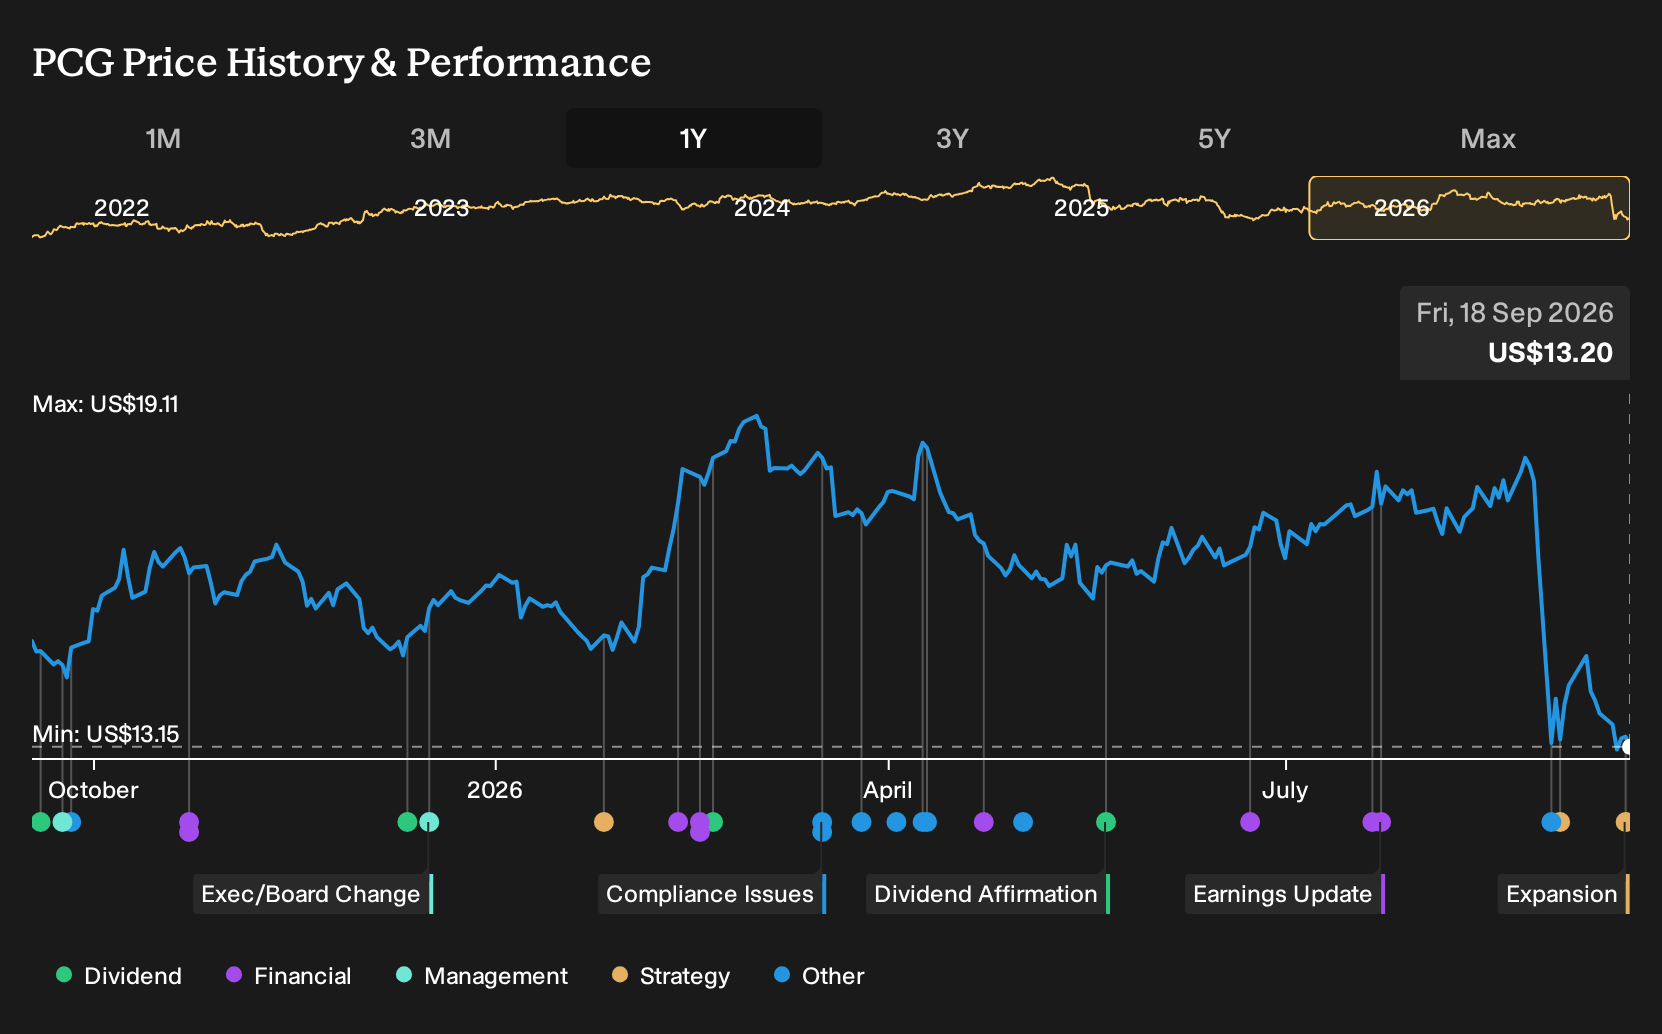
- PG&E Corporation recently declared a third quarter 2026 regular cash dividend of US$0.05 per share, while Pacific Gas and Electric Company advanced more than US$73 million of community microgrid investments across Northern and Central California after selecting six new projects and signing grant agreements for earlier awards.
- The fresh wave of community microgrids, including the Pescadero project designed to run most of the town for at least 24 hours on local solar and batteries, highlights how PG&E is trying to balance resilience spending with ongoing shareholder cash returns during a period of higher interest rates and capital needs.
- We will look at how PG&E's investment narrative is shaped by these new community microgrid commitments and resilience-focused spending.
PG&E Investment Narrative Recap
To own PG&E, you need to be comfortable with a heavily regulated utility that is investing heavily in wildfire mitigation and grid resiliency while carrying meaningful legal and financing risks. The recent US$0.05 dividend affirmation signals steady capital returns, but the short term focus still rests on execution of large capital programs and rate decisions.
The biggest near term swing factor remains how regulators treat cost recovery for this spending as interest rates move higher and interest coverage is already tight. Wildfire policy and any shift in the AB 1054 framework remain the primary risks that could raise required funding and increase earnings volatility.
The US$73 million community microgrid initiative is the most relevant current announcement for PG&E because it ties resilience spending directly to specific projects. These systems support outage performance and can help the utility serve new electrification and data center demand that analysts expect to drive load growth over the next several years.
For catalysts, investors are watching whether microgrid and broader grid modernization projects are treated as prudently incurred and earn an adequate regulated return. Any sign that regulators restrict recovery on this type of infrastructure, or tighten scrutiny given higher borrowing costs, would challenge the thesis that PG&E can grow its rate base while keeping earnings on a steadier path.
PG&E's narrative projects US$28.6b revenue and US$4.5b earnings by 2029. This assumes 3.4% yearly revenue growth and an earnings increase of roughly US$1.4b from US$3.1b today.
Uncover why PG&E's fair value indicates a 49% potential upside to its current price, a discount that could close quickly.
Exploring Other Perspectives
One bullish twist you might want to explore is how some analysts frame PG&E’s US$73b capital plan itself as the key upside. Before this dividend and microgrid news, the most optimistic forecasts were already baking in US$30.3b revenue and US$4.9b earnings by 2029. Those projections could shift meaningfully as this new spending round is digested.
Explore 2 other PG&E fair value estimates, including one that suggests as much as 49% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your PG&E research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for PG&E. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PG&E's overall financial health at a glance.
Looking for more PG&E-like investment ideas?
If the PG&E story has you thinking about how to position your portfolio for regulated returns, balance sheet strength, and resilience themes, it can help to widen the lens and scan a broader set of listed utilities and infrastructure plays.
- If capital preservation is near the top of your list, start with sturdier operators by screening for 30 resilient stocks with low risk scores that may offer a smoother ride through choppy markets.
- For readers hunting for value, cast a wider net over companies trading on more modest expectations by reviewing 35 high quality undervalued stocks that pass fundamental checks.
- Those who prefer durable business quality with room to grow can scan a 16 high quality undiscovered gems, which often sit outside the usual blue chip lists yet still show solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com