
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Lemonade (LMND) Expands In Kentucky, Is The Stock Fully Valued?
Lemonade expands renters coverage and steps onto the conference stage
Lemonade (LMND) just switched on renters insurance in Kentucky, widening its U.S. footprint as the insurer also prepares to showcase its model at the FT Partners FinTech Conference on September 15, 2026.
Recent moves like the Kentucky launch and the upcoming FT Partners appearance come against a weaker share price backdrop, with Lemonade’s stock down 11.77% on a 30 day share price return and 38.01% on a year to date share price return. At the same time, the 3 year total shareholder return sits at a very large gain that contrasts sharply with the 22.75% decline in the 1 year total shareholder return, suggesting that earlier optimism has cooled and investors are reassessing growth potential and risk around the current US$47.09 level.
Compare Lemonade’s pullback and expansion story with other hand picked insurers and fintechs on our 30 resilient stocks with low risk scores that aim for sturdier balance sheets and smoother return profiles.
Lemonade continues to expand its product footprint while the share price has retreated sharply. The business model may appeal, but is the current US$47.09 price offering real value or charging a premium for the story?
Most Popular Narrative: 3.8% Undervalued
Lemonade’s most followed narrative tags fair value at $48.95 against the recent $47.09 share price. This frames only a small implied gap and anchors the discussion on what actually has to go right in the operating story.
Ignore the 79%. In-force premium, the measure of how much insurance Lemonade actually has on the books, grew 32.4% to $1.43 billion. Revenue grew 79% because ceded premiums fell roughly 49% as the company retained a larger share of its own risk.
See why 2 investors see Lemonade as 4% undervalued.
Result: Fair Value of $48.95 (UNDERVALUED)
Still, the thesis around Lemonade can unravel fast if the gross loss ratio climbs back toward 70% or if in force premium growth slows meaningfully from recent levels.
Find out about the key risks to this Lemonade narrative.
Another View on Lemonade’s Valuation
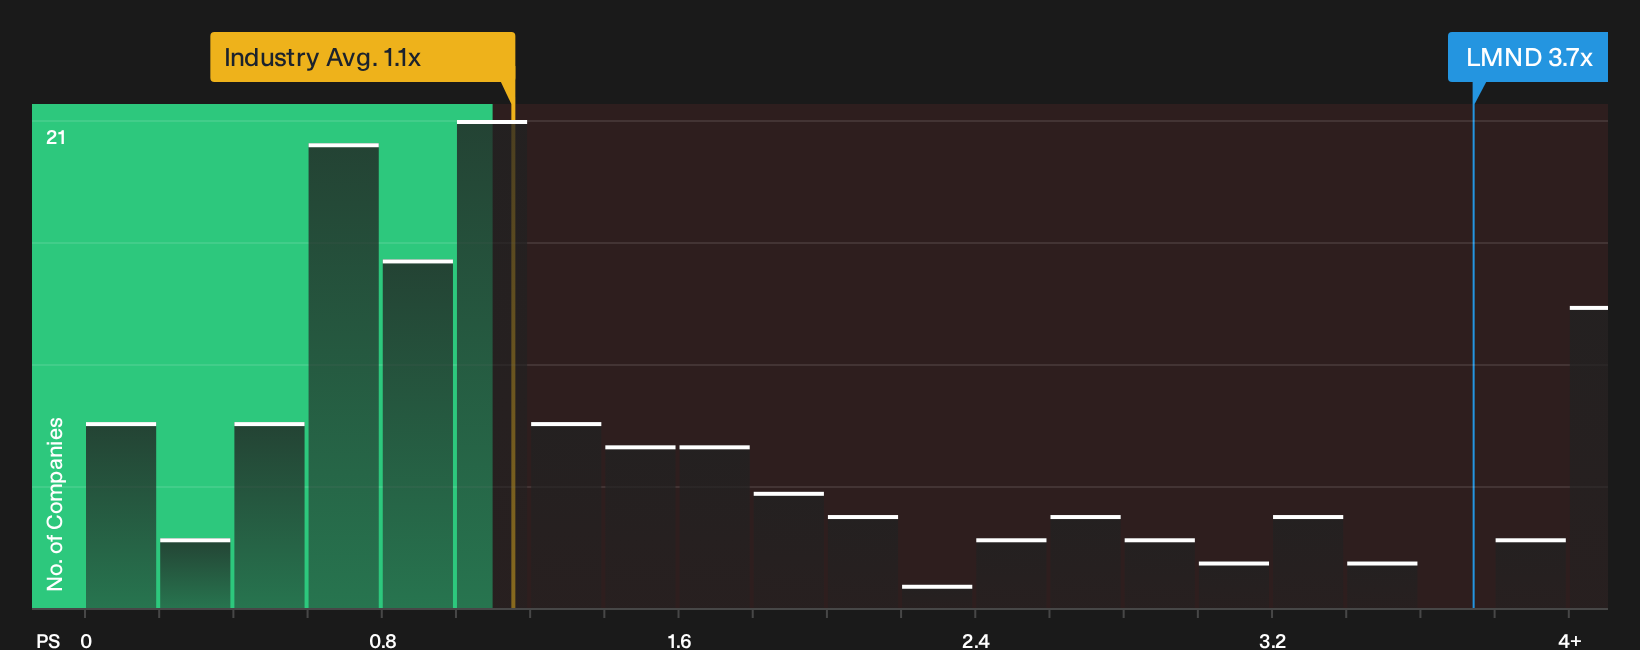
The first narrative paints Lemonade as 3.8% undervalued with a fair value of $48.95. A different lens tells a harsher story. On P/S, the stock trades at 3.7x compared with 1.1x for the US Insurance industry, 1.9x for peers and a fair ratio of 1.8x that the market could move toward.
That gap leaves investors weighing whether they are paying up for future growth that still needs to translate into profits, or backing away from a setup where any disappointment could pressure the multiple hard.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone on Lemonade so far feels familiar, that is the point; markets rarely agree for long. Act while the data is fresh, weigh both caution and optimism, then test your own judgment against 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Lemonade?
Do not stop with a single ticker. Your next strong investment candidate could already fit your criteria, and skipping the search now risks missing a clear opportunity.
- Zero in on potential bargains by scanning a curated set of companies that trade below their assessed worth using the 35 high quality undervalued stocks.
- Target resilient balance sheets by filtering for dependable businesses that pair financial strength with solid fundamentals through the list of solid balance sheet and fundamentals (23 results).
- Hunt for overlooked opportunities by reviewing a focused collection of quality stocks that have not yet drawn broad attention with the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com