
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Asian Growth Companies With High Insider Ownership September 2026
In September 2026, the Asian markets are navigating a complex landscape marked by global rate hikes and fluctuating oil prices, which have sparked inflation concerns and influenced investor sentiment. Amidst these challenges, growth companies with high insider ownership often stand out due to their potential for robust internal alignment and long-term vision, making them noteworthy considerations in today's volatile environment.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Zhejiang Taotao Vehicles (SZSE:301345) | 27.9% | 30.6% |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 126% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 116.3% |
| Meitu (SEHK:1357) | 22.9% | 30.7% |
| L&C BIOLTD (KOSDAQ:A290650) | 20.9% | 163% |
| HUMAN MADE (TSE:456A) | 23.9% | 29.8% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 31.9% |
| Fulin Precision (SZSE:300432) | 11.2% | 66.5% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's explore several standout options from the results in the screener.
Sieyuan Electric (SZSE:002028)
Simply Wall St Growth Rating: ★★★★★★
Overview: Sieyuan Electric Co., Ltd. specializes in the design, R&D, manufacturing, sale, service, and EPC of power transmission and distribution equipment globally with a market cap of CN¥108 billion.
Operations: The company's revenue from the Transmission and Distribution Equipment Industry is CN¥23.84 billion.
Insider Ownership: 35%
Earnings Growth Forecast: 30.6% p.a.
Sieyuan Electric demonstrates strong growth potential, with revenue expected to grow 26.7% annually, outpacing the broader Chinese market. The company's earnings are also projected to increase significantly at 30.6% per year over the next three years. Recent business expansions and product certifications bolster its global presence in key markets like North America and Southeast Asia. Despite an unstable dividend track record, Sieyuan's competitive price-to-earnings ratio suggests it offers good value relative to the market average.
- Take a closer look at Sieyuan Electric's potential here in our earnings growth report.
- Our comprehensive valuation report raises the possibility that Sieyuan Electric is priced lower than what may be justified by its financials.
Shenzhen Envicool Technology (SZSE:002837)
Simply Wall St Growth Rating: ★★★★★★
Overview: Shenzhen Envicool Technology Co., Ltd. offers temperature control and energy-saving solutions both in China and internationally, with a market cap of CN¥80.82 billion.
Operations: The company generates revenue from its Precision Temperature Control Energy Saving Equipment segment, amounting to CN¥6.51 billion.
Insider Ownership: 17.1%
Earnings Growth Forecast: 58.7% p.a.
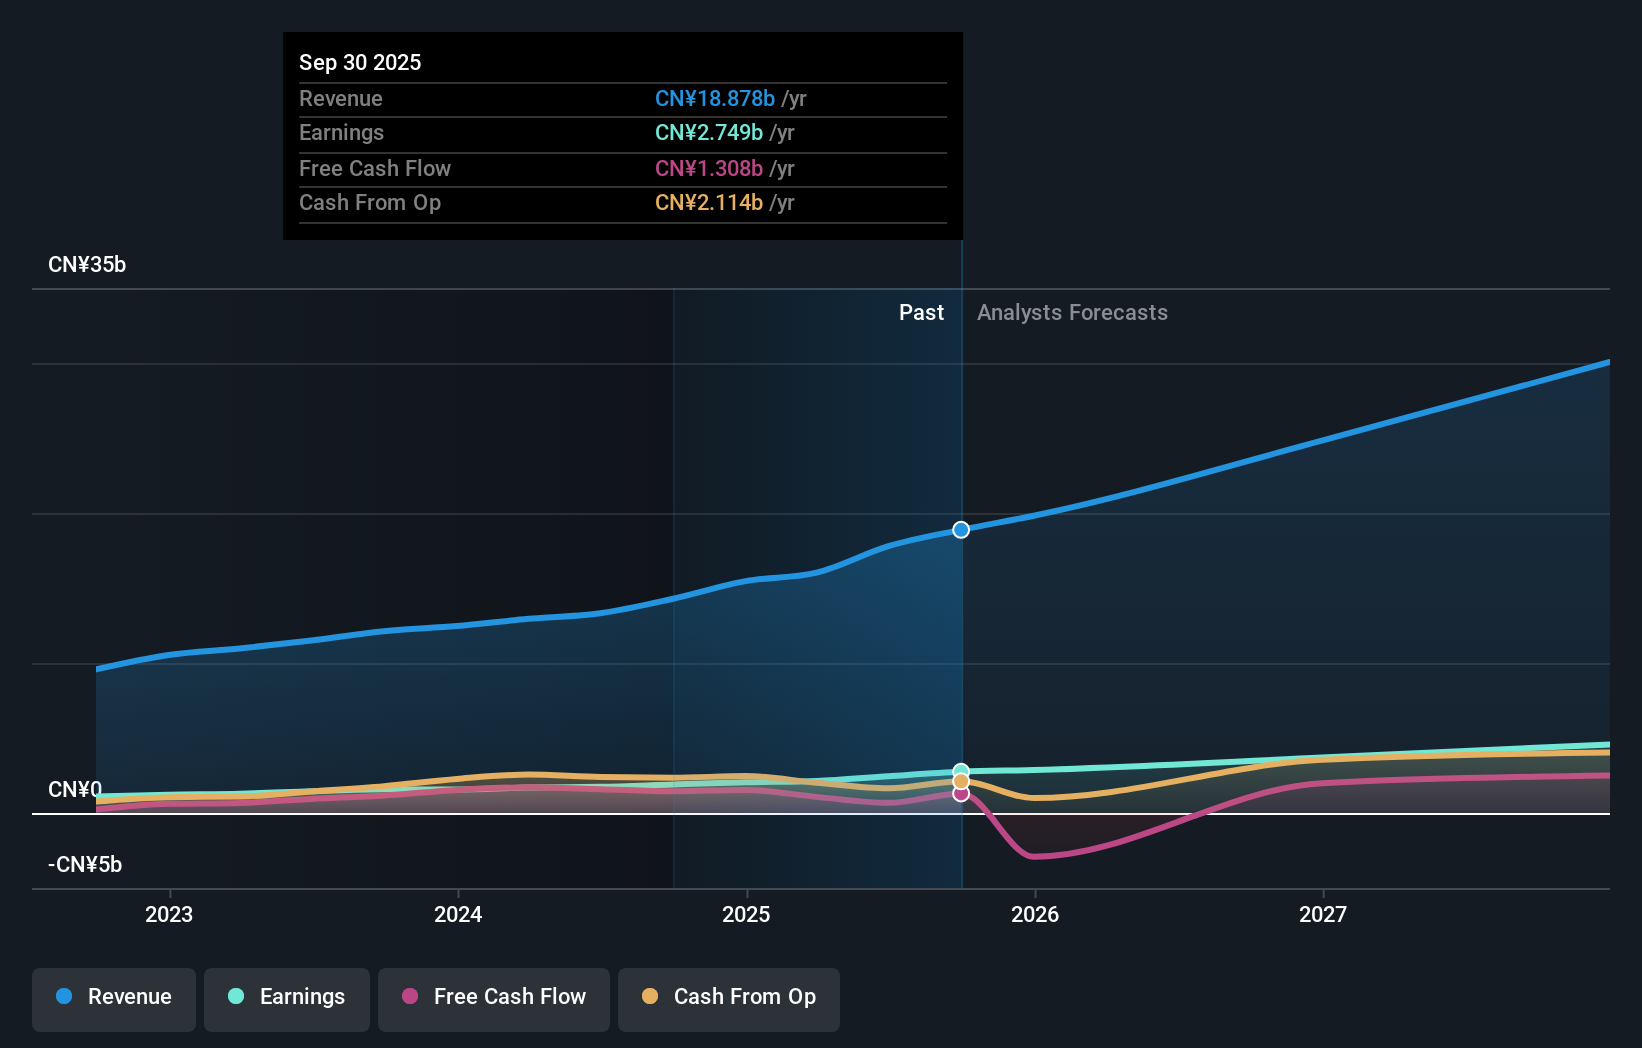
Shenzhen Envicool Technology shows promising growth potential with revenue forecasted to grow at 39.8% annually, surpassing the broader Chinese market. Despite a recent decline in net income for the first half of 2026, earnings are expected to increase significantly by 58.7% per year over the next three years. The company maintains high insider ownership and stable return on equity projections, enhancing investor confidence despite short-term earnings volatility.
- Click here and access our complete growth analysis report to understand the dynamics of Shenzhen Envicool Technology.
- Upon reviewing our latest valuation report, Shenzhen Envicool Technology's share price might be too optimistic.
Voltronic Power Technology (TWSE:6409)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Voltronic Power Technology Corp., along with its subsidiaries, manufactures and sells uninterruptible power systems (UPS) in Taiwan and Mainland China, with a market cap of NT$87.19 billion.
Operations: The company generates revenue primarily through the manufacturing and trading of uninterruptible power systems and inverters, amounting to NT$19.58 billion.
Insider Ownership: 21%
Earnings Growth Forecast: 29.2% p.a.
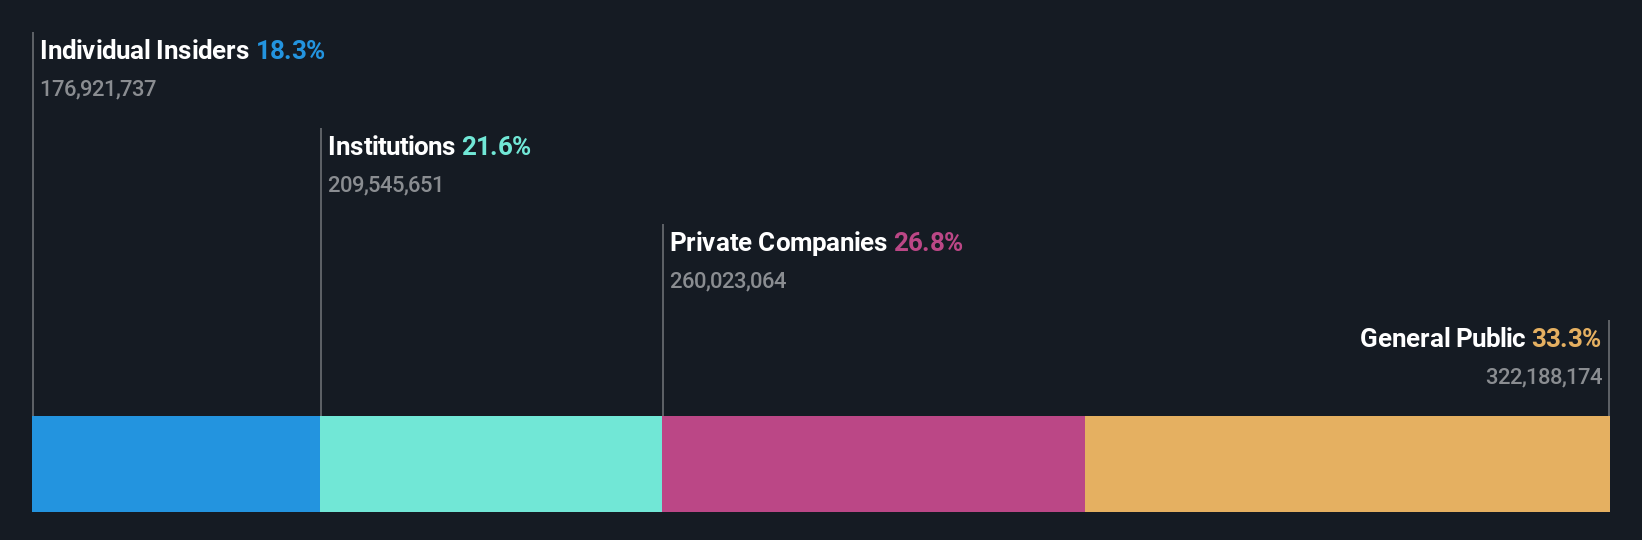
Voltronic Power Technology is poised for significant earnings growth of 29.19% annually over the next three years, outpacing the Taiwanese market's average. Despite this, revenue growth at 11.3% per year lags behind market expectations and recent earnings have declined, with net income halving in the second quarter compared to last year. The company's return on equity is projected to be very high at 41.1%, although profit margins have decreased from last year’s levels.
- Click to explore a detailed breakdown of our findings in Voltronic Power Technology's earnings growth report.
- Our comprehensive valuation report raises the possibility that Voltronic Power Technology is priced higher than what may be justified by its financials.

Key Takeaways
- Unlock our comprehensive list of 495 Fast Growing Asian Companies With High Insider Ownership by clicking here.
- Seeking Other Investments? These 25 companies survived and thrived after COVID and have the right ingredients to survive Trump's tariffs. Discover why before your portfolio feels the trade war pinch.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com