
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Parker-Hannifin (PH) Could Be 19% Undervalued As Fresh Debt Refinancing Raises The Question
Parker-Hannifin (PH) just completed twin debt offerings totaling about US$2.4b and €2.0b in senior notes. The financing focuses on refinancing existing borrowings tied to past acquisition activity.
Parker-Hannifin’s recent flurry of bond issuance and credit facility activity has taken place against a softer tape, with the 30-day share price return down 5.81% and the 7-day share price return slightly lower, even as the 1-day share price move of 1.97% hints at short-term buyers stepping back in.
Zooming out, the contrast is sharp: the total shareholder return over 1 year is 25.90%, over 3 years is about 15x, and over 5 years is about 3.5x. This signals that despite recent share price weakness, longer term momentum has been strong as debt funded acquisitions and product partnerships, like the Axora Medical distribution deal, reshape the story.
Scan Parker-Hannifin alongside a curated list of solid balance sheet and fundamentals (23 results) that, like PH, rely on scale, diversified revenue and disciplined financing decisions to reshape their capital structure.
The share price has cooled while Parker-Hannifin leans on fresh bond funding to tidy up past deal financing. Does that combination justify stepping in at US$943, or does patience still look cheaper?
Most Popular Narrative: 19% Undervalued
Parker-Hannifin’s most followed valuation narrative pegs fair value around $1,160.95, comfortably above the last close at $943.54. That gap rests on a view that cash generation, margins and capital returns can support a richer price tag than the market is assigning today.
The company's enhanced exposure to aftermarket and longer-cycle revenue streams (anticipated to be 85% of the portfolio by 2029) creates higher quality, more recurring income and reduced cyclicality, which should underpin long-term earnings growth and provide earnings stability during future cycles.
See why 44 investors see Parker-Hannifin as 19% undervalued.
Result: Fair Value of $1,160.95 (UNDERVALUED)
Still, the narrative around Parker-Hannifin can crack if aerospace demand cools or if acquisitions like Curtis Instruments drag on margins longer than expected.
Find out about the key risks to this Parker-Hannifin narrative.
Another View On Parker-Hannifin Valuation
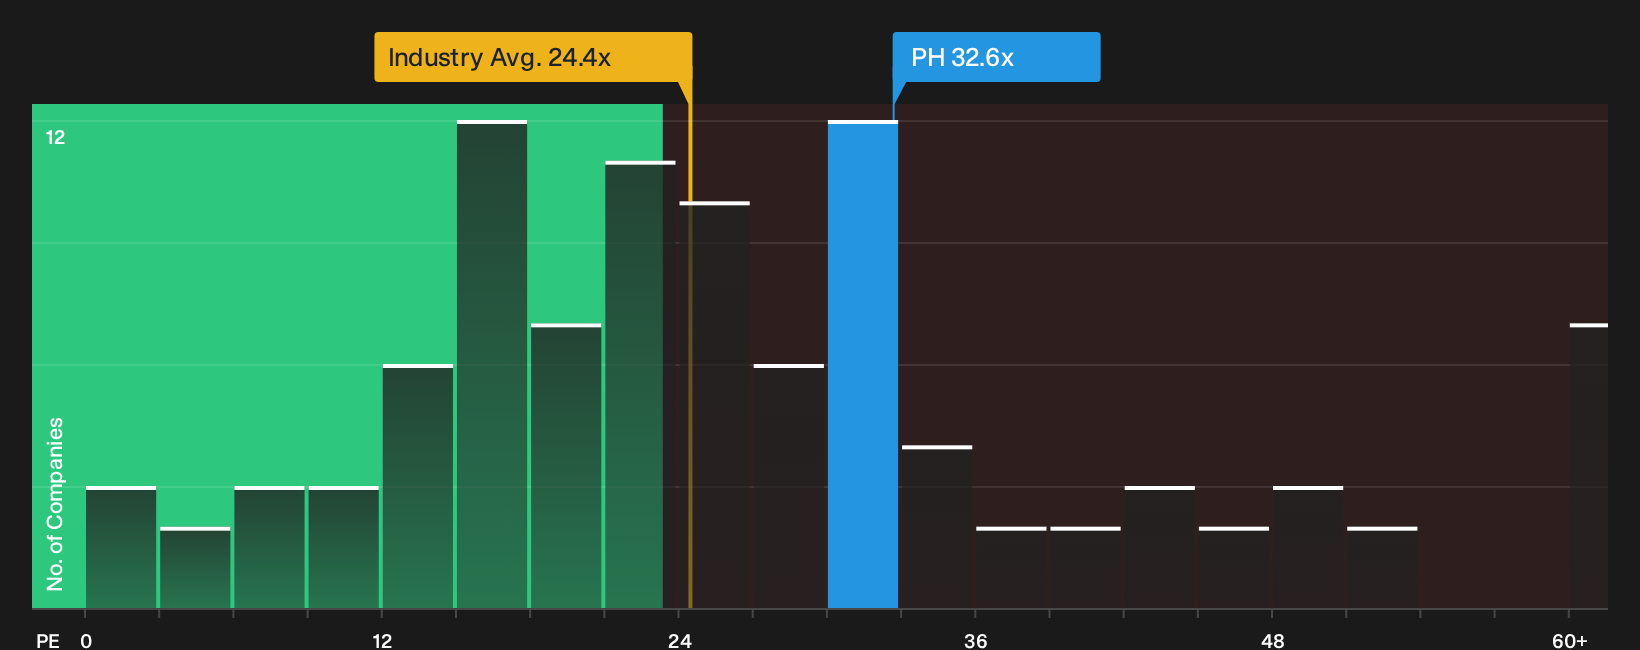
Analysts see Parker-Hannifin as undervalued against a fair value of about $1,160, yet the market is already paying a rich P/E of 32.6x. That is above the US Machinery industry on 24.4x and above a fair ratio of 30x, which points to less margin for error if expectations cool.
Investors weighing that richer P/E against industry, peers and the fair ratio may want to stress test their own scenarios before leaning on the most optimistic targets, or ask whether a lower entry multiple would offer a better balance between quality and valuation risk. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or early opportunity, either way the onus is on you to weigh the upside and downside. Act while sentiment is divided and stress test your own assumptions with the 3 key rewards and 2 important warning signs
Looking for more Parker-Hannifin style investment ideas?
If Parker-Hannifin has you thinking harder about quality, valuation and risk, do not stop here. Fresh ideas often come from widening your search.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (23 results) that filters for financially robust businesses built to handle tougher conditions.
- Hunt for potential mispricing with a 35 high quality undervalued stocks that focuses on strong fundamentals trading below what many investors might expect.
- Stack income potential on top of capital growth by reviewing a 7 dividend fortresses that highlights higher yield payouts with defensive traits.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com