
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Northern Trust (NTRS) Cheap After The J O Hambro Outsourced Trading Win?
J O Hambro Capital Management’s decision to appoint Northern Trust (NTRS) as the sole provider of outsourced trading services puts the group’s Integrated Trading Solutions business in focus for investors assessing the stock’s institutional franchise.
Recent price action shows that Northern Trust’s share price return has cooled in the very short term, with a 7 day share price return down 5.97% and a 30 day share price return down 3.27%, even as the year to date share price return sits at 27.72%. Over a longer horizon, total shareholder return has been stronger, with a 1 year total shareholder return of 38.14% and a 3 year total shareholder return close to 2x. This suggests that investors have already rewarded the business for prior execution while now weighing fresh contract wins, new mandates and digital asset products against today’s US$177.89 share price.
Scan beyond Northern Trust and identify other institutional finance players with a solid footing using our curated list of list of solid balance sheet and fundamentals (23 results).
Northern Trust looks like a capable operator in institutional services and digital assets, yet after a near 2x three year total return and fresh mandate wins, is the US$177.89 share price still giving you value?
Most Popular Narrative: 3% Undervalued
Northern Trust's most followed valuation story pegs fair value at about $183.81 versus the recent $177.89 close, so the current price sits slightly below that narrative anchor and puts the focus on how durable earnings and margin assumptions really are.
The company's recent organic growth and margin expansion are largely attributed to near-term operational efficiencies and balance sheet optimization (notably lower expense growth and improved operating leverage). Yet investors may be overestimating the persistence of these improvements in light of ongoing industry fee pressure from the growing shift to passive investing and ETFs, which is likely to constrain long-term revenue growth and profit margins.
Find out how 11 investors see Northern Trust as 3% undervalued.
Result: Fair Value of $183.81 (UNDERVALUED)
Still, the narrative can break if fee pressure from the shift to passive products bites harder than expected, or if rising technology spend erodes margin assumptions.
Find out about the key risks to this Northern Trust narrative.
Another View On Northern Trust’s Valuation
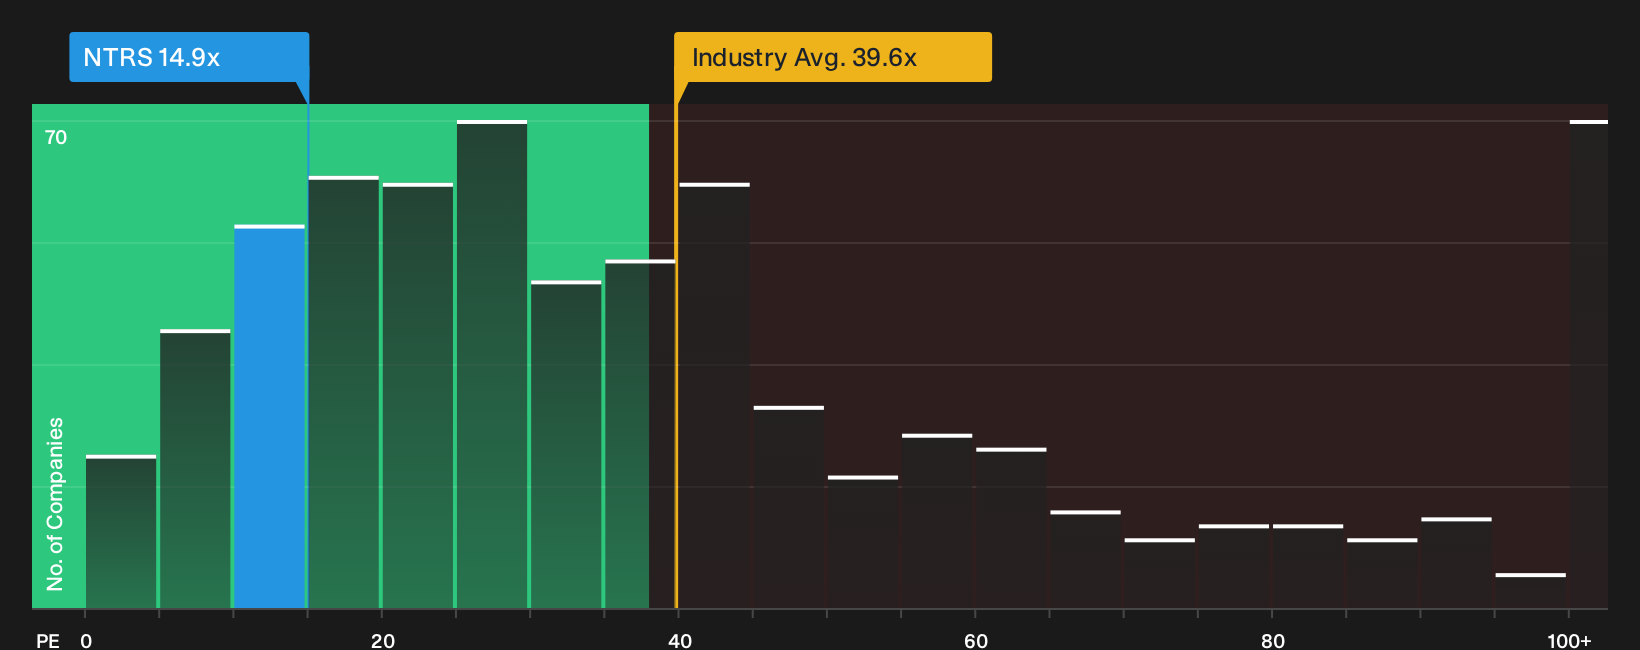
The first story frames Northern Trust as roughly 3% undervalued on a fair value of about $183.81, yet the P/E picture is less generous. The stock trades on about 14.9x earnings versus a fair ratio of roughly 14x, even though the peer group sits near 21.7x and the wider US Capital Markets space around 39.6x. That mix points to a company priced below rivals but slightly above its own fair ratio, so how much valuation risk are you really comfortable owning if sentiment turns?
See what the numbers say about this price in more detail in our valuation breakdown, then decide which set of assumptions you trust more, the market’s current P/E or the narrative fair value anchor. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Northern Trust feels familiar, consider promptly reviewing the underlying data and stress testing the upbeat signals that other investors are focusing on using our breakdown of 4 key rewards
Looking for more Northern Trust style investment ideas?
Round out your view beyond Northern Trust and put fresh ideas on your radar with a few focused stock lists built directly from the Simply Wall St screener.
- Target resilient compounding potential by reviewing companies that screen as 35 high quality undervalued stocks.
- Prioritise income today by scanning for reliable payers across our 7 dividend fortresses.
- Dial down portfolio fragility by zeroing in on businesses flagged as 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com