
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ASML (NasdaqGS:ASML) Stock May Trade At A Premium Despite High NA EUV News
ASML Holding has delivered a powerful share price run in recent years, and that kind of move naturally puts the focus on whether the current valuation is still grounded in the earnings that support it. With the stock now closely tied to big themes in advanced chips and AI hardware, the question for you is whether today's price fairly reflects what the business is actually earning.
- Over the past 3 years the stock has returned 192.3%, which puts a lot of weight on the argument that its earnings can support a much higher valuation than in the past.
- Recent collaboration with TSMC on High NA EUV and 12 inch photomask technology may support expectations for ASML's future earning power as chipmakers plan for more complex and capital intensive production nodes.
- Your read on ASML Holding is one view; the desks covering it have another. See what analysts think ASML Holding's shares could be worth.
The issue now is whether ASML's current share price is justified by the earnings that investors are effectively paying for at this level.
If you want to stress test whether ASML Holding's earnings-based valuation question shows up elsewhere in AI infrastructure, compare it with the companies in 88 AI infrastructure stocks
Does ASML Holding Look Pricey on Earnings?
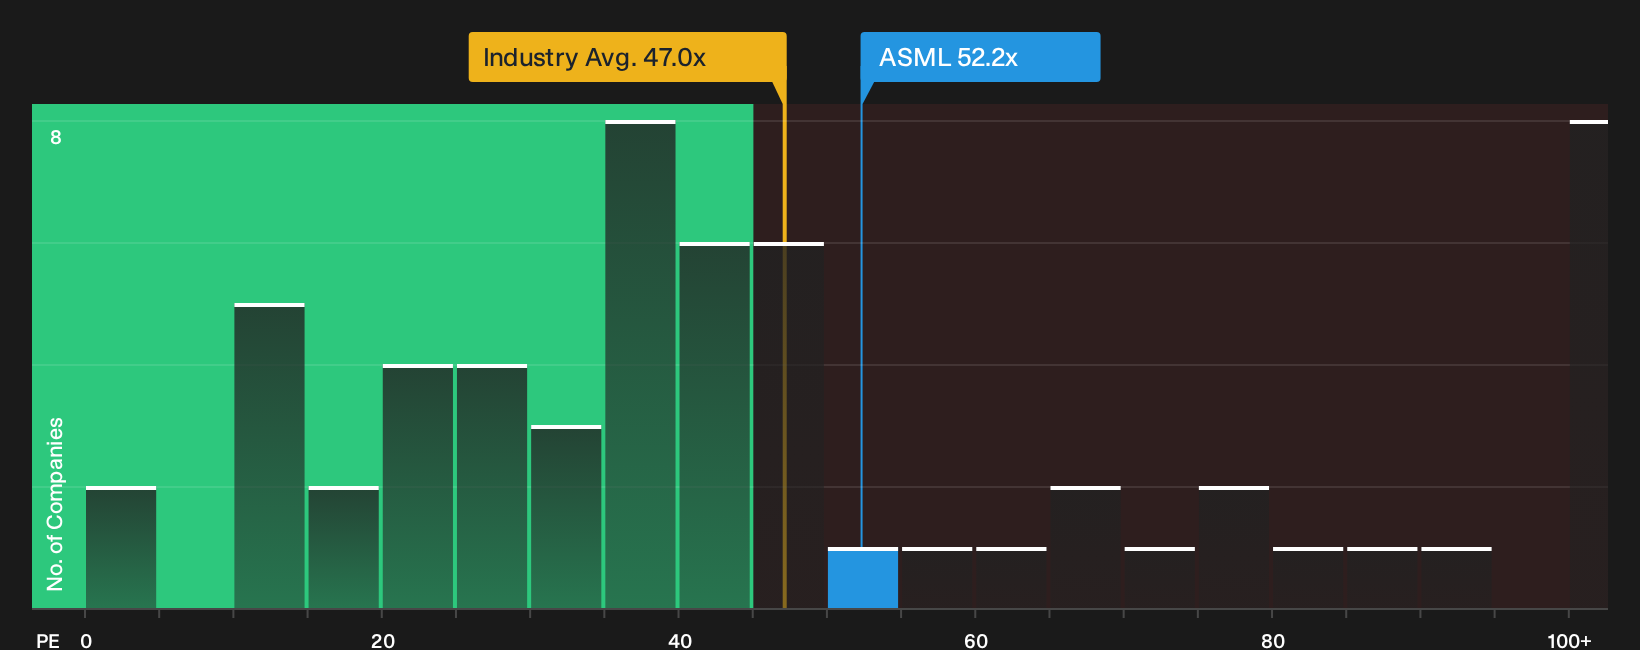
The P/E multiple is a useful way to think about ASML Holding because earnings are a central anchor for how investors frame the stock. ASML trades on a P/E of 52.2x, which is higher than the semiconductor industry average of 47.0x and above the peer group at 46.5x. Those gaps suggest buyers are currently willing to pay more per unit of earnings for ASML than for many other large chip equipment producers.
On this framework, the fair multiple that would be expected for ASML, given its sector, quality profile and risk mix, sits below the current 52.2x level, so the stock screens as overvalued on earnings. The recent collaboration with TSMC on High NA EUV and 12 inch photomask technology helps explain why sentiment is strong, yet the present P/E still assumes a richer earnings valuation than these benchmarks imply. That leaves you weighing how comfortable you are paying this kind of premium for ASML today. Explore the numbers behind ASML Holding's P/E valuation.
The ASML Holding Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for ASML Holding pick up where the P/E puzzle leaves off and map out what would need to happen to ASML Holding's growth, margins and earnings for the stock to be worth meaningfully more or less than the current price, based on the ideas shared on Simply Wall St's Community page. Rather than relying on a single multiple or model output, each narrative sets out the assumptions behind its view of fair value so you can track those against the actual results as they come through.
A fresh, number driven Narrative on ASML Holding gives you a clear way to spell out the earnings, multiples and business assumptions that would need to line up with the current P/E. It also lets you track over time whether developments such as the planned High NA EUV and 12 inch photomask rollout with TSMC are actually supporting the valuation that investors are paying for today.
Share your own Narrative for ASML Holding and set out the assumptions behind your valuation.
ASML Holding's valuation still hinges on one unanswered question
The share price conversation only goes so far when the real steering wheel sits with the executives, their track records and the way their incentives are structured around your capital. See who runs ASML Holding and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com