
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AI Regulation Debate Alters The Investment Case For Huron Consulting Group Stock
- Recent debate about AI regulation and potential model kill switches has pushed AI governance and safety into mainstream conversation, shining a light on advisors such as Huron Consulting Group that help heavily regulated clients manage related risks.
- The current focus on AI controls highlights Huron Consulting Group's role inside clients' risk, compliance and technology decision making, where AI policies intersect with real operational constraints in healthcare, education and other regulated fields.
- This article examines how Huron Consulting Group's investment narrative is influenced by rising AI governance scrutiny and demand for practical compliance expertise.
Scan beyond Huron Consulting Group and track how other regulated-industry specialists are gearing up for tighter AI rules by reviewing our curated list of 30 resilient stocks with low risk scores.
Huron Consulting Group Investment Narrative Recap
To own Huron Consulting Group, you need to believe that regulation heavy sectors keep turning to outside specialists for help with financial pressure, compliance and complex tech like AI. In the near term, the key swing factor is consulting demand across healthcare and education, where digital projects and performance improvement work drive higher value engagements.
Recent kill switch and AI control debates appear more like a potential tailwind than a disruption to that setup. The bigger risk still comes from funding pressure and policy change that squeeze client budgets, especially in healthcare. Extended pauses in tech projects or tighter spending would matter more than the current AI safety headlines.
There have been no fresh company announcements directly tied to the latest AI regulation debate, so the focus stays on how Huron Consulting Group executes its existing playbook. That means converting its pipeline in healthcare, education and commercial work into billable projects, and keeping utilization healthy while managing wage and contractor costs.
For your thesis, the key link is between Huron Consulting Group's AI, data and compliance capabilities and the drivers behind higher earnings growth that analysts have forecast. Execution on digital transformation projects and risk advisory work remains central to those potential catalysts. Any update that clarifies demand for AI governance services or progress integrating past acquisitions would be worth watching closely.
Huron Consulting Group's narrative points to revenues of $2.2b and earnings of $211.8 million by 2029, based on analysts' assumption of 8.5% yearly revenue growth and an earnings increase of about 2x from $103.8 million today.
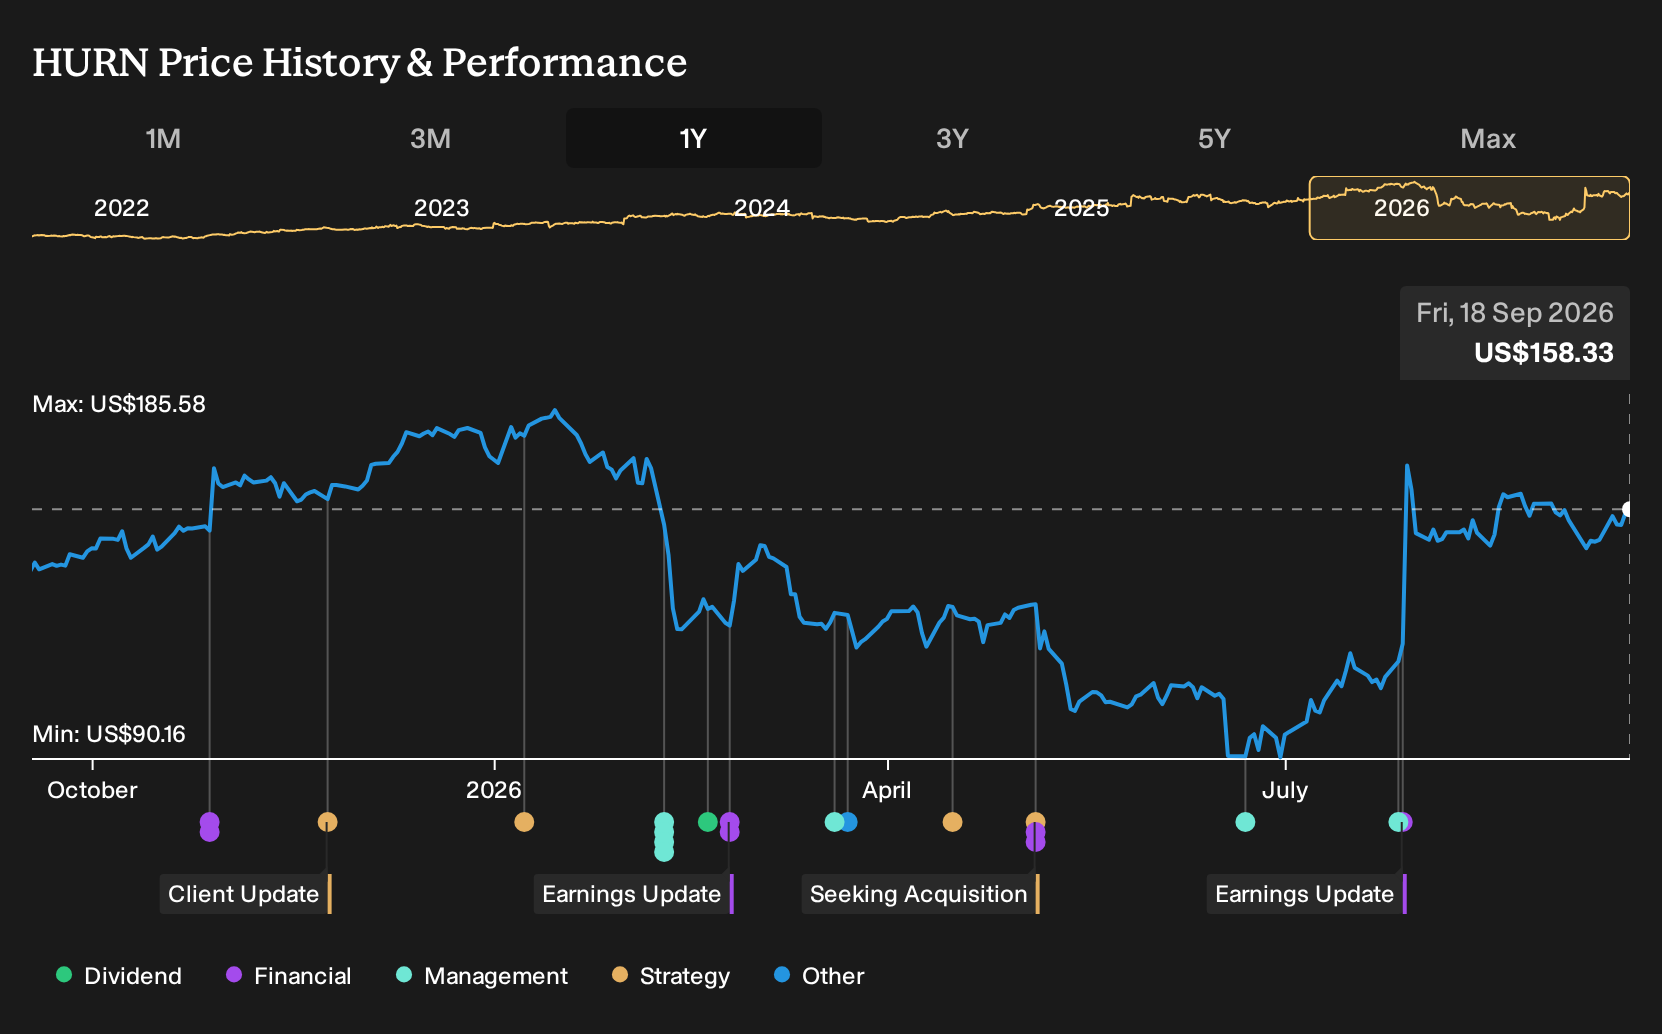
Uncover why Huron Consulting Group's fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
AI kill switch debates might sound like a clear win for Huron Consulting Group, yet the most cautious analysts lean the other way. They were only pencilling in about $2.2b of revenue and $202.8 million of earnings by 2029, with a lower 12.5x P/E, before this news event. Their view could shift, and yours might too, once you compare several narratives side by side.
Explore 3 other Huron Consulting Group fair value estimates, including one that suggests there could be as much as 40% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Huron Consulting Group research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Huron Consulting Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Huron Consulting Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Huron Consulting Group?
Once you have a view on Huron Consulting Group, it can help to cross check that thesis against other opportunities using the Simply Wall St Screener.
- For investors who want mispriced quality, scan a curated set of 35 high quality undervalued stocks that pair constructive fundamentals with more modest expectations.
- If resilience matters most to you, filter for companies on our 30 resilient stocks with low risk scores and compare their risk profiles with what you see in Huron Consulting Group.
- For those hunting for steady balance sheets and cleaner fundamentals, work through the list of solid balance sheet and fundamentals (23 results) and see which businesses merit a deeper look next.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com