
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Organon (OGN) Looks 22% Overvalued Following The MIUDELLA FDA Filing
How the MIUDELLA update ties into Organon’s women’s health focus
Organon (OGN) is back in focus after the FDA accepted a filing to extend the approved duration of use for MIUDELLA, a copper intrauterine system that Organon licensed globally in 2026.
The sNDA seeks to stretch labeled use to 6 years from 3 years, with a PDUFA decision expected in the second quarter of 2027. That timing matters for investors who are monitoring the potential evolution of Organon’s women’s health line.
Organon’s share price has climbed 88.95% year to date to US$13.68, while the 1-year total shareholder return of 31.98% contrasts with a 3-year total shareholder return that declined 15.86% and a 5-year total shareholder return that fell 50.51%. This indicates that momentum has picked up recently even though longer-term holders are still under water.
Spot fresh momentum stories beyond Organon by scanning our hand picked 35 high quality undervalued stocks, which pair recent traction with stronger balance sheets and cash flows.After an 88.95% year-to-date jump, Organon now forces a harder choice. Is it better to step in after this surge, or wait and hope the valuation resets lower before MIUDELLA’s impact is clearer?
Most Popular Narrative: 22% Overvalued
Organon’s most followed valuation story pegs fair value at $11.25, which sits below the recent $13.68 close and frames the current rally as stretched against those assumptions.
The analysts have a consensus price target of $11.25 for Organon based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $14.0, and the most bearish reporting a price target of just $8.0.
See why 34 investors see Organon as 22% overvalued.
Result: Fair Value of $11.25 (OVERVALUED)
Still, Organon’s dependence on mature, off patent products and ongoing pricing pressure in key franchises could quickly challenge any thesis built on margin expansion.
Find out about the key risks to this Organon narrative.
Another take on Organon’s valuation
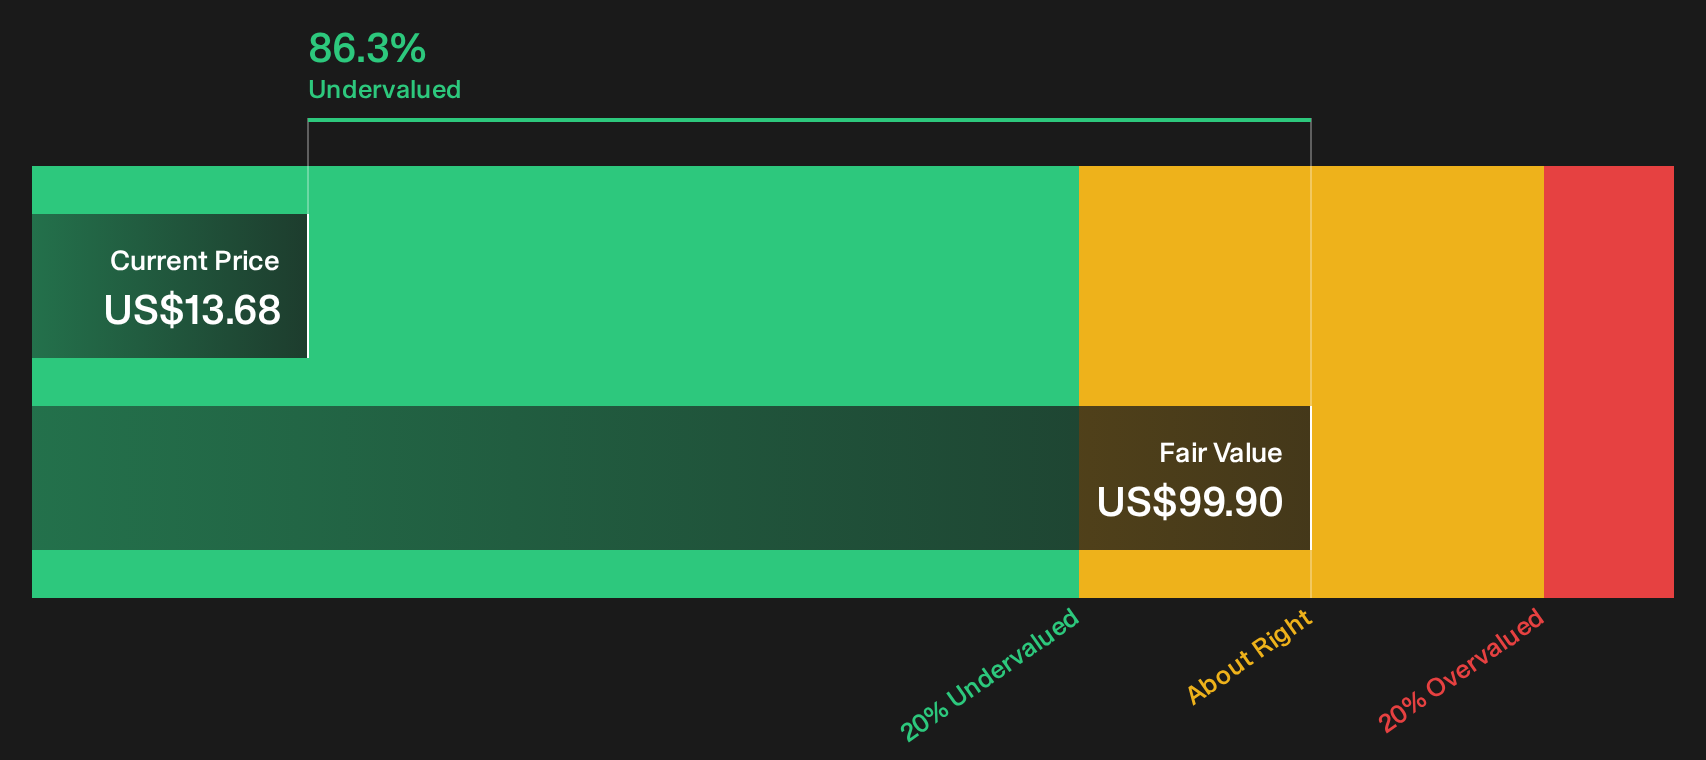
Analysts see Organon as 22% overvalued at $13.68 versus an $11.25 target, yet the SWS DCF model points the other way and flags the shares as trading well below an estimated future cash flow value of $99.90. When price and cash flows disagree this sharply, which signal do you trust?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Organon’s value and MIUDELLA’s potential can feel messy, so act while the data is front of mind. Test the story against your own risk tolerance using our breakdown of 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Organon?
If Organon has sharpened your focus, use that momentum to broaden your watchlist and pressure test your next moves with data driven stock shortlists.
- Target potential mispricings by scanning a focused set of quality companies trading below their estimated worth using the 35 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies that feature resilient payouts through the 7 dividend fortresses.
- Protect your downside by filtering for financially robust businesses with the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com