
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Has Stellantis (BIT:STLAM) Fallen Far Enough To Look Undervalued?
Stellantis shares have fallen sharply in recent years, and with the stock now trading near €4.20 the key question is whether that price still lines up with what its current sales can support.
- Over the past 3 years the share price has fallen 73.2%, which puts fresh focus on whether the market is now giving too much or too little weight to Stellantis' revenue base.
- The planned sale of the idle Brampton plant alongside more than €1b of investment in the Hordain van facility can reshape where and how Stellantis generates sales and spends capital, which may alter how investors think about the value of its top line.
- The analysts covering Stellantis have run their own numbers. See what analysts think Stellantis's shares could be worth.
For investors, the debate is whether Stellantis' current market value is justified by the scale and quality of its sales today.
If you are comparing Stellantis' sales-based pricing with other opportunities, a focused stock screen of 182 high quality undervalued stocks can be a useful next step in your research.
Is Stellantis Still Cheap on Sales?
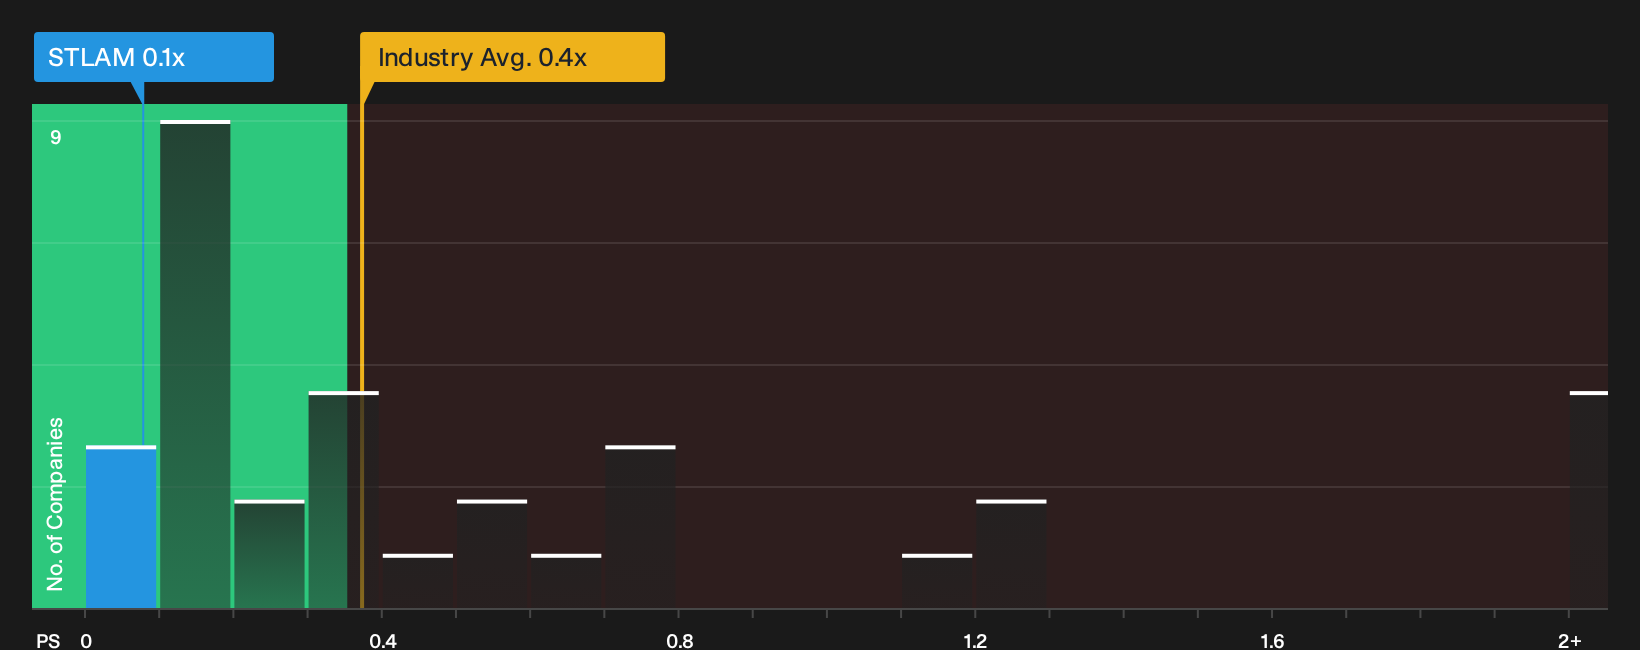
The P/S ratio suits Stellantis because investors are weighing the value of its sales base while earnings and free cash flow have been volatile. On this metric, Stellantis trades at about 0.1x P/S, which is well below the Auto industry average of 0.6x and also far under the broader peer group around 3.0x. Based on the tailored fair multiple that adjusts for the group’s size, margins and risk profile, the current P/S level screens as undervalued rather than just low in absolute terms.
Because the company is planning to sell the idle Brampton plant and invest more than €1b into the Hordain van facility, the market is effectively pricing the existing revenue stream at a steep discount even as the production footprint is being reshaped. That gap suggests the share price is not giving much credit to Stellantis’ current sales line relative to sector norms. Explore the numbers behind Stellantis's P/S valuation.
The Stellantis Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Stellantis pick up where the price to sales puzzle leaves off. They set out, in plain terms, the mix of future growth, margins and earnings that would need to hold for Stellantis' share price to look meaningfully higher or lower than today. Where a single valuation ratio gives you one number, these Narratives describe the future that number assumes, so you can watch how reality lines up with it over time on the Community page.
Bulls and bears on Stellantis are reading the same playbook very differently, with one side seeing upside headroom and the other still worried about pressure on the business.
Bull case: 27% undervalued
"Continued investment in software innovation, as well as direct-to-consumer sales and refreshed product launches for key brands lays the groundwork for future recurring revenue streams..."
Discover why this Narrative puts Stellantis at 27% undervalued.
Bear case: 5% overvalued
"Stellantis' heavy reliance on internal combustion engine vehicles particularly in North and Latin America puts it at a structural disadvantage as emissions regulations and consumer preferences shift rapidly toward electric vehicles worldwide..."
Explore why this Narrative puts Stellantis at 5% overvalued.
One more Stellantis angle that can quietly move the dial
Before you stop at the numbers, it is worth asking who is steering Stellantis, how their incentives are wired, and whether those rewards line up with your own expectations as a shareholder. See who runs Stellantis and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com