
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Dividend And Debt Refinance Could Matter For Royal Caribbean Stock (RCL)
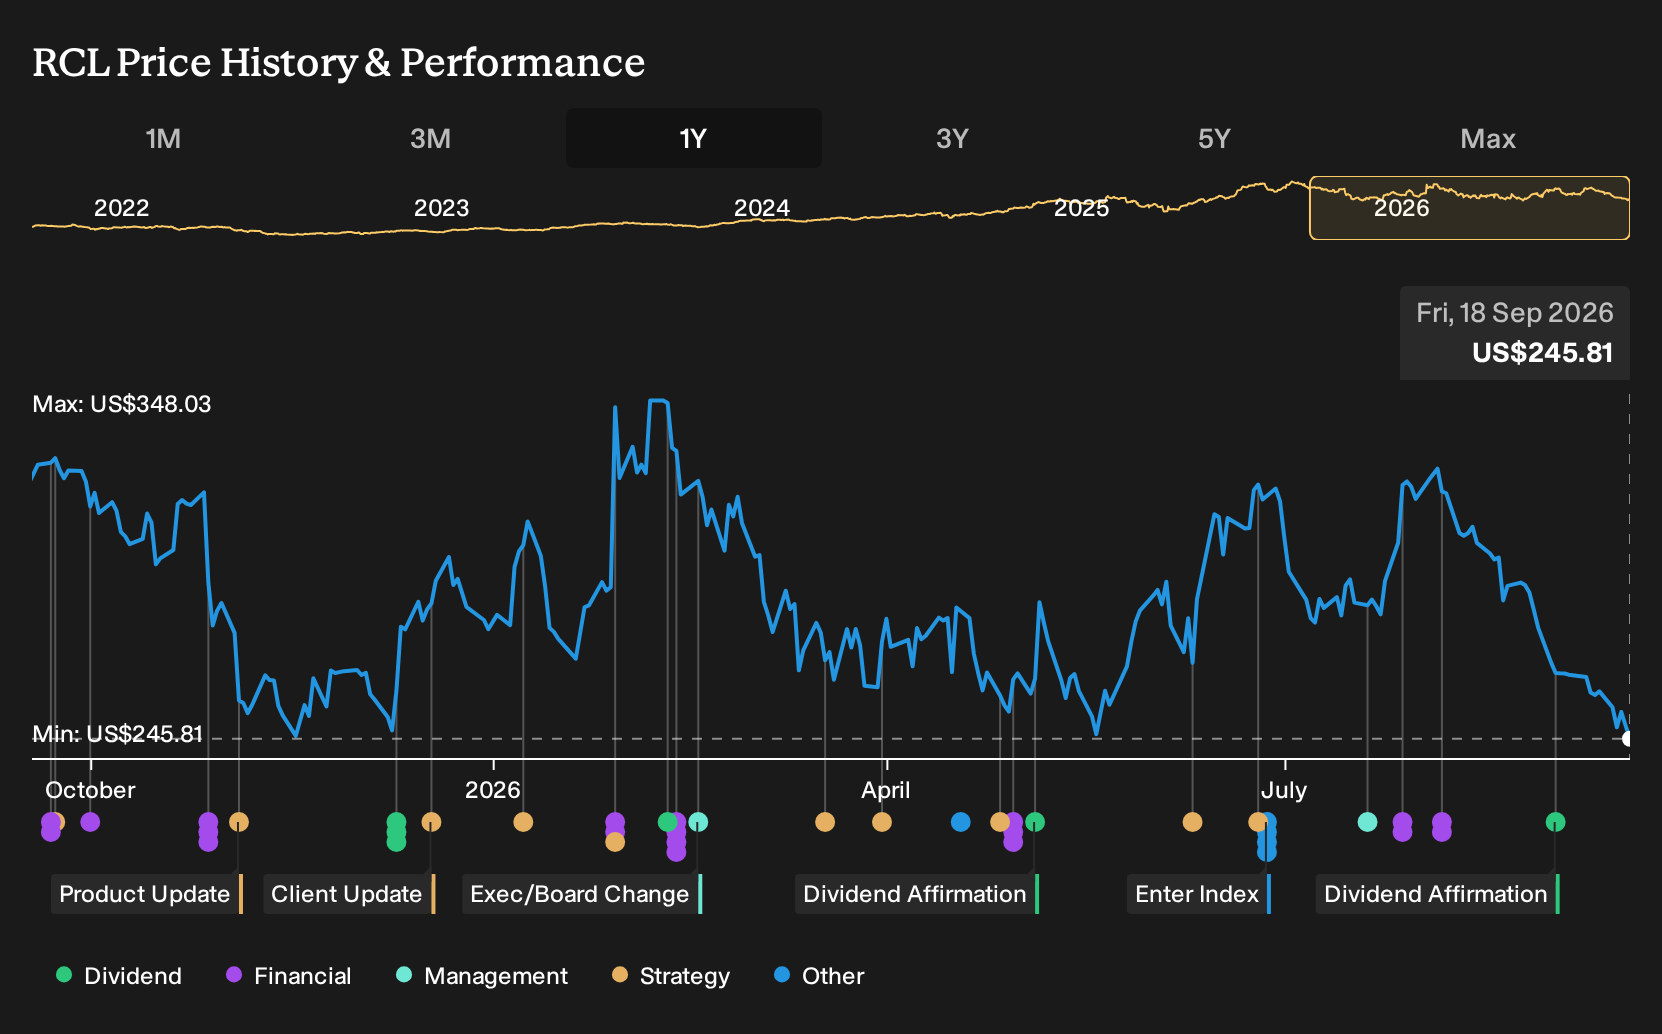
- Royal Caribbean Cruises recently confirmed a total dividend of US$1.50 per share with an ex-dividend date in mid September 2026, maintaining its established quarterly payout pattern supported by a dividend payout ratio of about 31% alongside ongoing share buybacks.
- The group also completed a US$1.25b note sale carrying a 5.55% coupon due in 2034 to refinance floating rate loans, aligning its capital returns, debt structure, and recent earnings beat with management’s focus on balancing shareholder payouts and future ship and destination investment.
- We will now look at how Royal Caribbean Cruises' investment narrative is shaped by steady dividends alongside this recent long term refinancing.
Scan beyond Royal Caribbean Cruises and line up other travel and leisure stocks returning cash to investors with our curated 7 dividend fortresses.
Royal Caribbean Cruises Investment Narrative Recap
To own Royal Caribbean Cruises stock, you need to be comfortable with a cruise operator that relies on full ships, steady pricing, and higher onboard spend to keep earnings moving. The big near term swing factor is whether demand holds up for those newer vessels and private destinations, particularly as some regions face geopolitical friction and close in bookings could soften.
The main risk right now is that consumer discretionary spending weakens, which could pressure ticket pricing and onboard revenue while fuel and currency costs stay unpredictable. The latest updates on guidance and recent performance do not fundamentally change that backdrop. They mostly fine tune how prepared the group is if conditions tighten.
The recent US$1.25b note sale with a 5.55% coupon due in 2034 is the announcement that matters most for this story. Royal Caribbean Cruises is using it to refinance floating rate loans and other obligations, which changes the mix of its liabilities rather than shrinking the overall debt load.
For you, the relevance is about execution risk and financial flexibility around catalysts such as new ships and destination projects. A more predictable interest bill can help management plan capex and marketing spend, although high leverage and large future investment needs still leave the balance sheet exposed if ticket pricing, onboard spend, or booking trends weaken.
Royal Caribbean Cruises' narrative projects US$24.3b revenue and US$6.4b earnings by 2029. That profile implies 9.1% yearly revenue growth and an earnings increase of about US$2.0b from US$4.4b today.
Uncover why Royal Caribbean Cruises' fair value indicates a 41% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Regulation is where the lowest analysts push back hardest on Royal Caribbean Cruises. They model only 7.6% yearly revenue growth and US$6.1b earnings by 2029, and expect a lower 15.2x P/E, because tighter climate rules and higher compliance costs could bite harder than the consensus assumes. These views may shift after this refinancing news.
Explore 5 other Royal Caribbean Cruises fair value estimates, including one that suggests it could be worth just $278.55.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Royal Caribbean Cruises research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Royal Caribbean Cruises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Royal Caribbean Cruises' overall financial health at a glance.
Looking For More Ideas Beyond Royal Caribbean Cruises?
If you want to pressure test your view on Royal Caribbean Cruises, it can help to line it up against other companies with different risk and return profiles. The Simply Wall St Screener lets you filter by balance sheet strength, valuation, dividends, and more so you can see where this stock fits in your wider watchlist.
- If you care most about resilient businesses with steadier profiles, start with a 30 resilient stocks with low risk scores that score well on financial risk and volatility checks.
- If value is your priority, line Royal Caribbean Cruises up against a 35 high quality undervalued stocks that combine quality fundamentals with what our models flag as pricing gaps.
- If you want growth potential that is not already crowded, broaden your research with a 16 high quality undiscovered gems that show strong fundamentals but attract less market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com