
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Varonis Systems Stock Could Change Following Data Cleanup Launch
- Varonis Systems launched its Varonis Data Lifecycle Management capability in September 2026, aiming to automatically identify and remove redundant, obsolete, and trivial data across enterprise environments while supporting compliance with GDPR, CCPA, and HIPAA.
- The new tool connects data classification, access context, and activity monitoring so organizations can delete unnecessary information with more confidence, potentially reducing storage expense, security exposure, and regulatory risk in a single workflow.
- We will now look at how Varonis Systems' investment narrative could be influenced by automated ROT data removal through Varonis DLM.
Scan beyond Varonis Systems and explore other data security plays that address storage cost, AI noise, and compliance risk with a curated set of list of solid balance sheet and fundamentals (23 results)
Varonis Systems Investment Narrative Recap
To own Varonis Systems, you need to believe that growing data security and compliance demands will eventually outweigh the near term drag from its SaaS transition and current losses. The big operational question is whether recurring SaaS momentum, cross sell and new use cases like data lifecycle management can steadily convert into cleaner earnings and cash flow.
The main short term catalyst remains execution on ARR growth while stabilizing margins that have faced pressure and a revenue mix shift. The key risk stays the same. The business is still unprofitable and not forecast to reach profitability within three years, which keeps dilution, competition and consolidation pressure very relevant.
The launch of Varonis Data Lifecycle Management directly connects to existing catalysts around data security posture management and AI driven protection. This new capability sits on the same platform that already discovers, classifies and monitors sensitive information, so it supports the idea that one vendor can handle more of an enterprise’s unstructured data problems end to end.
Operationally, DLM gives Varonis Systems another reason to talk to the same customers about storage cost, AI quality and compliance in a single conversation. That can help cross sell, stickiness and wallet share if execution is tight. It also increases expectations. If gross margin or SaaS support costs stay under pressure while competitors and hyperscalers push broader suites, the larger platform pitch around DLM faces a tougher test.
Varonis Systems' narrative projects US$1.1b revenue and US$120.7 million earnings by 2029. This projection is based on 15.2% yearly revenue growth and an earnings increase of about US$262 million from a loss of US$141.4 million today.
Uncover why Varonis Systems' fair value indicates a 7% potential upside to its current price, which could close sooner than many investors expect.
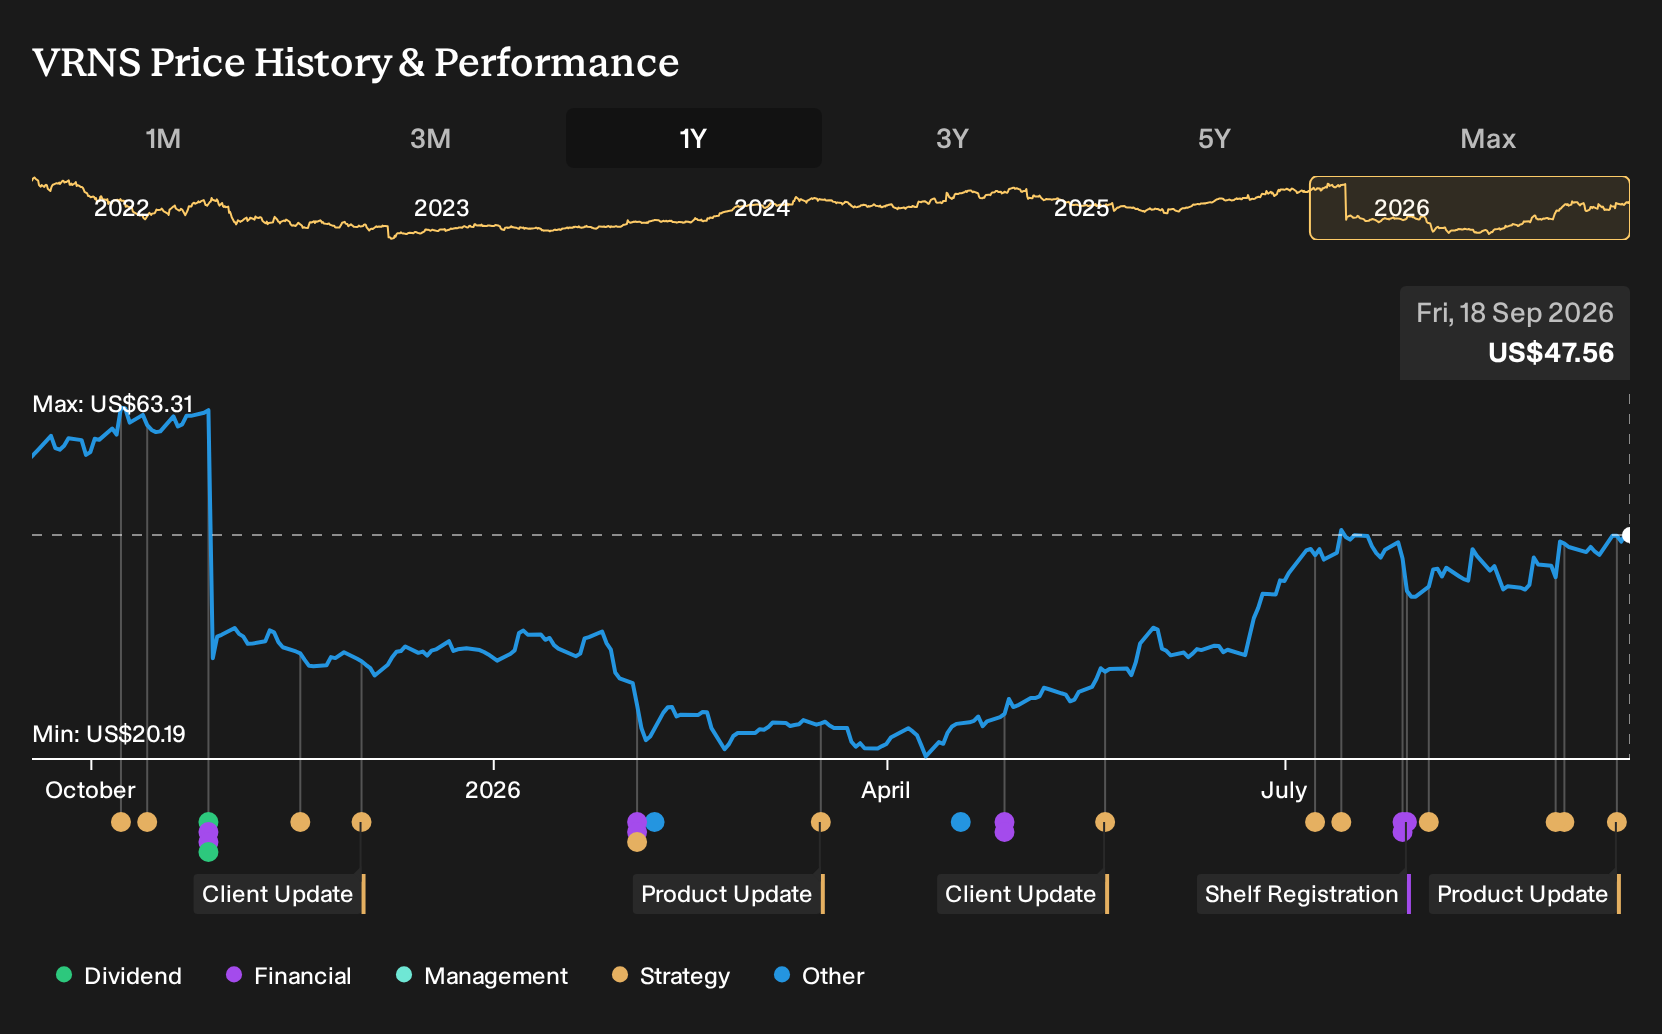
Exploring Other Perspectives
For Varonis Systems, the most optimistic analysts were already leaning hard into the SaaS transition as a catalyst. They were penciling in roughly 19.4% annual revenue growth and about US$134.0 million in potential earnings by 2029. Those forecasts came before Data Lifecycle Management, so some opinions may shift once this product is fully digested.
Explore 3 other Varonis Systems fair value estimates, including one that suggests up to 50% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Varonis Systems research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Varonis Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Varonis Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond Varonis Systems?
Once you have formed a view on Varonis Systems, it can help to widen the lens and compare it with other stocks that offer different combinations of quality, risk and income potential. The Simply Wall St Screener lets you do that in a structured way so you can test ideas rather than just collect tickers.
- If capital preservation is high on your list, consider starting with companies that score well on resilience and risk, using the 30 resilient stocks with low risk scores as a filter for your shortlist.
- If you are hunting for opportunities that the market may be overlooking, you could scan for strong fundamentals paired with limited attention through the 16 high quality undiscovered gems to surface fresh ideas.
- If balance sheet strength matters most to you, anchor your research with a curated list of solid balance sheet and fundamentals (23 results) so you focus on businesses with financial foundations that look more robust.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com