
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Product Showcases Just Shift TriMas (TRS) Investment Narrative?
- TriMas Packaging recently showcased its global portfolio of fragrance pumps, premium closures, dispensing systems and fully recyclable Singolo dispensing products at LUXE PACK Monaco and Beautyworld Dubai, giving beauty and personal care brands hands-on exposure to its latest packaging solutions.
- The focus on recyclable all-plastic dispensing, customization and live performance demonstrations offers a clear window into how TriMas is positioning its packaging operations around functionality, design flexibility and sustainability driven demand.
- We will now examine how TriMas' investment narrative could be influenced by its recyclable Singolo dispensing line and broader premium-market showcase.
Scan beyond TriMas and compare other packaging and materials stocks geared to premium consumer brands using the curated 16 high quality undiscovered gems.
TriMas Investment Narrative Recap
To be comfortable owning TriMas, you need to believe its packaging operations can translate product launches into steadier earnings, while the Aerospace and industrial exposure does not add excessive volatility. The current story leans on operational standardization and better use of automation to support margins. The recent fragrance and beauty showcase helps awareness but does not change the near term earnings setup on its own.
The key short term catalyst remains execution on integration, ERP rollouts, and process harmonization across acquired packaging assets, which analysts already link to margin potential. The biggest risk is that bottlenecks or tariff swings dilute those efficiency gains and compress gross margin just as TriMas leans more heavily on higher value packaging volumes.
Among recent developments, the expanded spotlight on Singolo, TriMas' fully recyclable all plastic dispensing line, is the clearest operational tie to future catalysts. It directly targets the sustainability focus that analysts already flag as a driver for eco friendly dispensing and closure demand, and it sits inside the Packaging segment that contributes the bulk of group revenue.
If Singolo and similar platforms see broader adoption by premium beauty and personal care customers after events like LUXE PACK Monaco and Beautyworld Dubai, Packaging mix could skew further toward higher specification, sustainability linked products. That would align with the thesis that TriMas can lean on new product uptake and process efficiency to support margin improvement, while still facing the ongoing risk that regulatory pressure on plastics shifts customer specifications faster than TriMas adapts its portfolio.
TriMas' current analyst script points to revenues of $747.8 million and earnings of $77.9 million by 2029, based on 4.2% yearly revenue growth and an earnings increase of about $59.3 million from current earnings of $18.6 million.
Uncover how TriMas' fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
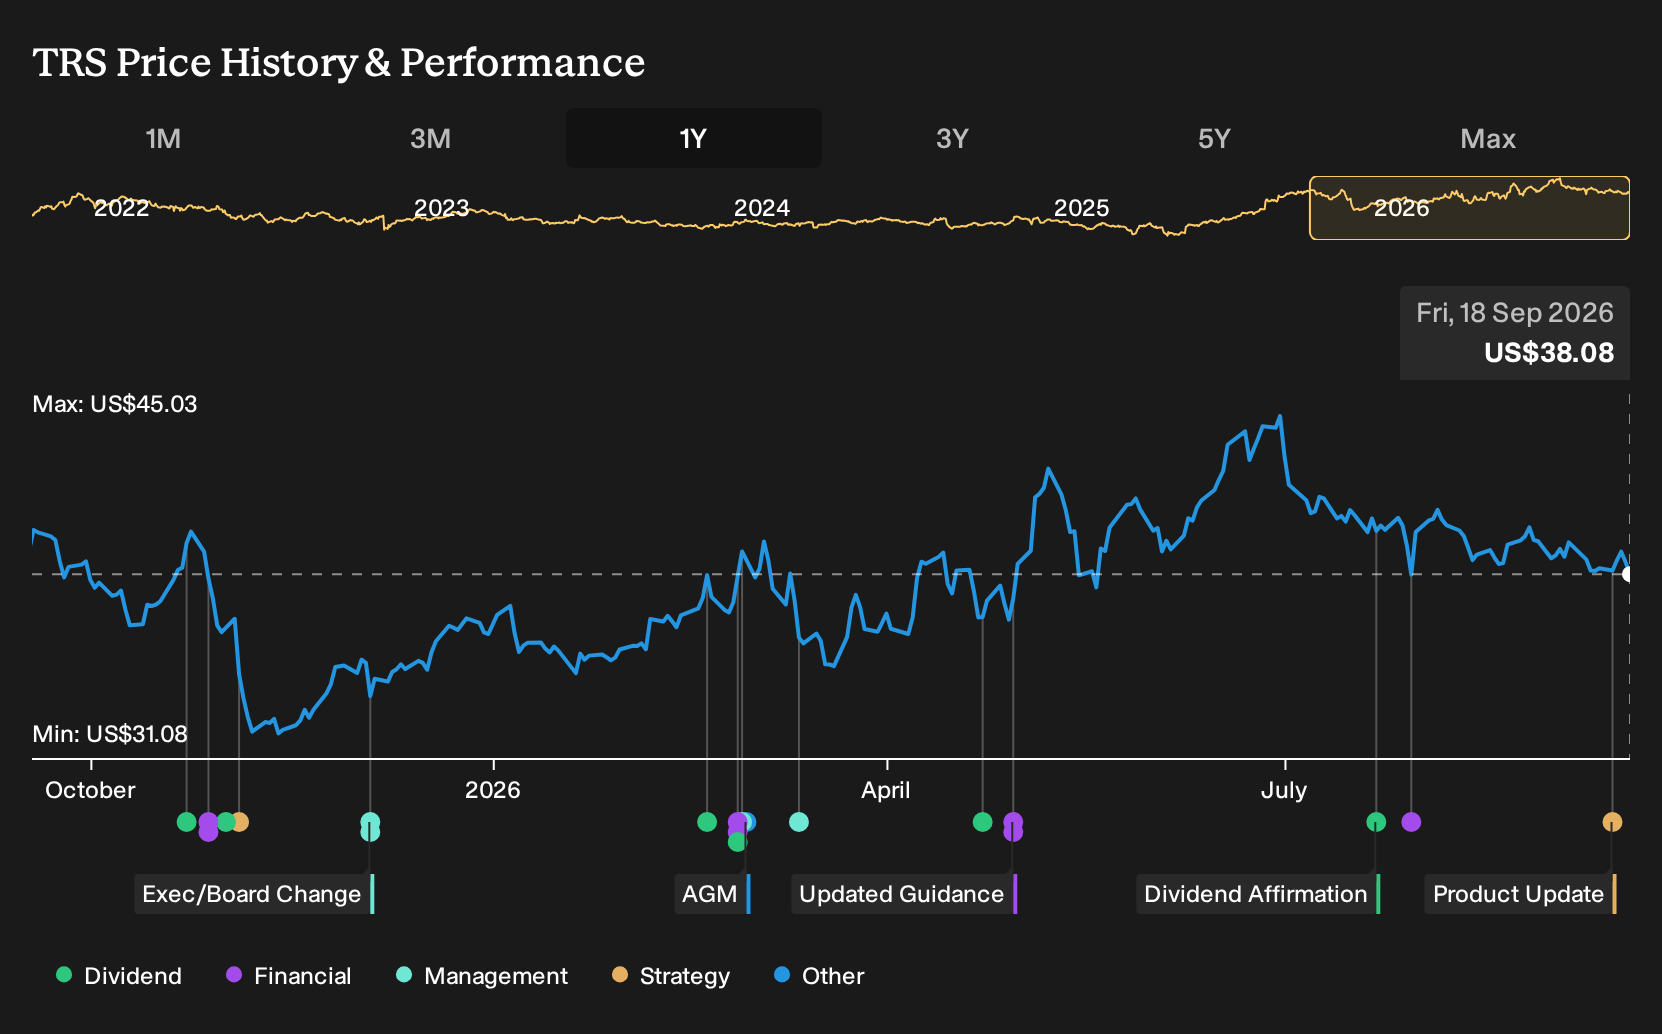
Community fair values for TriMas from the Simply Wall St Community span from about US$4.52 to US$45 across 2 separate views, a huge gap that shows how far apart private investors can be on the same stock. Set that against execution risks around integration, tariffs and plastics regulation, and you get a wide field of potential outcomes that deserves closer inspection before you decide where you stand.
Explore another TriMas fair value estimate, including one that suggests as much as 18% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your TriMas research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for TriMas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TriMas' overall financial health at a glance.
Looking For More Investment Ideas Beyond TriMas?
If the TriMas story has sharpened your thinking on quality, risk and income, it can be useful to line it up against other opportunities with similar traits. The Simply Wall St screener lets you quickly filter for different combinations of balance sheet strength, valuation and income so you can build a watchlist that actually fits your style.
- For investors who want value with quality, review a curated group of companies trading below their estimated worth via the 35 high quality undervalued stocks.
- If capital preservation ranks high for you, check out a hand picked 30 resilient stocks with low risk scores that score well on resilience and stability.
- Income focused investors can scan for payout potential by reviewing a focused 7 dividend fortresses that meet a 5%+ yield hurdle.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com