
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Uranium Royalty (UROY) Is Back In The Spotlight
Uranium Royalty (UROY) drew fresh attention after reporting first quarter results to July 31, 2026, with sales of US$50.98 million and net income of US$16.25 million, both above the prior year.
The recent first quarter update has arrived while Uranium Royalty’s share price has been in a strong upswing, with a 90 day share price return of 54.58% and a 1 year total shareholder return of 22.91%. This suggests that momentum has been building rather than fading over both shorter and longer timeframes.
Ride this uranium momentum by screening for other potential nuclear energy infrastructure beneficiaries with the curated 19 nuclear energy infrastructure stocks.After a 54.58% 90 day surge and a market value around US$1.73b, Uranium Royalty now trades above the average analyst target. Whether this premium is a warning sign or a fair price for recent execution is what the following valuation work will test.
Price-to-Earnings of 31.3x: Is it justified for Uranium Royalty?
On earnings, Uranium Royalty is being valued at a P/E of 31.3x, against a last close of $4.56, which suggests investors are willing to pay a premium for each dollar of profit compared with the broader US Metals and Mining industry.
The P/E ratio compares the share price with earnings per share and is often used for profitable resource royalties and producers, since it ties valuation directly to the bottom line. A higher multiple can signal that the market is pricing in strong cash generation, a differentiated business model, or simply chasing recent share price strength rather than focusing on balance sheet risk.
Here, Uranium Royalty trades on a richer P/E than the sector average of 20.8x, which points to the stock being expensive relative to typical metals and mining peers. Against a peer average P/E of 33.5x, the valuation looks closer to the group, which hints that investors may be treating UROY similarly to companies with comparable business profiles, even though the SWS DCF model currently flags the shares at $4.56 as above an estimated future cash flow value of $1.25.
Result: Price-to-Earnings of 31.3x (OVERVALUED)
See what the numbers say about this price — find out in our valuation breakdown.
Still, Uranium Royalty’s premium P/E and market value near US$1.73b could face pressure if uranium sentiment cools or if physical uranium transactions slow.
Find out about the key risks to this Uranium Royalty narrative.
Another View on Uranium Royalty’s Valuation
There is a second lens you can use on Uranium Royalty. The SWS DCF model estimates future cash flows at $1.25 per share, which is well below the current $4.56 price. That flags the stock as overvalued using this method and raises a different question about what you are really paying for.
Look into how the SWS DCF model arrives at its fair value.
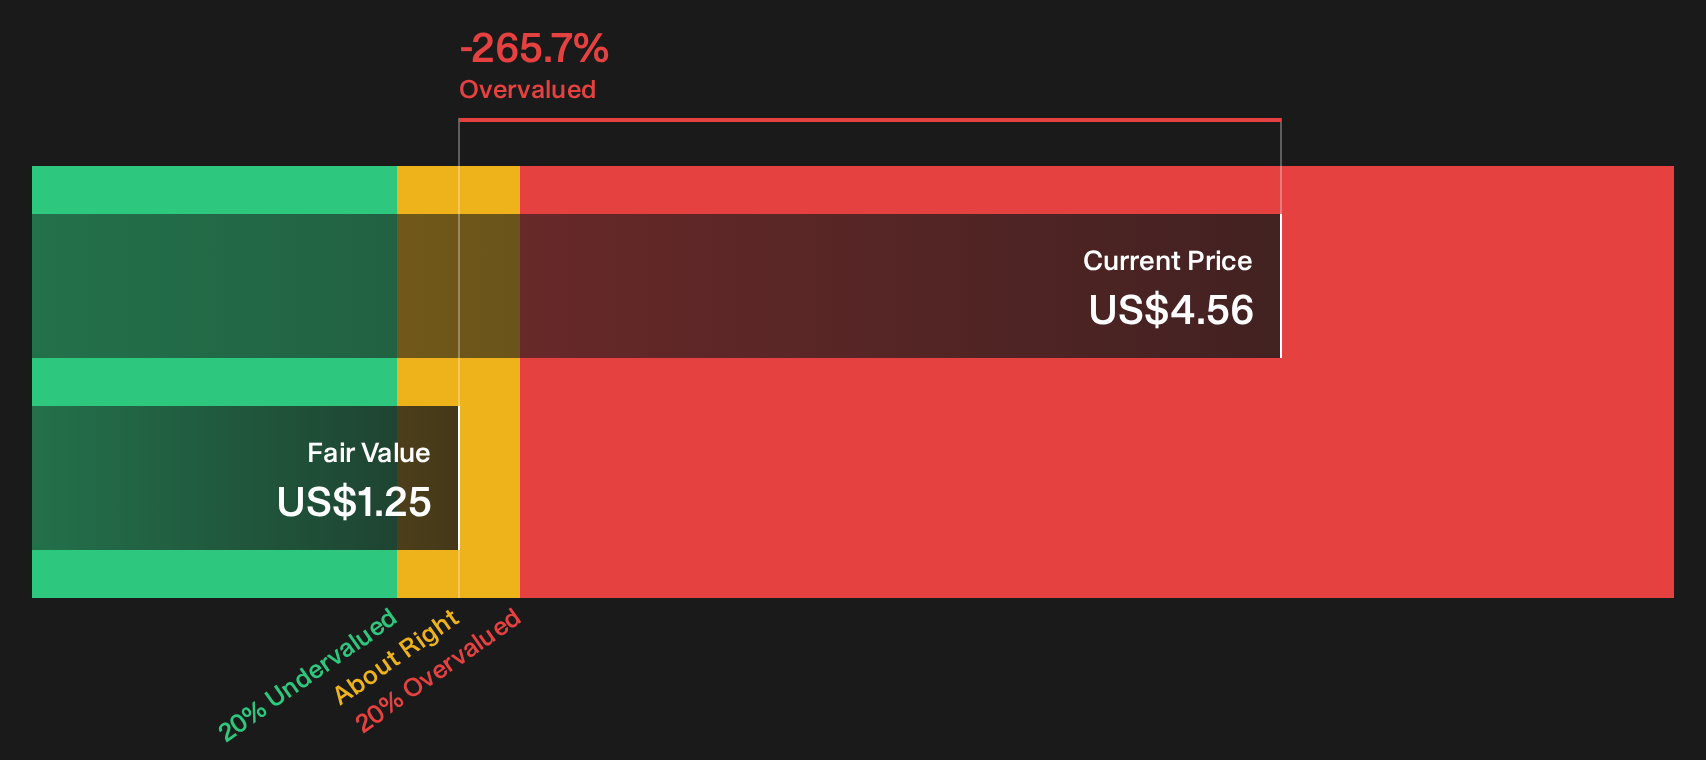
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Uranium Royalty for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Momentum, uranium exposure and a rich P/E all pull sentiment in different directions today. Act quickly, review Uranium Royalty’s numbers, and weigh both sides by checking the 1 key reward and 2 important warning signs
Looking for more Uranium Royalty style investment ideas?
If Uranium Royalty has sharpened your focus on where capital goes next, do not stop here. Broader ideas can help you spot the next opportunity early.
- Chase potential mispricing by scanning a 33 high quality undervalued stocks that filters for quality businesses still trading at compressed valuations.
- Prioritise resilience and sleep better at night with a 30 resilient stocks with low risk scores that highlights companies with sturdier risk profiles.
- Get ahead of the crowd by sifting through a 16 high quality undiscovered gems that focuses on strong fundamentals before the market fully catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com