
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Chinasoft International (SEHK:354) Fairly Valued After Its Foshan AI Project Win?
Chinasoft International (SEHK:354) has secured a RMB 35.5 million Foshan project tied to Guangdong’s Industrial Robot and Smart Home Application Enablement Centre, advancing its push into AI powered device edge cloud solutions for pan home furnishing manufacturers.
Recent trading suggests investors are reassessing Chinasoft International’s prospects, with a 1-day share price return of 5.99% and a 90-day share price gain of 20.06%. However, the year to date share price return is down 24.76% and the 1-year total shareholder return has declined 36.69%, pointing to improving short term momentum against a weak longer term track record.
Scan how Chinasoft International fits into the broader AI and automation story by comparing it with 88 AI infrastructure stocks powering device edge cloud rollouts worldwide.
Chinasoft International has bounced hard in the short term, yet still sits on deep 1 and 5 year share price declines. Is this Foshan contract the start of a rerating, or just a blip that the valuation does not fully support?
Price-to-Earnings of 22.9x: Is it justified for Chinasoft International?
Chinasoft International trades on a P/E of 22.9x, which sets a reference point for how the HK$3.89 share price lines up against its profitability compared with peers.
The P/E ratio compares what investors are paying today for each unit of current earnings. For a software and IT services group where a lot of value is tied to contracts and service pipelines, this metric often reflects how confident the market is in future profit delivery rather than just the latest year of results.
On one hand, the stock is described as good value when measured against an estimated fair P/E of 24.1x, which suggests the current multiple is slightly below a level the market could potentially move toward if expectations hold. On the other hand, the same 22.9x P/E is flagged as expensive versus the broader Asian IT industry average of 19.2x. This signals that investors are already paying a premium compared to sector peers and that premium needs to be backed by the forecast 33.7% annual earnings growth and revenue growth of 9.2% a year.
Relative to its direct peer set, Chinasoft International is also described as good value, with its 22.9x P/E sitting well under a peer average of 76.9x. That wide gap points to the market assigning much less optimism to this stock than to comparable IT companies, even though its earnings are forecast to grow faster than the Hong Kong market and its earnings quality is described as high.
Explore the SWS fair ratio for Chinasoft International.
Result: Price-to-Earnings of 22.9x (ABOUT RIGHT)
Still, the long slide in Chinasoft International’s multi year returns, along with any disappointment against its current earnings forecasts, could quickly cap this rerating story.
Find out about the key risks to this Chinasoft International narrative.
Another view on Chinasoft International’s value
The P/E story presents Chinasoft International as roughly fairly priced, yet the SWS DCF model offers a different perspective. At HK$3.89, the share price stands above an estimated future cash flow value of HK$2.11, which presents the stock as overvalued on this cash based basis. Which signal do you treat as your anchor?
Look into how the SWS DCF model arrives at its fair value.
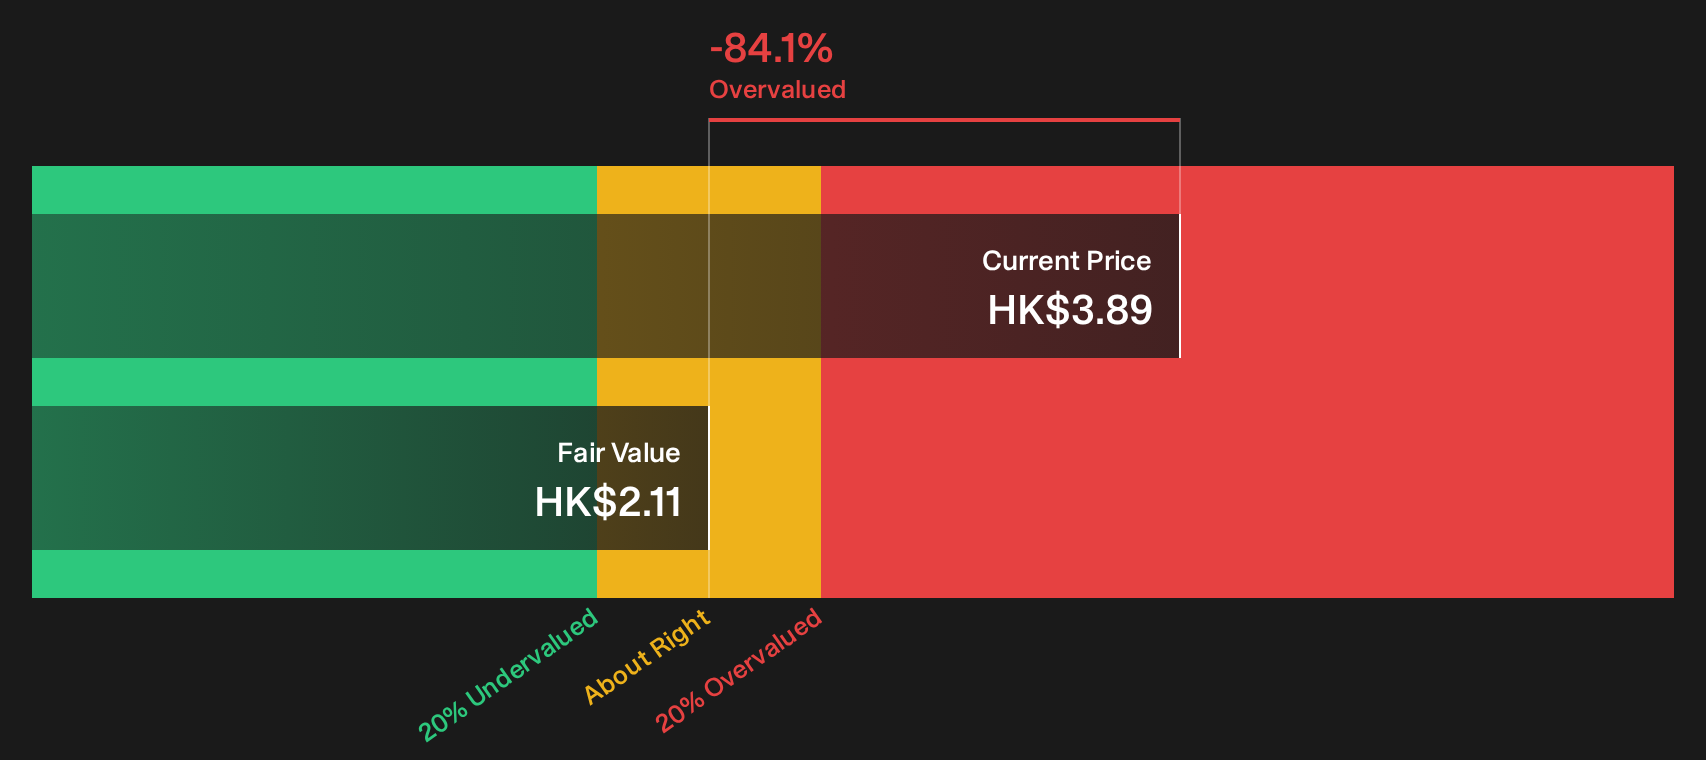
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Chinasoft International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Chinasoft International so far. If you want a clear takeaway, act quickly and review both sides of the story with 1 key reward and 1 important warning sign
Looking for more Chinasoft International sized ideas?
Do not stop with Chinasoft International. Use the same disciplined lens across a wider watchlist so you are not relying on a single opportunity.
- Target potential mispricing by scanning companies that combine quality fundamentals with attractive valuations using 179 high quality undervalued stocks.
- Strengthen your income stream by reviewing dependable yield opportunities through 156 dividend fortresses.
- Dial down portfolio stress by focusing on businesses with sturdier finances using the 226 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com