
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Ciena (CIEN) Faces A Valuation Test Following Its 2029 Revenue And R And D Push
Ciena (CIEN) shares are in focus after a recent special call where management laid out a path to approximately US$14b in revenue by fiscal 2029 and detailed significant research and development spending plans.
Recent trading has been choppy for Ciena, with the share price down about 12% over the past 30 days and around 24% over 90 days. This comes even though the year to date share price return is 41.75% and the 1 year total shareholder return is 152.08%.
Scan Ciena alongside other optical and AI infrastructure plays that could be setting up for their next leg higher with our curated 88 AI infrastructure stocks
Bulls point to Ciena’s US$14b revenue ambition and heavy R&D plans, while bears focus on the sharp pullback in the share price. Which side does today’s valuation actually support?
Most Popular Ciena Narrative: 37% Undervalued
Ciena’s most followed narrative pegs fair value at about $551.86, comfortably above the last close around $348.80. This puts the current pullback in a very different light for anyone focused on long term cash flows rather than recent volatility.
Major cloud providers and a new wave of neo-scalers are aggressively investing in high-capacity, low-latency optical networking infrastructure to support AI workloads, driving multiyear, global network buildouts that should significantly expand Ciena's addressable market and underpin sustained, above-trend revenue growth.
Ciena's industry-leading solutions (WaveLogic 6, RLS platform, pluggables, DCOM) are rapidly becoming de facto standards for AI network infrastructure. This is resulting in sizable multi-hundred-million-dollar orders, a record order book, and strong visibility into 2026 growth, suggesting consensus revenue estimates may be too conservative.
See why 46 investors see Ciena as 37% undervalued.
Result: Fair Value of $551.86 (UNDERVALUED)
Still, Ciena’s dependence on a handful of large hyperscaler customers and ongoing supply chain constraints could quickly challenge the bullish AI networking narrative.
Find out about the key risks to this Ciena narrative.
Another View on Ciena’s Valuation
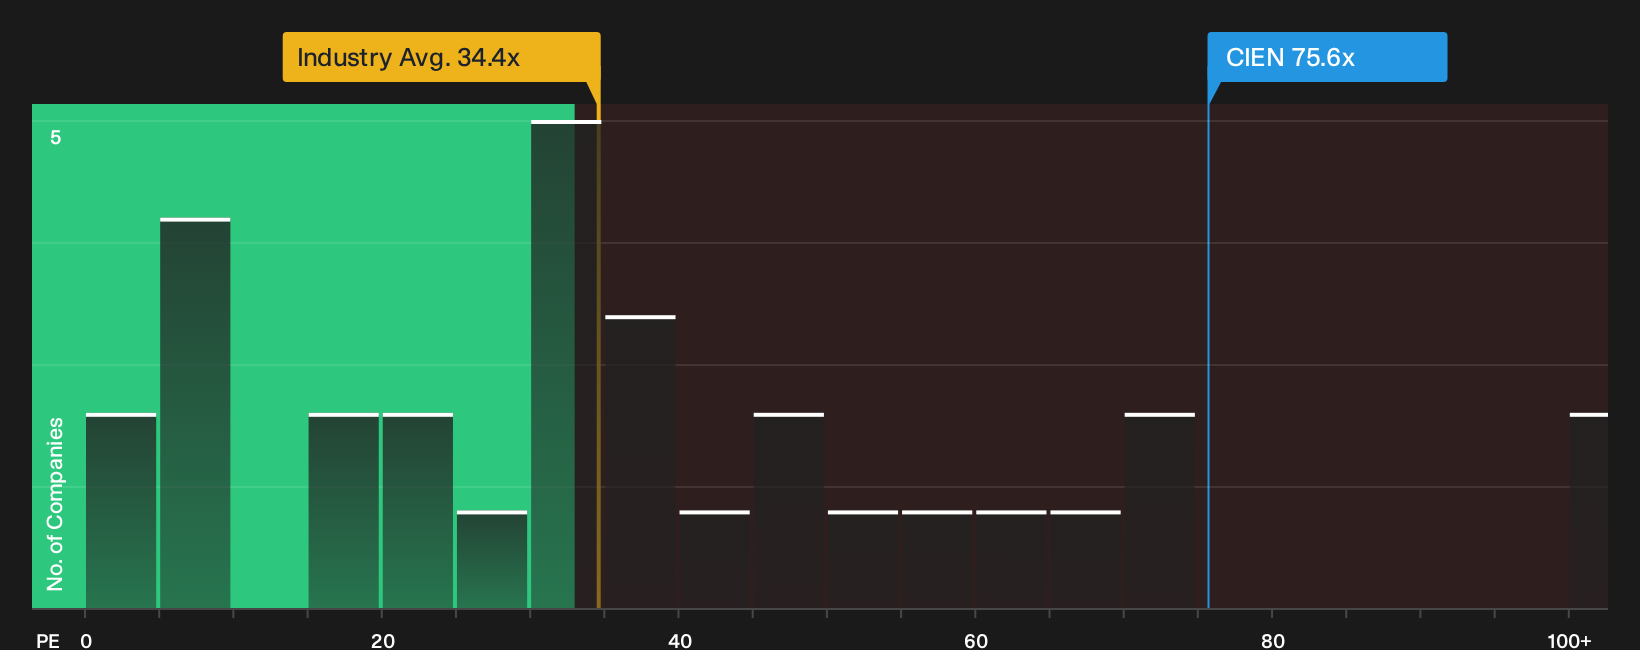
Ciena screens as cheap against an estimated fair value based on future cash flows, trading at about a 35.9% discount to an SWS DCF fair value of $544.46. Yet the same shares change hands at roughly 75.6x earnings compared with a fair ratio of 52.2x and an industry P/E of 34.4x. That gap points to meaningful valuation risk if sentiment cools, even if the growth story plays out.
To see how that earnings multiple could compress or hold up as expectations shift, take a closer look at the valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Ciena are clear, so treat this inflection point as a prompt to move fast. Review the underlying data and stress test your own thesis with the full breakdown of 3 key rewards and 2 important warning signs
Looking For More Ideas Beyond Ciena?
If Ciena has you thinking harder about valuation and resilience, do not stop with a single ticker. Broaden your watchlist now so you are not chasing late moves tomorrow.
- Target steadier compounding and focus on capital preservation by reviewing a curated set of lower volatility candidates through our 30 resilient stocks with low risk scores.
- Hunt for mispriced opportunities where quality and price still line up nicely using our focused 33 high quality undervalued stocks.
- Aim for staying power in tougher markets by zeroing in on companies with robust finances through our list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com