
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 AI Stocks With P E Under 28 To Watch
Rising bond yields and heavier government borrowing to fund AI projects mean capital is getting more expensive, even as governments talk up an AI Force and new data center spending. That combination can leave some AI related companies priced as if the boom never happened. This article highlights three stocks linked to the ChatGPT and AI build out that currently screen as undervalued and warrant closer analysis.
The three AI related stocks below are just a sample, and the full screen surfaced 47 more companies tied to the ChatGPT and wider AI build out with equally compelling narratives that are not covered here. To identify and analyze the rest of this group, head straight into the Undervalued Artificial Intelligence/ AI Stocks screener
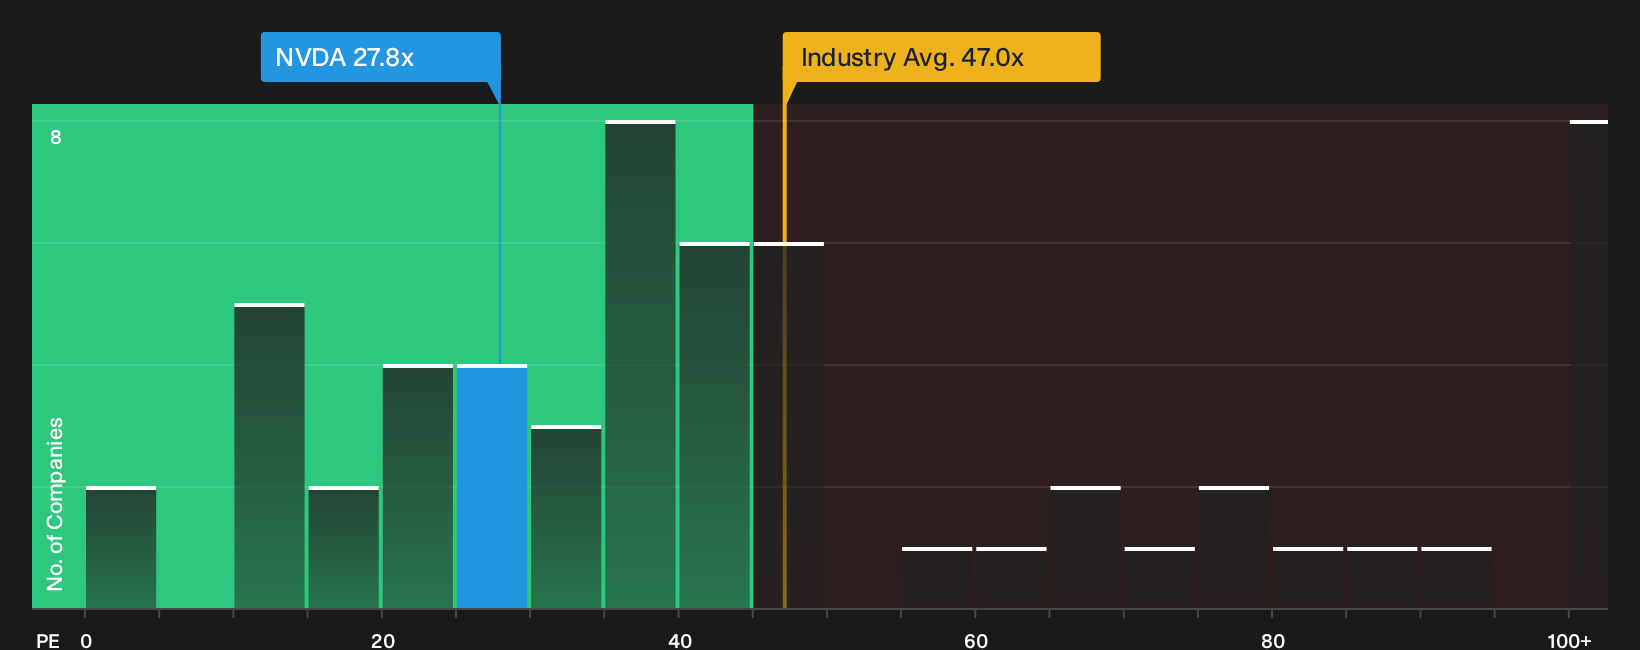
NVIDIA (NVDA)
Overview: NVIDIA is a chip and software company that supplies GPUs and AI platforms for data centers, gaming, professional graphics, and automotive customers worldwide.
Operations: NVIDIA generates about US$275.4b from Compute & Networking and US$27.6b from Graphics, with most sales coming from the United States and Taiwan.
Market Cap: US$5,362.1b
NVIDIA matters for this AI screener because its GPUs and software effectively provide the computing muscle that many ChatGPT style services run on.
"Uptake of an open-source, cheaper, or better platform than Nvidia's CUDA would heavily undermine Nvidia's moat and enable any sizeable firm to directly engage semiconductor manufacturers, such as TSMC, to produce their own chips, stealing away Nvidia's high margin products."
For anyone looking at NVIDIA through the AI lens, the real swing factor is what happens if that one core assumption changes.
If that assumption feels shaky, read the full narrative for NVIDIA to see how NVIDIA’s moat, pricing power, and AI upside could still be decoupling from today’s risks.
Adobe (ADBE)
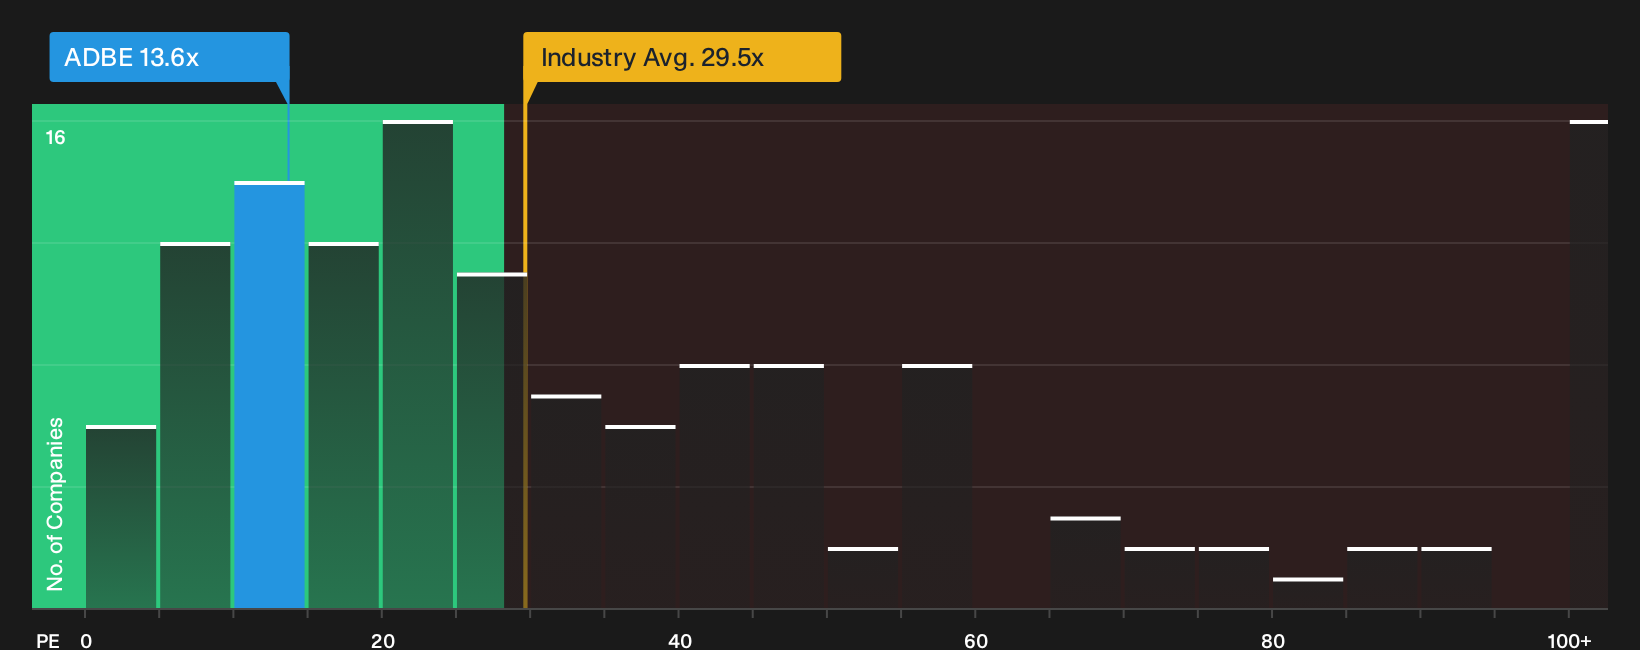
Overview: Adobe is a software company that provides AI-infused creative, document, and customer experience tools through its Creative Cloud and Experience Cloud platforms.
For investors focused on AI infrastructure and applications, Adobe connects directly to the revenue side of the story, since its generative tools like Firefly are built into the creative and marketing workflows where brands actually produce and personalize content.
"For Adobe to undergo a significant rerating, the "AI Narrative Correction" must take place. Analysts will need to see that the "naked swimmers," startups with high burn rates and no operating cash flows, fail to disrupt the established verticals."
What happens to Adobe’s pricing power and customer stickiness if a single assumption about how professionals adopt AI-assisted workflows eventually breaks?
When that assumption starts to wobble, the full narrative for Adobe shows how Adobe’s AI push, pricing power, and ecosystem effects could still be quietly accelerating.
Oracle (ORCL)
Overview: Oracle is a global enterprise software and cloud provider. Its Oracle Cloud Infrastructure powers AI workloads, databases, and business applications for large organizations.
Operations: Oracle generates about US$62.8b from Cloud and software, US$5.8b from Services, and US$3.2b from Hardware.
Market Cap: US$446.3b
Oracle matters for this AI-focused screen because its Oracle Cloud Infrastructure and AI services give enterprises a direct on-ramp to large language models while keeping data close to existing databases and business systems.
"In 2024, OpenAI made headlines by expanding its cloud footprint to include Oracle Cloud Infrastructure (OCI), a move described as strategic, reflecting the growing demand for massive compute power and the need for multi-cloud resilience."
What happens to Oracle’s margins and bargaining power if a single unseen pressure changes how quickly that AI backlog converts into cash?
When that pressure matters most, the full narrative for Oracle examines how Oracle's AI backlog, multicloud positioning, and capital intensity could be quietly resetting the risk-reward balance.

Seeking Fresh Alternatives Beyond AI?
New themes gain momentum while older stories risk getting caught flat. Use these fresh idea lists before the crowd notices and the easy entries drop; act now.
- Spot steady cash generators and reduce blowup risk by scanning a curated list of solid balance sheet and fundamentals (23 results) that keeps financial strength and durable fundamentals front and center.
- Identify structural commodity trends early by tracking miners in the 17 top copper producer stocks before copper demand stories move from under the radar for now to fully priced.
- Follow long term electrification and infrastructure momentum by hunting for enablers in the 39 power grid technology and infrastructure stocks while critical grid upgrades still trade on yesterday's assumptions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com