
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Dekon Food And Agriculture Group (SEHK:2419) Reports August Sales As Valuation Signals Stay Mixed
Dekon Food and Agriculture Group (SEHK:2419) has published unaudited sales data for August 2026, giving investors fresh numbers on hog and poultry volumes, pricing mix, and revenue concentration.
The new August sales update lands after a choppy year for Dekon Food and Agriculture Group, with a 1 month share price return of 8.34% and a 90 day gain of 37.59%. This contrasts with a year to date share price decline of 15.66% and a 1 year total shareholder return that is down 24.39%, which suggests recent momentum has been improving even as longer term holders remain under water.
Compare Dekon Food and Agriculture Group's latest sales momentum with other livestock and protein producers by scanning our curated list of solid balance sheet and fundamentals (198 results) for potential ideas on your watchlist.
After a sharp rebound in Dekon Food and Agriculture Group shares, but with a still weak 1 year return, the question is whether current pricing still compensates you for the business and balance sheet risks. The valuation set up matters here.
Preferred Price-to-Sales of 0.9x: Is it justified?
Dekon Food and Agriculture Group last closed at HK$58.45, and on a P/S multiple of 0.9x it screens more expensive than the Hong Kong Food industry but cheaper than closer peers, which sends a mixed signal on value.
The price to sales ratio compares the company’s market value to its annual revenue. For a livestock and poultry breeder like Dekon Food and Agriculture Group, where earnings are currently loss making and margins can swing with feed costs and hog prices, investors often lean on P/S as a cleaner way to compare revenue scale against what the market is willing to pay.
On that measure, Dekon Food and Agriculture Group looks expensive compared with the broader Hong Kong Food industry average P/S of 0.7x, which suggests the market is paying a premium versus typical sector pricing. At the same time, the stock trades below the peer average P/S of 2.0x and above an estimated fair P/S ratio of 0.5x. This points to the current valuation sitting above a level the market could move towards if sentiment cools.
Explore the SWS fair ratio for Dekon Food and Agriculture Group.
Result: Price-to-sales of 0.9x (OVERVALUED)
Still, Dekon Food and Agriculture Group faces clear risks if hog and poultry pricing weakens further or if loss making operations pressure its HK$22.6b market value.
Find out about the key risks to this Dekon Food and Agriculture Group narrative.
Another view on Dekon Food and Agriculture Group's value
On price to sales, Dekon Food and Agriculture Group screens as expensive, yet the SWS DCF model points the other way. With the stock at HK$58.45 versus an estimated future cash flow value of HK$87.59, the framework suggests the shares trade at a discount. Which lens do you trust more when cash flows finally matter again?
Look into how the SWS DCF model arrives at its fair value.
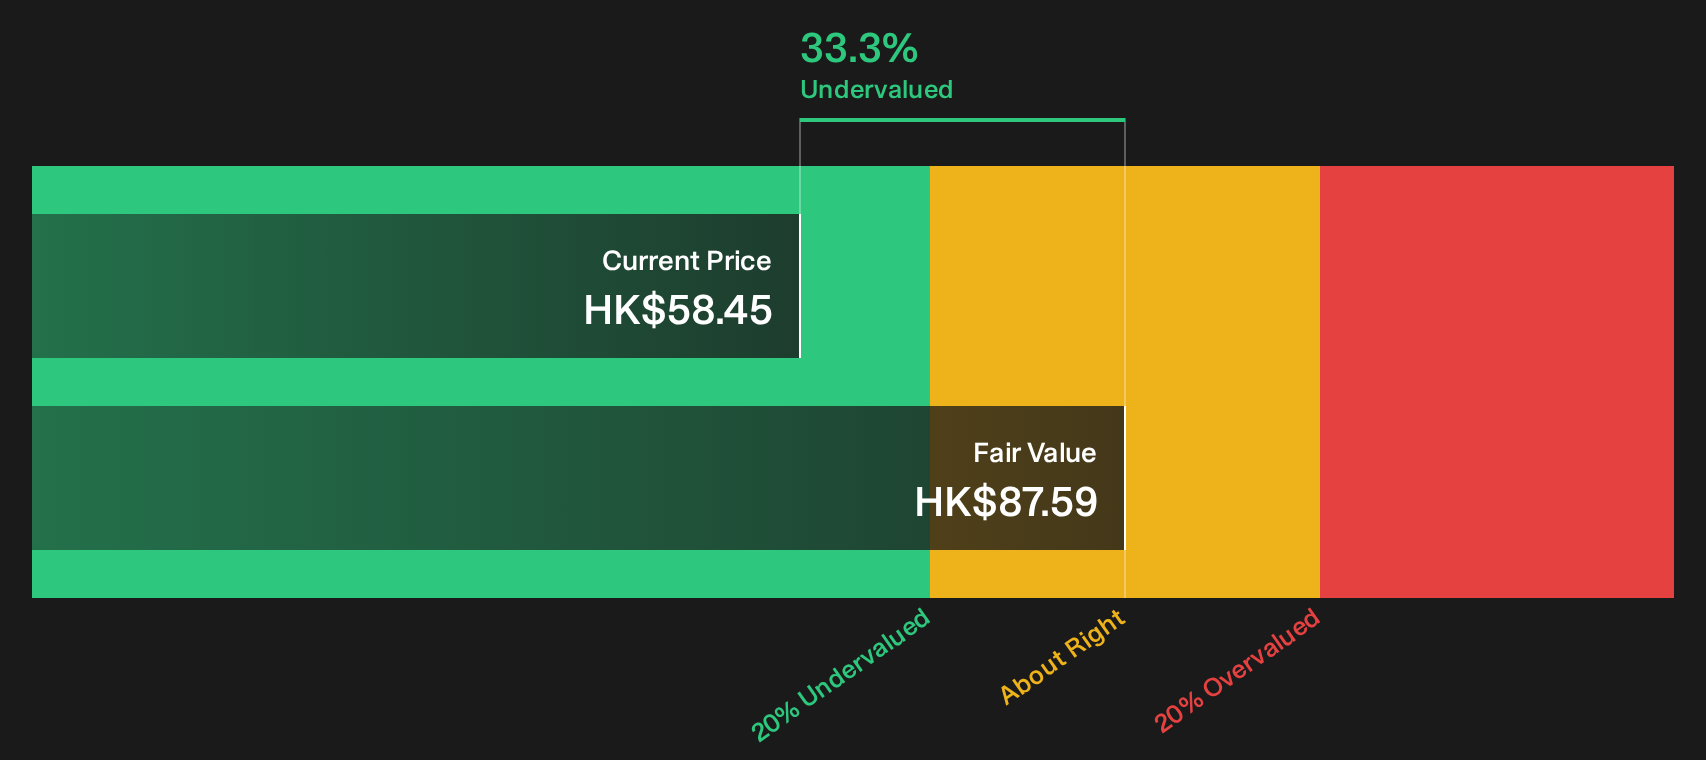
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Dekon Food and Agriculture Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 180 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Dekon Food and Agriculture Group's valuation can feel uncomfortable, so move quickly, review the underlying drivers, and pressure test the upside story through the 3 key rewards
Looking for more investment ideas beyond Dekon Food and Agriculture Group?
If Dekon Food and Agriculture Group has sharpened your focus on valuation and risk, broaden your opportunity set now before the next leg of the market cycle leaves you behind.
- Hunt for mispriced quality and tap into 180 high quality undervalued stocks that pair resilient fundamentals with more attractive entry points than Dekon Food and Agriculture Group currently offers.
- Target stability first and use the 227 resilient stocks with low risk scores to spot businesses that score well on resilience while still offering room for reasonable upside.
- Anchor your income plan and build a shortlist through the 155 dividend fortresses that focuses on higher yielding companies with the potential for steadier payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com