
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Ituran Stock Could Change Following Ministry SaaS Contract
- Ituran Location and Control reported record Q2 2026 revenue of US$104.8 million, with recurring subscription income and total subscribers both higher. The Israeli Ministry of Transport also awarded the business a multi year SaaS traffic monitoring contract worth over NIS 21 million.
- The new agreement for a nationwide Big Data traffic platform signals that Ituran Location and Control’s proprietary analytics are being adopted for core public infrastructure decisions, extending the telematics provider beyond its traditional automotive focus.
- The next area of attention will be how this strong SaaS contract win could influence Ituran Location and Control’s broader investment narrative.
Scan beyond Ituran Location and Control and compare this traffic data specialist with other telematics and data heavy businesses using our curated list of 16 high quality undiscovered gems.
Ituran Location and Control Investment Narrative Recap
For Ituran Location and Control, the big picture is about whether you think its telematics services can keep compounding subscriber-based revenue while managing margin pressure. The recent Israeli Ministry of Transport SaaS win supports that belief by reinforcing the data and software side of the business, but it does not change that subscriber additions remain the main short term catalyst.
The biggest near term risk still sits in profitability swings from product mix, currency moves, and lower margin OEM work, especially as new segments like motorcycles and usage based insurance scale. The new contract adds visibility and credibility, yet does not remove these execution and FX sensitivities.
The MOT agreement is the most relevant development. It plugs Ituran Location and Control’s Big Data platform directly into national transport planning, using anonymized information from more than 1 million vehicles. That pushes the group deeper into SaaS and analytics, which matters if you care about recurring revenue quality rather than only hardware or device sales.
For catalysts, the traffic platform win sits alongside record Q2 2026 revenue of US$104.8 million and 2.711 million subscribers. Together, these updates point to a business leaning on scale, OEM programs and data projects for future momentum, while investors still need to weigh currency volatility, OEM margins and the reliance on sustained subscriber growth.
Ituran Location and Control's narrative uses analyst forecasts that point to revenue of US$486.9 million and earnings of US$95.7 million by 2029. These figures are based on an assumed 9.1% yearly revenue growth rate and a move in earnings from US$60.1 million today to that 2029 consensus, which is an increase of roughly US$35.6 million.
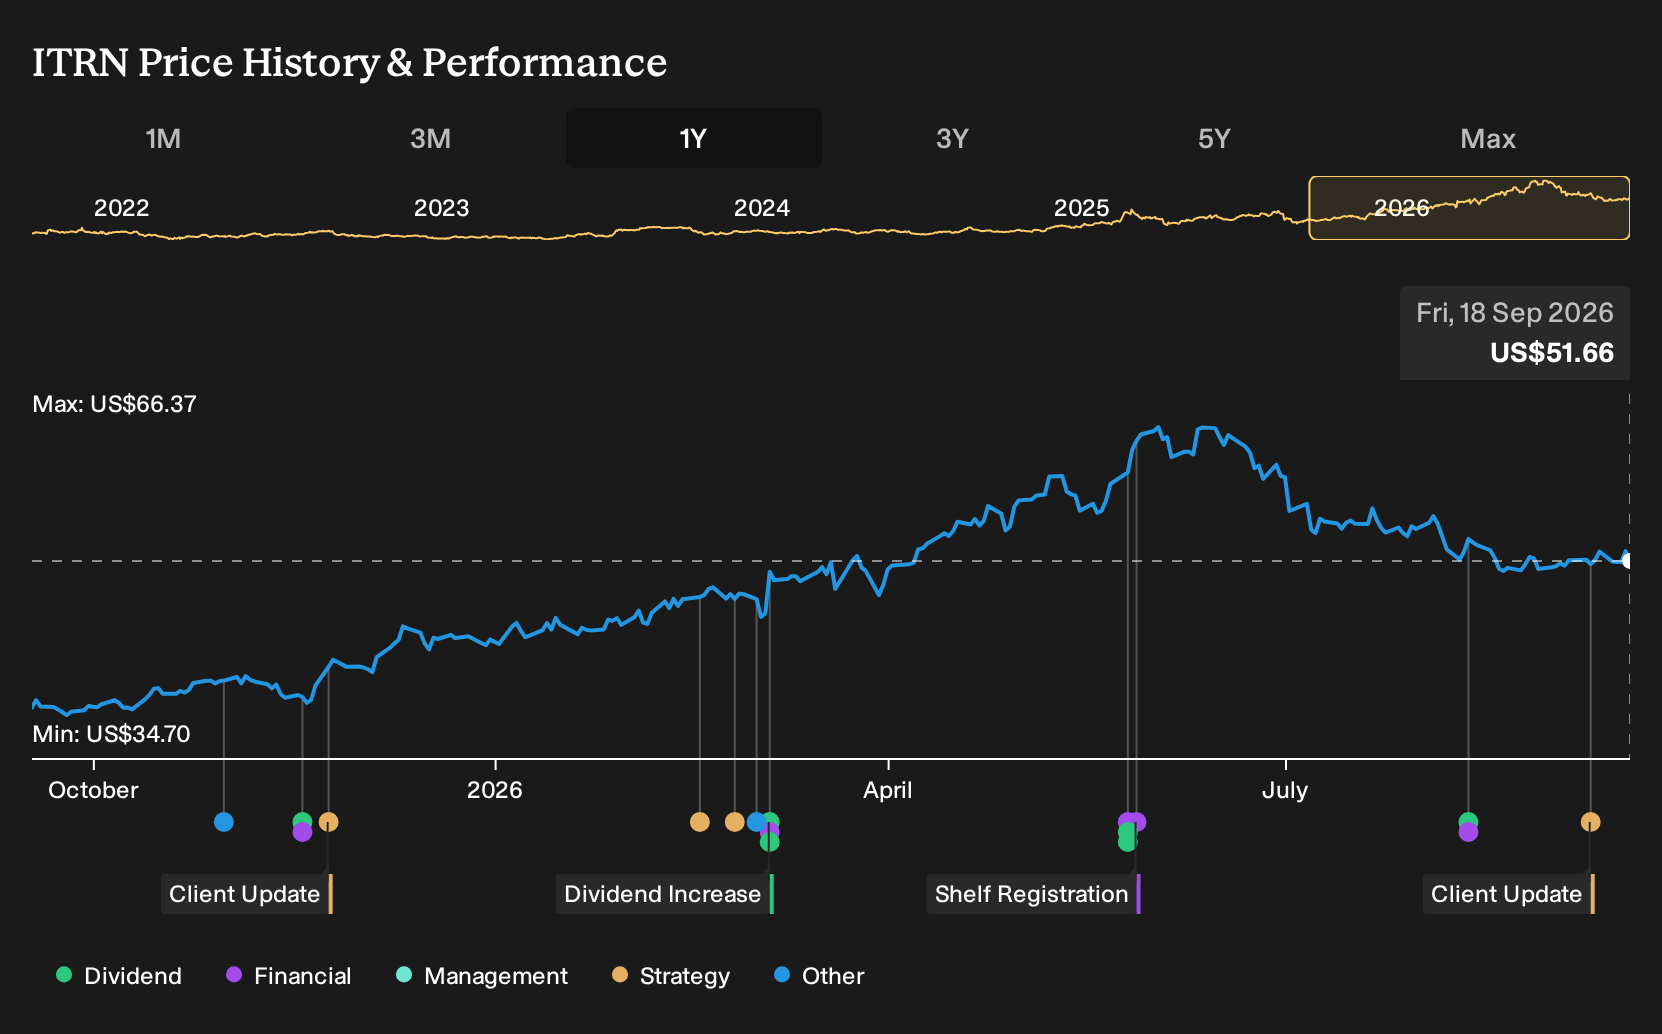
Uncover why Ituran Location and Control's fair value indicates a 42% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between US$73.5 and about US$75 per share, so retail opinions around Ituran Location and Control currently show little dispersion. That consensus sits alongside currency swings, OEM margin pressure and the new MOT SaaS deal, which together provide very different angles to test against your own view.
Explore another Ituran Location and Control fair value estimate, including one that suggests it could be worth just $73.50!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis.
- A great starting point for your Ituran Location and Control research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ituran Location and Control. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Ituran Location and Control's overall financial health at a glance.
Looking for more investment ideas beyond Ituran Location and Control?
If you want to cross check the Ituran Location and Control story against a wider opportunity set, the Simply Wall St Screener can help you quickly filter for businesses that match your own risk, quality and income preferences.
- For investors who want potential upside with a margin of safety on fundamentals, consider starting with 33 high quality undervalued stocks that pass strict quality checks.
- If capital preservation and steadier profiles matter most to you, focus on 30 resilient stocks with low risk scores that score well on Simply Wall St's risk framework.
- Income seekers who prefer cash returns today can review 6 dividend fortresses that offer yields of 5% or more.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com