
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Seazen Group (SEHK:1030) Could Be 204% Above Fair Value After August Sales Update
Fresh contracted sales data from Seazen Group (SEHK:1030) for August 2026 has given investors new numbers to assess, with both monthly and year-to-date figures now on the table.
The August sales update lands as Seazen Group’s share price has bounced in the short term, with a 1-day share price return of 5.32% and a 7-day share price return of 9.19%. However, the year-to-date share price return is still down 28.26% and the 1-year total shareholder return has declined 43.32%, suggesting recent momentum is building off a much weaker longer run.
Stress test Seazen Group’s recent sales update against a curated 180 high quality undervalued stocks that combines operational traction with balance sheets investors can scrutinize side by side.
Seazen Group now has fresh sales figures on the table and a share price that has jumped in the past week. The real question is whether that mix adds up to a solid business at a sensible valuation.
Preferred P/E of 29.7x on Seazen Group: Is it justified?
On the latest numbers, Seazen Group is trading on a P/E of 29.7x, which sits well above both its Hong Kong real estate peers and the wider local market even after a share price that has fallen sharply over 5 years.
The P/E ratio compares the HK$ share price with earnings per share and gives a quick sense of how much investors are paying for each unit of profit. For a property developer and manager like Seazen Group, a higher P/E can reflect expectations that current earnings are depressed relative to what the business might earn in future cycles.
Here, the headline valuation is stretched. The stock is described as expensive against the Hong Kong Real Estate industry average P/E of 8.9x and also above a peer average of 26.4x. It is even slightly rich compared with an estimated fair P/E of 28.3x that the market could move toward if sentiment cooled and pricing aligned more closely with underlying fundamentals.
Seazen Group’s current multiple therefore sits materially above sector norms and a touch higher than the modelled fair ratio.
Explore the SWS fair ratio for Seazen Group.
Result: Price-to-earnings of 29.7x (OVERVALUED)
Still, the sharp 5 year share price decline of 75.81% and annual revenue contraction of 22.23% leave Seazen Group exposed if earnings momentum stalls again.
Find out about the key risks to this Seazen Group narrative.
Another view on Seazen Group’s value
The SWS DCF model paints a different picture for Seazen Group. On this view, the HK$1.49 share price sits above an estimated future cash flow value of about HK$0.49, which points to an overvalued result rather than a bargain.
That gap raises a simple question for investors. Is the current price reflecting earnings power that the DCF model is not capturing, or is the market leaning too hard on recent profit strength that may not last through the cycle?
Look into how the SWS DCF model arrives at its fair value.
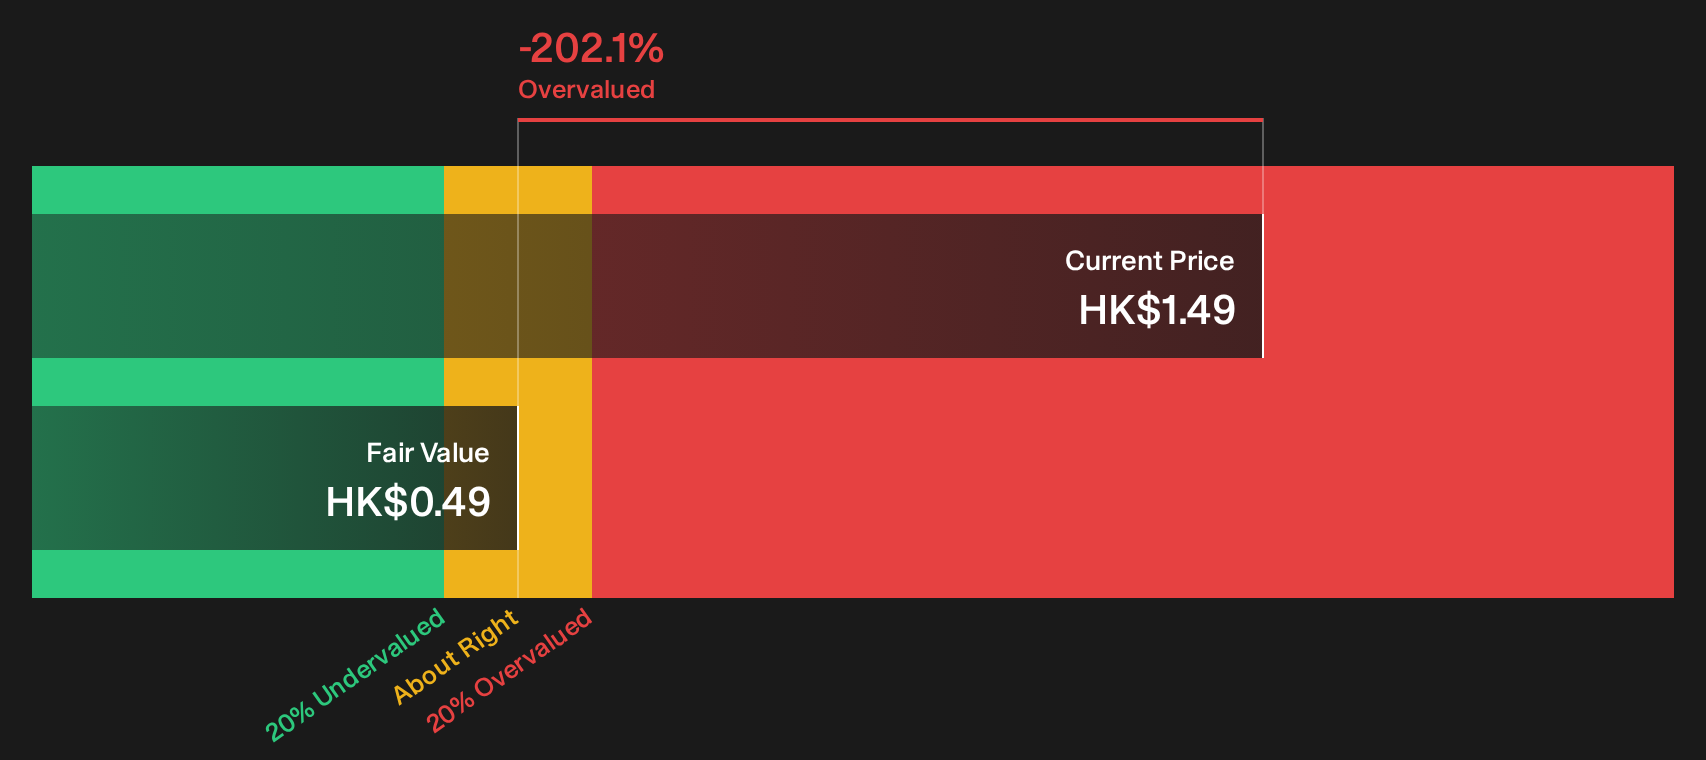
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Seazen Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 180 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Seazen Group is mixed, with fresh sales data and valuation flags pulling in opposite directions. Move quickly, compare the full picture, and weigh both the 2 key rewards and 1 important warning sign.
Looking for more Seazen Group sized investment ideas?
Do not stop with Seazen Group. Use the same disciplined lens on other opportunities so you are not relying on a single stock to carry your portfolio.
- Target quality at a discount by scanning a 180 high quality undervalued stocks that blends strong fundamentals with pricing that still looks reasonable on the numbers.
- Build income resilience by focusing on companies in the 155 dividend fortresses that offer higher yields supported by financial details you can easily compare.
- Reduce portfolio stress by filtering for resilient businesses in the 227 resilient stocks with low risk scores that score well on stability instead of relying on story alone.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com