
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Strong Results And Dividend Hike Require Action From Karooooo Stock Investors?
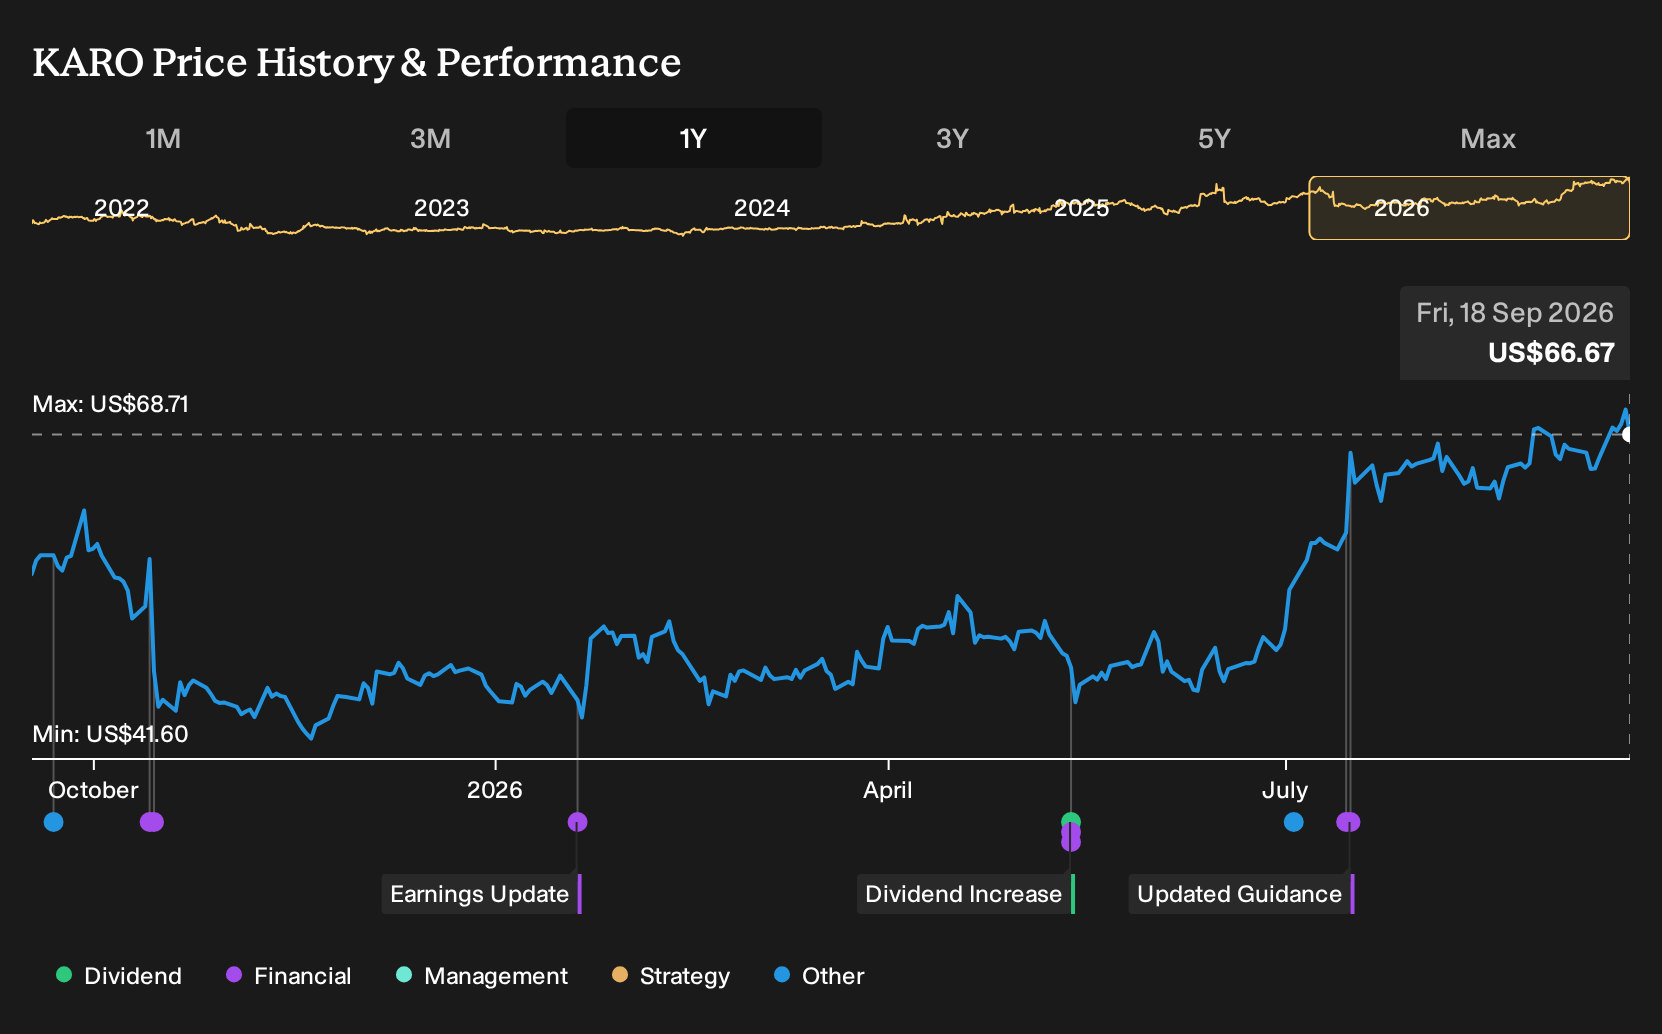
- Karooooo reported a strong start to FY27, with Cartrack subscription revenue growth of 19% in Q1, record net subscriber additions of 142,472 led by South Africa, record operating profit of ZAR 410 million, and a 1.5 US dollar dividend per share that was 20% higher than the prior year.
- The quarter highlighted how new offerings such as Cartrack Tag and video solutions, together with earlier sales capacity investments, are contributing to both subscriber momentum and the company’s decision to lift its dividend.
- We will now look at how Karooooo's investment narrative could shift in light of record operating profit and a higher dividend.
Compare Karooooo's momentum in subscriptions and dividends with other operationally solid companies by scanning our hand picked list of solid balance sheet and fundamentals (23 results).
Karooooo Investment Narrative Recap
To own Karooooo, you need to be comfortable with a mobility SaaS business that still leans heavily on South Africa while trying to build out newer regions and products. The latest quarter, with strong Cartrack subscription momentum and record operating profit, supports that core thesis but does not erase concentration in one key market.
The near term swing factor is execution on sales capacity and cross selling of tools like Cartrack Tag and video, which now show up in higher subscriber adds. The main risk is that reliance on South Africa and slower ARPU progress limit how much of that subscription growth turns into sustained margin and free cash flow strength.
The dividend decision is the announcement that most clearly ties into this Q1 update. Karooooo lifted the payout to 1.5 US dollars per share, 20% higher than last year, which indicates confidence in its cash generation and balance sheet flexibility despite ongoing investment needs.
For you as a shareholder, that higher dividend can be a useful test of discipline. Subscription growth, record operating profit of ZAR 410 million and rising capital returns need to stay balanced against risks flagged earlier, such as dividend cover by free cash flow and the cost of continued expansion outside South Africa.
Karooooo's narrative projects ZAR 9.1b revenue and ZAR 1.8b earnings by 2029. This assumes 16.5% yearly revenue growth and an earnings increase of about ZAR 800m from ZAR 1.0b today.
Uncover how Karooooo's fair value indicates a 10% potential upside to its current price before the gap closes.
Exploring Other Perspectives
One alternate view on Karooooo focuses on revenue potential rather than concentration risk. The most optimistic analysts were already pencilling in ZAR 10.0b of revenue and ZAR 2.0b of earnings by about 2029, above the consensus ZAR 9.1b and ZAR 1.8b. That more upbeat script may shift again once this Q1 update is fully absorbed, so treat it as one of several viewpoints to test against your own expectations.
Explore 3 other Karooooo fair value estimates, including one that suggests there could be as much as 20% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Karooooo research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Karooooo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Karooooo's overall financial health at a glance.
Looking for more investment ideas beyond Karooooo?
If Karooooo has helped sharpen what you want from a business, use that same lens across the wider market. A focused screener can quickly surface stocks that line up with your preferences on quality, income, or risk.
- If you want potential mispricing on your side, start by scanning 33 high quality undervalued stocks that pair stronger fundamentals with prices that may not fully reflect them.
- For investors who care most about consistency and resilience, consider reviewing 30 resilient stocks with low risk scores that score well on balance sheet strength and earnings stability.
- If you are hunting for future leaders before they are widely followed, check out 16 high quality undiscovered gems that combine solid financials with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com