
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Reserve Update Could Be A Game Changer For Pan American Silver Stock (TSX:PAAS)
- Pan American Silver reported updated mineral reserves and resources as of June 30, 2026, following extensive drilling and near-mine exploration across its portfolio, including its 44% share of the Juanicipio operation.
- The reshaped reserve base, including new veins at La Colorada and additional ounces at multiple mines, shows how exploration and portfolio changes are redefining Pan American Silver’s long-term asset mix.
- This article examines how Pan American Silver's investment narrative is influenced by the enlarged reserve base from its 2026 drilling program.
Extend the Pan American Silver thesis across the sector by comparing its reserve-heavy profile with other producers in our hand picked 10 top silver producer stocks.
Pan American Silver Investment Narrative Recap
To own Pan American Silver, you need to be comfortable with a miner that is leaning into a very large reserve and resource base while still relying on clean execution at a handful of complex sites. The updated 2026 reserve statement strengthens the long term asset inventory but does not by itself change the near term production profile.
Right now, the key short term swing factor is progress at La Colorada Skarn and related high grade zones, along with optimization work at Jacobina and the more challenged gold operations. The biggest risk is project slippage or higher costs at these assets, which could lift all in sustaining costs and strain capital even with a deeper reserve pipeline.
The June 30, 2026 mineral reserve and resource update is the headline announcement that matters most here. Pan American Silver now estimates about 511.1 million ounces of silver and 6.3 million ounces of gold in proven and probable reserves, with over 1.1 billion ounces of silver sitting in measured and indicated resources and a further 437.0 million ounces in inferred material.
That scale, plus the 44% share of Juanicipio and the drilling success across La Colorada, Jacobina, Huaron, San Vicente, Cerro Moro and Minera Florida, gives management more options to sequence projects and extend mine lives. It does not remove risk at La Colorada Skarn, Jacobina tailings or the technically complex gold mines, but it gives the business more ways to respond if any single project underperforms.
How Pan American Silver’s Reserve Story Connects To Analyst Expectations
Analysts who follow Pan American Silver are effectively tying the enlarged reserve base to a slower but steady build in the financials. The current consensus assumes revenue grows by 5.7% per year over the next three years, with profit margins rising from 31.6% today to 35.4% as projects like La Colorada Skarn and various optimization efforts mature.
On earnings, the market is working off a starting point of about US$1.3b today and a central forecast of US$1.7b by 2029. That implies an increase of roughly US$400m in profit, even though analyst views are wide, with the most optimistic closer to US$1.8b and the most cautious nearer to US$1.2b. The same 2029 anchor year is used for top line expectations, with consensus revenue estimates of US$4.7b.
Pan American Silver's narrative incorporates analyst estimates of US$4.7b in revenue and US$1.7b in earnings by 2029, which reflect the 5.7% yearly revenue growth assumption and an earnings increase of roughly US$400m from US$1.3b today.
Uncover why Pan American Silver's fair value indicates a 32% potential upside to its current price that could narrow quickly.
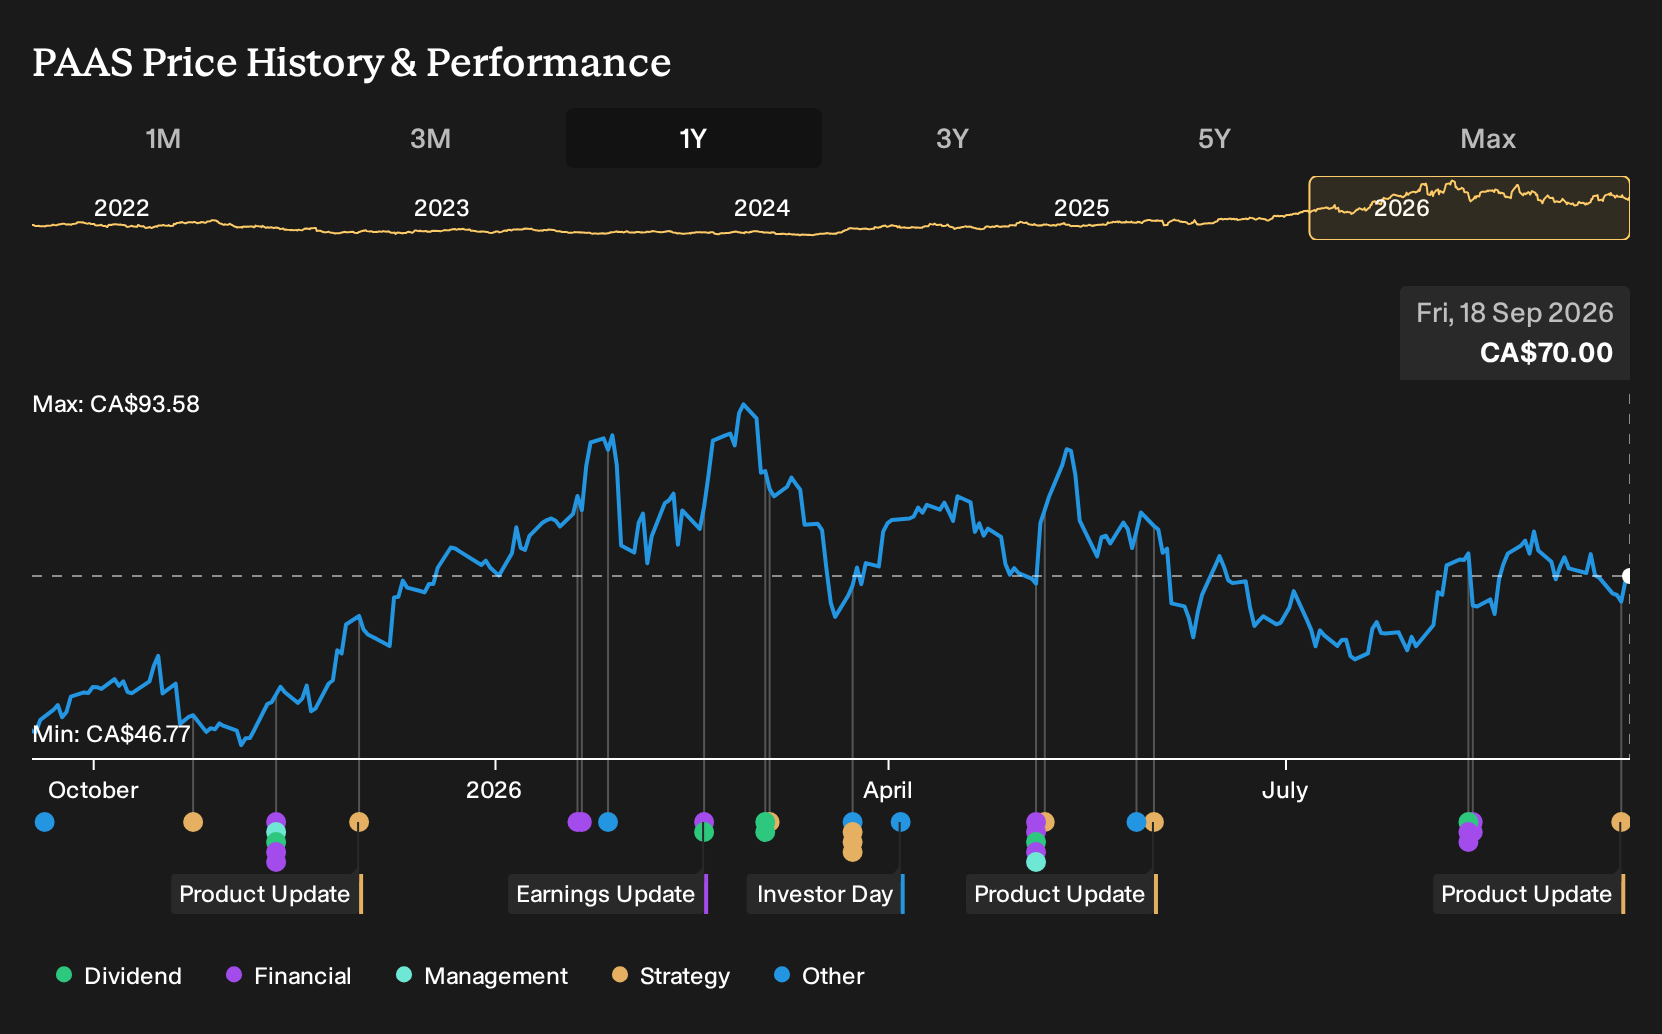
Exploring Other Perspectives
One alternate angle to watch is the bullish focus on La Colorada Skarn as a cost game changer. Before this reserve update, the most optimistic analysts were already pencilling in about US$5.3b of revenue and US$2.1b of earnings by 2029. You can see how this fresh drilling news might either push those views even further or cause some to reassess them entirely.
Explore 4 other Pan American Silver fair value estimates, including one that suggests up to 52% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Pan American Silver research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Pan American Silver. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate Pan American Silver's overall financial health at a glance.
Looking for more investment ideas beyond Pan American Silver?
If the Pan American Silver story has you thinking about portfolio balance and risk, it can be useful to widen the lens and compare it with other companies that fit specific traits you care about, from cash strength to income potential or overlooked quality.
- For investors who care most about resilient balance sheets and fundamentals, start with this focused list of solid balance sheet and fundamentals (7 results) that can help you filter for financially sturdy businesses.
- If your priority is income, use the 1 dividend fortresses to spot companies that pair higher yields with characteristics that may support ongoing payouts.
- To hunt for lesser known opportunities with strong underlying numbers, sort through the 9 high quality undiscovered gems and see which under-followed stocks match your criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com