
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Snowflake (SNOW) Stock Looks Above Fair Value On Its 122% Run
Snowflake has delivered a strong multiyear share price run, and the stock most recently closed at US$332.43. That kind of performance puts a spotlight on a simple question for anyone looking at the chart today: whether the current price makes sense when set against its sales.
- Over the past 3 years Snowflake has returned 122.1%, which raises the question of how much future sales progress is already reflected in the share price.
- Management is leaning hard into AI driven data products, which can shape expectations for how efficiently the business turns its data footprint into revenue growth and eventually into cash generation.
- There is a second opinion on Snowflake worth weighing. See what analysts think Snowflake's shares could be worth.
For investors, the debate is whether Snowflake's current valuation is adequately supported by the sales it generates today and what it may realistically add over time.
If you want to test this same sales based valuation question beyond Snowflake's AI story, line it up against a wider field using 88 AI infrastructure stocks.
Is Snowflake Getting Expensive on Sales?
P/S is the cleaner lens for Snowflake right now because earnings are not yet the main driver of how investors frame the story.
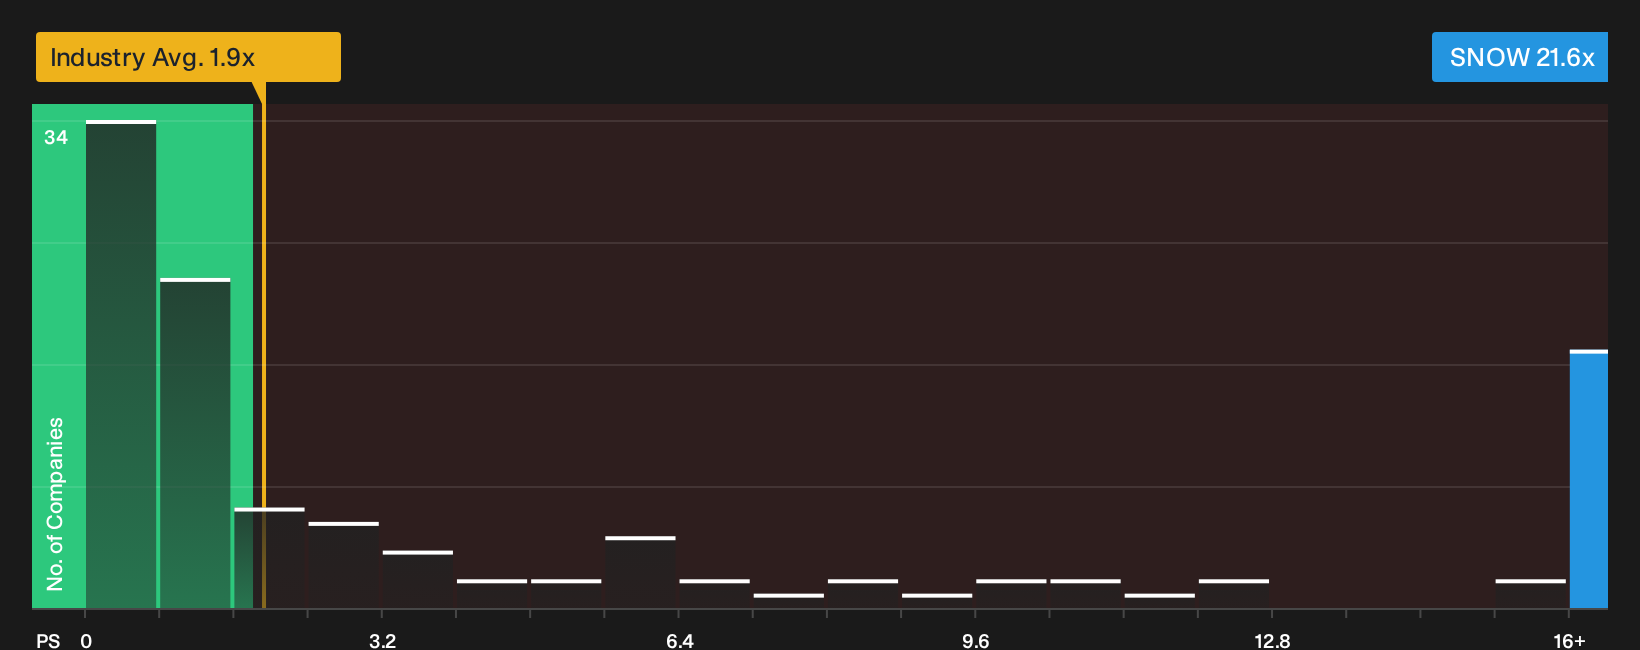
Snowflake trades on a P/S of about 21.6x, which is much higher than the broader IT sector on roughly 1.9x and still above closer peers on about 18.8x. A fair P/S level implied by its growth, margins, size and risk profile screens lower than where the stock currently changes hands, so the present sales multiple points to Snowflake being overvalued on this framework.
Because management is pushing hard into AI heavy data products and user-facing tools, recent excitement around that shift appears to be reflected in how much investors are willing to pay for each dollar of Snowflake revenue. Anyone considering the shares needs to judge whether that premium P/S ratio is justified by the company’s data footprint, AI positioning and path to cash generation. Explore the numbers behind Snowflake's P/S valuation.
The Snowflake Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Snowflake pick up where the P/S puzzle leaves off. Each scenario explains what would need to happen to Snowflake's growth, profitability and earnings profile for the current share price to appear high or low. Rather than relying on a single multiple or model line, every narrative sets out the assumptions behind its view of value so you can compare those expectations with the actual numbers as they are reported, all hosted on the Community page.
The Snowflake community splits into two clear camps on valuation, with one side seeing meaningful upside and the other flagging a steep premium.
Bull case: 20% undervalued
"Rapid product innovation, including the launch of ~250 new features and expanded offerings such as Snowflake Intelligence, Cortex AI SQL, and Postgres support, is increasing average revenue per user and deepening customer stickiness…"
Discover why this Narrative puts Snowflake at 20% undervalued.
Bear case: 322% overvalued
"Databricks, Snowflake''s primary competitor, recently secured funding at a $100 billion valuation, that''s actually higher than Snowflake''s current market capitalisation…"
Explore why this Narrative puts Snowflake at 322% overvalued.
One more Snowflake check that sits beyond today's price tag
Before closing the file on Snowflake, it is worth asking how professional analysts currently map out the business a few years from now, and then lining that view up against today's market value. Explore where analysts expect Snowflake to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com