
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
KB Home (KBH) Could Be 19% Undervalued As Lakeside Bluffs Opens
What the new Lakeside Bluffs launch means for KB Home stock
KB Home (KBH) just opened Lakeside Bluffs in Lake Stevens, Washington, a new ENERGY STAR focused townhome community that gives investors a fresh data point on the builder's product mix and regional footprint.
Recent trading tells a different story to KB Home’s new project pipeline. The share price has fallen 16.5% over the past month and is down 17.4% year to date, while the 5 year total shareholder return of 24.0% shows that longer term holders have still seen gains.
Spot under-pressure homebuilders like KB Home, and compare them with other companies that screen for value and quality using our curated 33 high quality undervalued stocks.Bulls point to KB Home’s earnings profile, townhome push and valuation screens. Bears focus on the share price slide and legal overhang. Which story do the numbers lean toward as you weigh today’s valuation?
Most Popular Narrative: 19% Undervalued
KB Home's most followed valuation storyline puts fair value at $58.25 per share, compared with the last close of $47.12. This narrative frames recent weakness as a discount rather than a reset in fundamentals.
KB Home is executing a land investment strategy that is increasing their lot position while returning capital to shareholders through share repurchases. This balanced approach aims to enhance earnings growth and shareholder value over the long term.
See why 14 investors see KB Home as 19% undervalued.
Result: Fair Value of $58.25 (UNDERVALUED)
Still, softer demand that led KB Home to cut its 2025 revenue guidance, along with regional pricing pressure in markets like Florida, could quickly challenge that undervalued story.
Find out about the key risks to this KB Home narrative.
Another View: KB Home and the cash flow gap
The first storyline paints KB Home as undervalued based on earnings and analyst targets. A different lens tells a sharper story. The Simply Wall St DCF model estimates future cash flow value at just $8 per share, well below the recent $47.12 price, which points to a much richer valuation. That is a wide gap for you to reconcile.
For investors who want to see exactly how that cash flow view is built, it helps to walk through the numbers step by step with the SWS DCF model. Look into how the SWS DCF model arrives at its fair value.
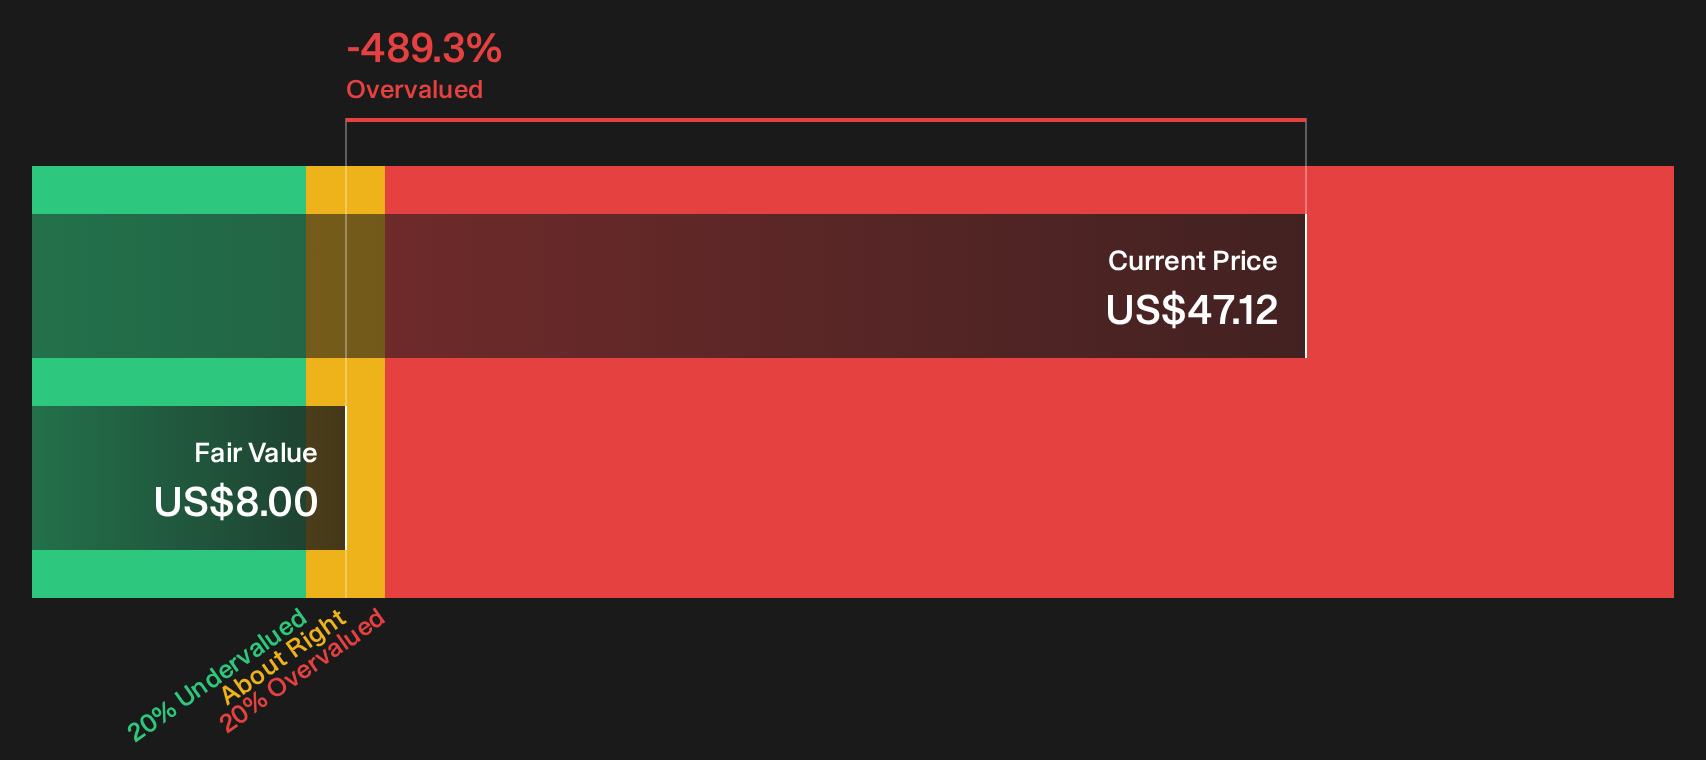
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out KB Home for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If you are weighing KB Home’s potential and the concerns described in this article, or if you already have a clear view, act promptly and stress test that perspective against the underlying data with 5 key rewards and 3 important warning signs.
Looking for more investment ideas beyond KB Home?
If KB Home is on your radar, broaden your watchlist with a few other angles that could complement or contrast what you see in this builder.
Use the Simply Wall St Screener to compare potential opportunities and avoid getting boxed into a single story when the market offers plenty of alternatives.
- Target potential mispricing by scanning a curated pool of companies that balance quality with attractive entry points through our 33 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses that pair higher yields with resilience using the 6 dividend fortresses.
- Limit downside risk by concentrating on financially robust candidates drawn from our list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com