
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
TDK (TSE:6762) Could Be 26% Undervalued Following Its R3 Lithium Investment
Event driven focus on TDK after R3 Lithium investment
TDK (TSE:6762) drew fresh attention after its venture arm backed R3 Lithium, linking the electronics group more directly to lithium carbonate recycling and to future battery material supply chains for energy storage and AI hardware.
Recent trading in TDK reflects that crosscurrent. The share price has eased about 27% over the past 90 days and is down 5.5% over the last month, yet still shows a 26.4% year to date gain and a very strong five year total shareholder return of 273.3%. This suggests momentum has cooled in the short term while the longer arc has rewarded patient holders.
Scan beyond TDK and see how other battery and AI hardware suppliers compare in the 88 AI infrastructure stocks.
Bulls point to TDK’s lithium exposure, AI ecosystem role and long run of shareholder returns. Bears focus on recent share price weakness and valuation risk. Which side does the current pricing really support?
Most Popular Narrative: 26% Undervalued
Analysts following TDK see more value than the market is currently pricing in, with a narrative fair value of ¥3,830.59 versus a last close of ¥2,845. That gap rests on a view that the AI focused battery and components pipeline can support higher profits over time.
TDK's investment and growth strategy in the AI ecosystem is expected to be a significant catalyst for future growth, targeting a growth rate of 25% to 30% over the mid to long term. This could positively impact revenue as they capitalize on emerging technologies and markets.
See why 2 investors see TDK as 26% undervalued.
Result: Fair Value of ¥3,830.59 (UNDERVALUED)
Still, the bullish TDK story meets some real friction, including ongoing U.S. antitrust litigation and softer demand in automotive and industrial passive components that could pressure profits.
Find out about the key risks to this TDK narrative.
Another View: TDK and the DCF Pushback
The analyst narrative frames TDK as 26% undervalued against a fair value of ¥3,830.59, yet the SWS DCF model paints a cooler picture. On that cash flow view, the shares at ¥2,845 sit above an estimated value of ¥2,260.04, which points to an overvalued outcome.
This clash between a higher narrative value and a lower DCF estimate leaves a simple question for investors: Which story feels more believable when you think about TDK's future cash generation and risk profile?
Look into how the SWS DCF model arrives at its fair value.
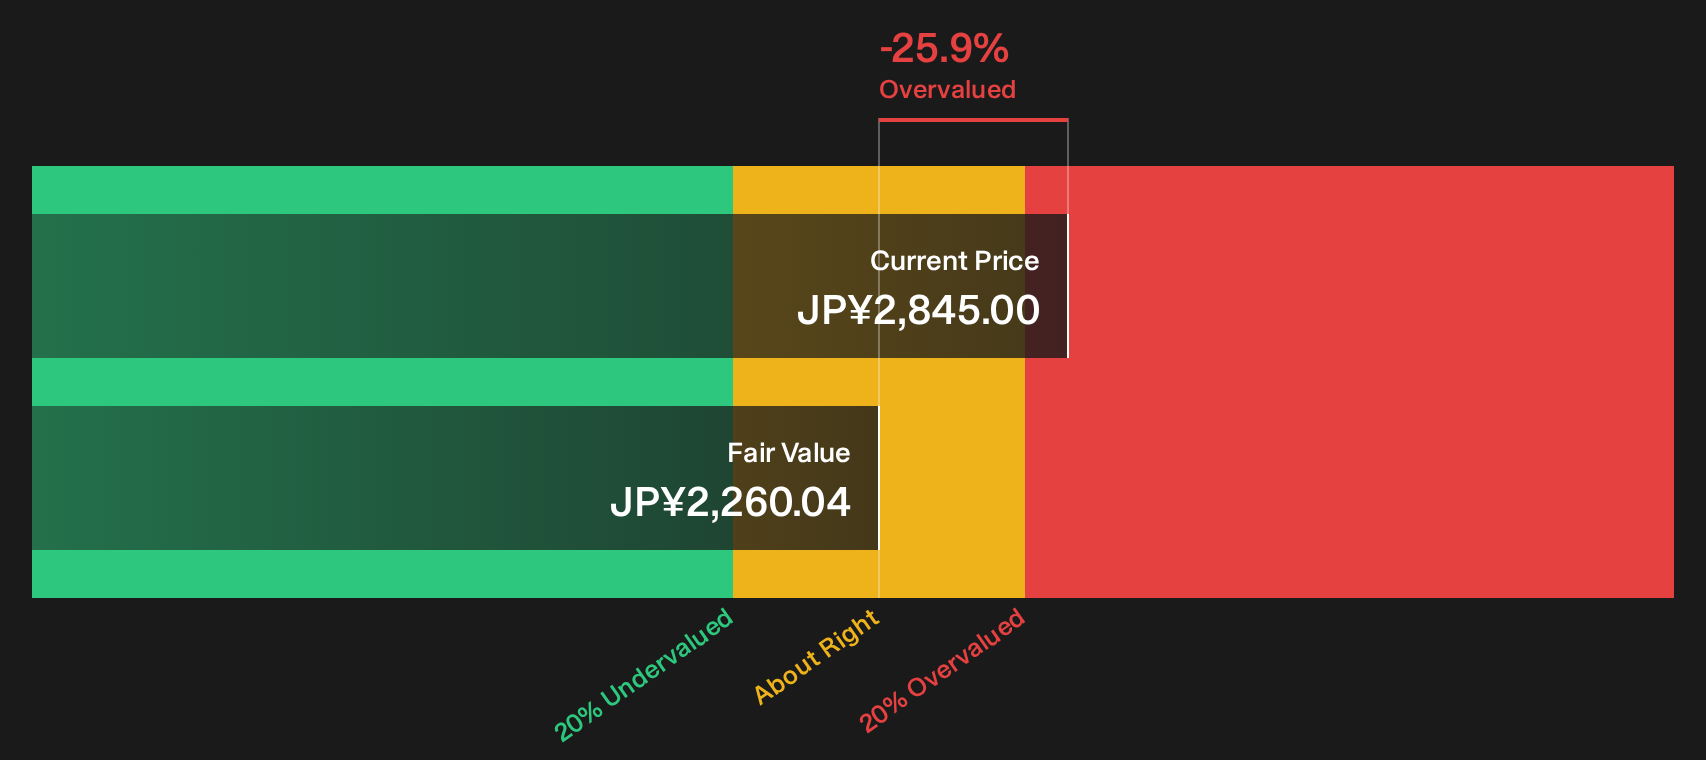
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out TDK for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals on TDK leave you on the fence, move quickly from headline stories to hard numbers and pressure test the bullish and bearish arguments against the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond TDK?
If TDK's story has you thinking bigger, use the Simply Wall St Screener to size up alternatives and avoid missing opportunities sitting in plain sight.
- Target quality at a discount with the 17 high quality undervalued stocks that surfaces financially strong businesses trading below their estimated worth.
- Prioritise resilience by scanning the 21 resilient stocks with low risk scores to focus on companies with steadier risk profiles and fewer financial red flags.
- Get ahead of the crowd through the 75 high quality undiscovered gems that highlights underfollowed stocks with solid fundamentals before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com