
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 High Quality Dividend Stocks For Steady Income As Rates Stay Higher
Interest rates are climbing again, inflation is stubborn, and headline stock indexes have been restless since mid August, which puts steady cash returns back in the spotlight for many investors. Reliable dividends can feel like solid ground when borrowing costs rise and growth stories come under pressure. This article walks through 3 dividend-focused stocks exposed to these macro shifts and explains how each one could factor into your portfolio decisions now.
The stocks highlighted below are a small sample of what screens well for quality and yield right now, and the full filter surfaced 15 more large caps with similarly robust dividend stories that are not covered in this article.
If you want to identify and analyze the highest conviction ideas using the same rules, head straight to the High-Quality Dividend Stocks screener.
Ingredion (INGR)
Ingredion plugs neatly into the High-Quality Dividend Stocks theme because it sells essential starches and sweeteners into everyday food and industrial products where demand tends to be steady, which helps support consistent cash generation for dividends even as rates and inflation move around.
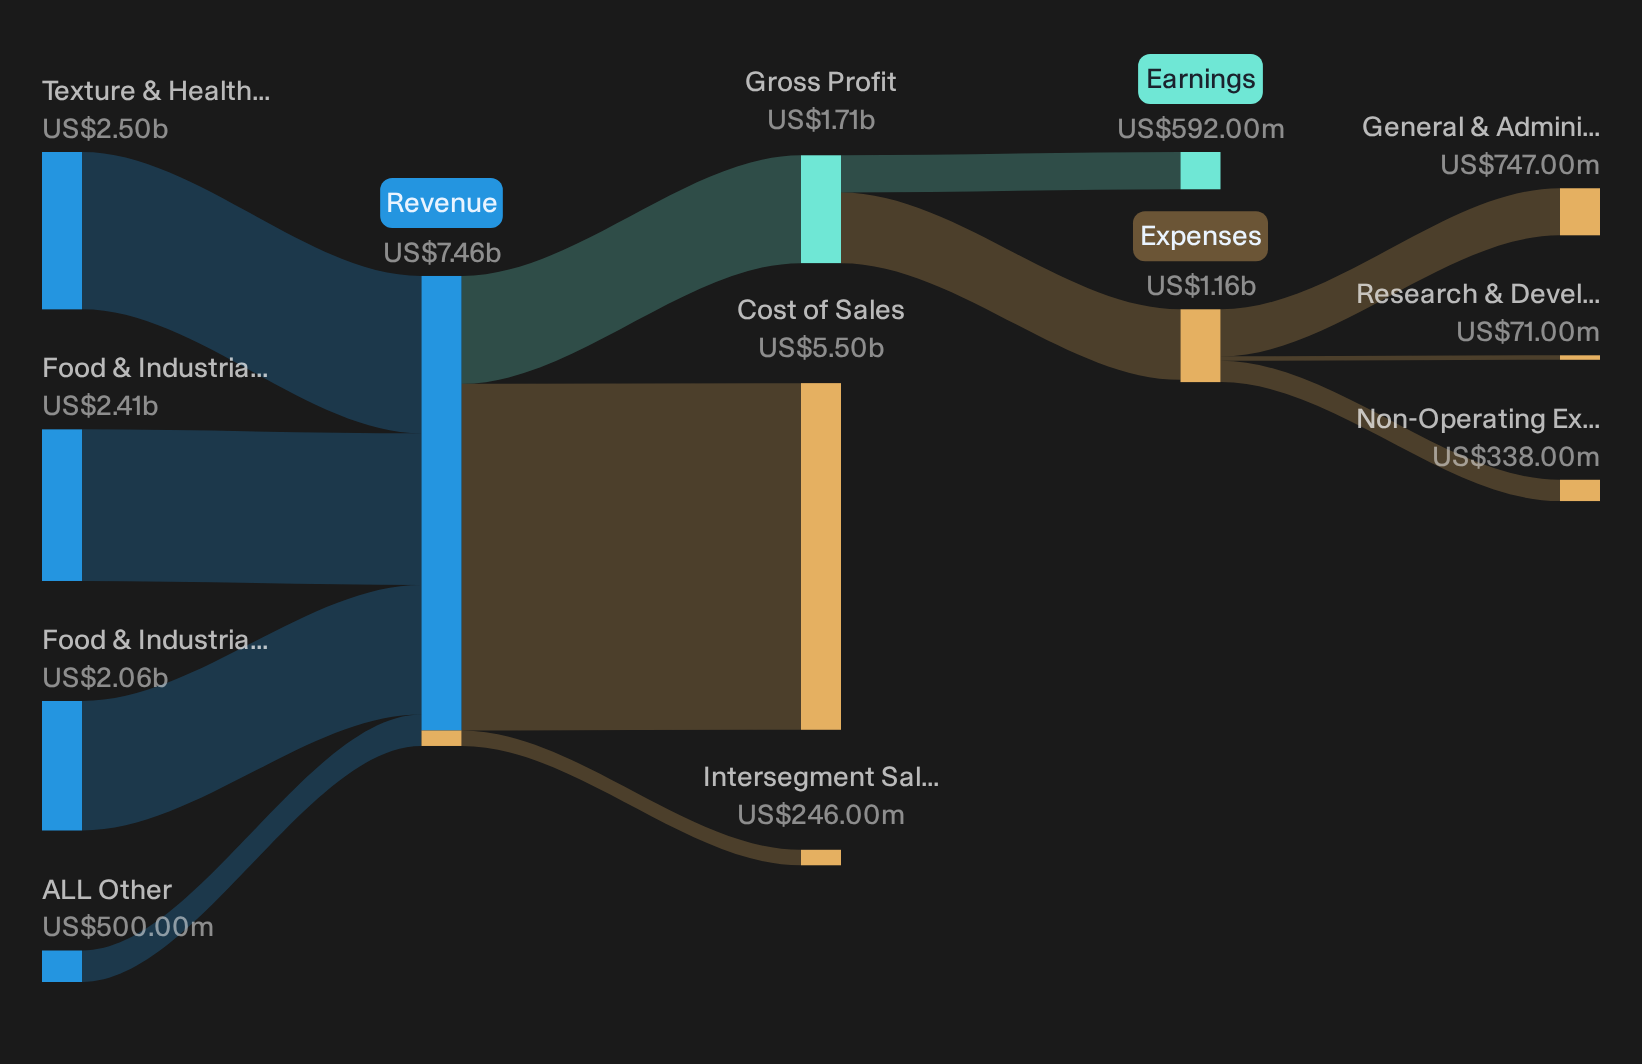
Ingredion manufactures starches, sweeteners and specialty nutrition and biomaterial ingredients for food and industrial customers worldwide, with Texture & Healthful Solutions contributing about US$2.5b of revenue, Food & Industrial Ingredients LATAM US$2.4b, U.S./Canada US$2.1b and other activities about US$500 million, and the stock valued around US$6.2b.
Ingredion’s appeal for dividend investors today rests on that essential-ingredient profile, and on how effectively management is trying to tilt the business toward higher value products.
"The acquisition of Tate & Lyle has the potential to transform Ingredion from a predominantly commodity-oriented starch and sweetener processor into a more global specialty ingredients platform. If management successfully integrates Tate & Lyle, delivers the expected synergies, and maintains its strong ROIC and free cash flow generation, the company could deserve a meaningfully higher valuation over the next 3 to 5 years."
What matters most now is how one quiet shift in the mix of products and customers feeds through into the cash flows that ultimately fund those payouts.
Those shifting cash flows are exactly what the full narrative for Ingredion unpacks in detail, including where Ingredion’s tilt toward specialty ingredients could be quietly accelerating returns.
Snap-on (SNA)
Snap-on fits the High-Quality Dividend Stocks theme because it sells essential tools and repair systems to professional users, which can support steady cash generation for dividends even when rates and inflation are pressuring more cyclical parts of the market.
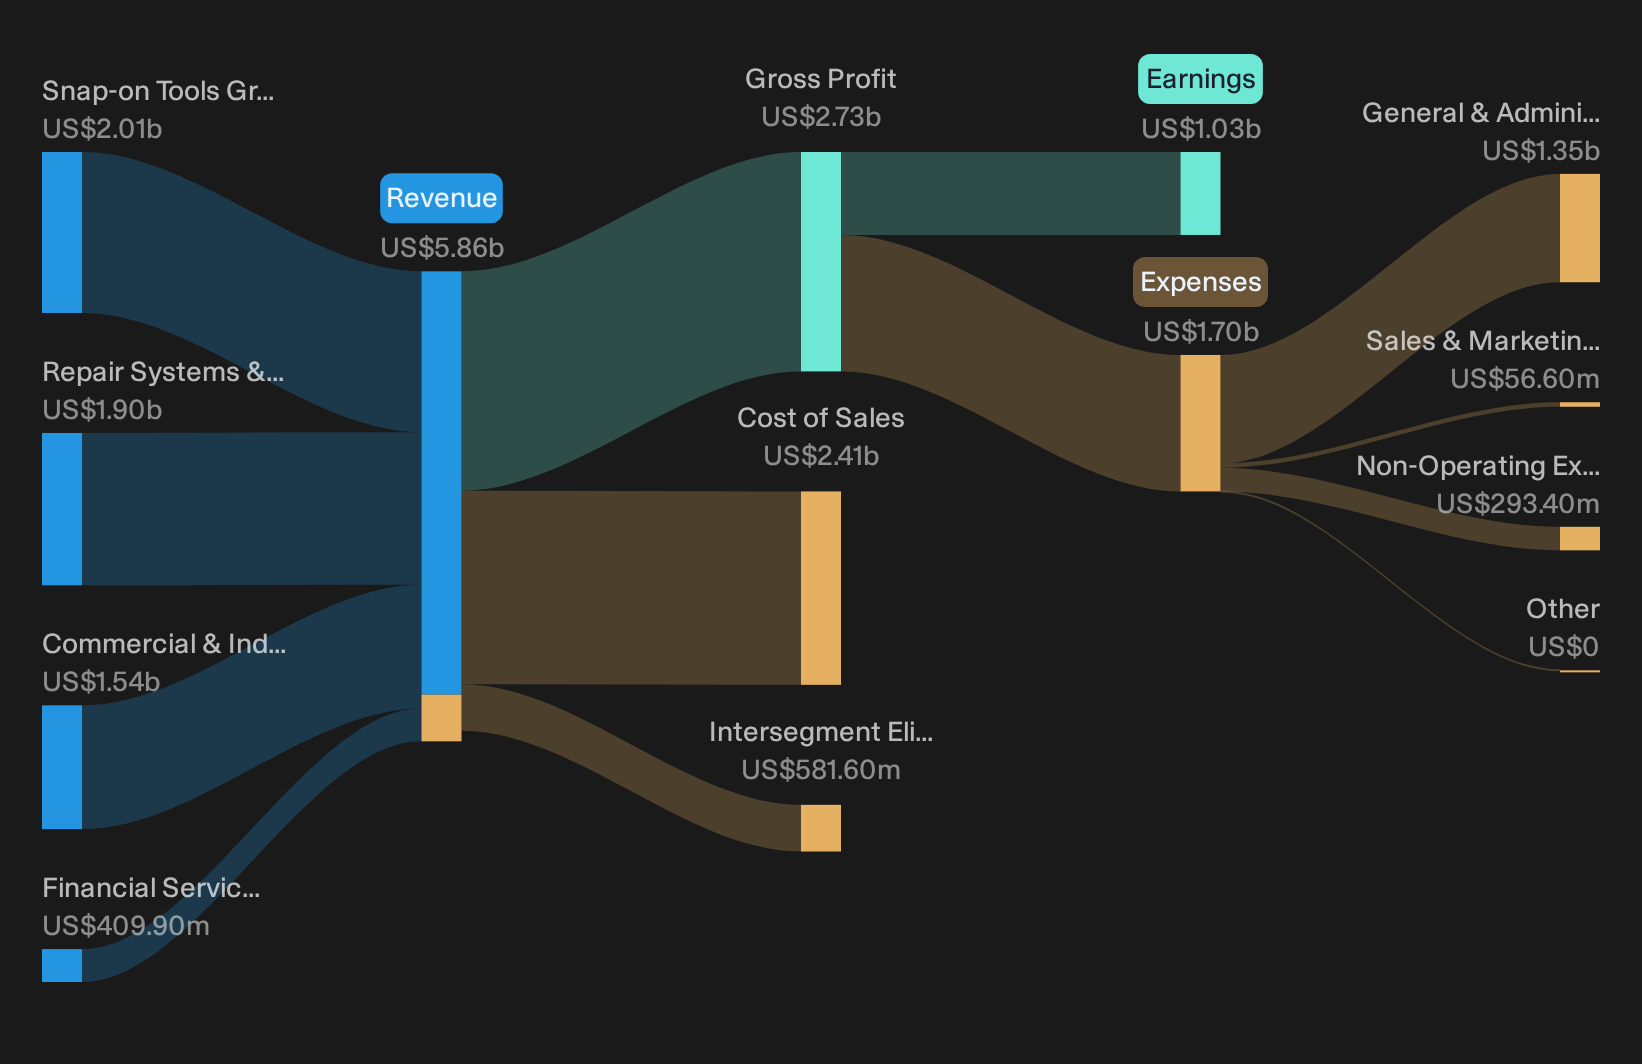
Snap-on manufactures professional tools, repair equipment and diagnostics, with around US$2.0b from Snap-on Tools Group, US$1.9b from Repair Systems & Information, US$1.5b from Commercial & Industrial, and US$410 million from Financial Services, and the stock valued near US$19.2b.
"With the shift toward more protectionist policies aimed at encouraging domestic manufacturing, US companies already producing on home soil may now be well positioned."
For Snap-on, what really matters over the next stretch is how one subtle shift in repair spending patterns interacts with that home-soil advantage.
That subtle shift in repair spend and onshore production is exactly what the full narrative for Snap-on digs into, revealing where Snap-on’s cash engine could be quietly accelerating.
A. O. Smith (AOS)
A. O. Smith fits the High-Quality Dividend Stocks theme because its essential water heaters and boilers generate recurring replacement demand, which can support steady cash flows and a consistent income stream for shareholders through different interest rate and inflation cycles.
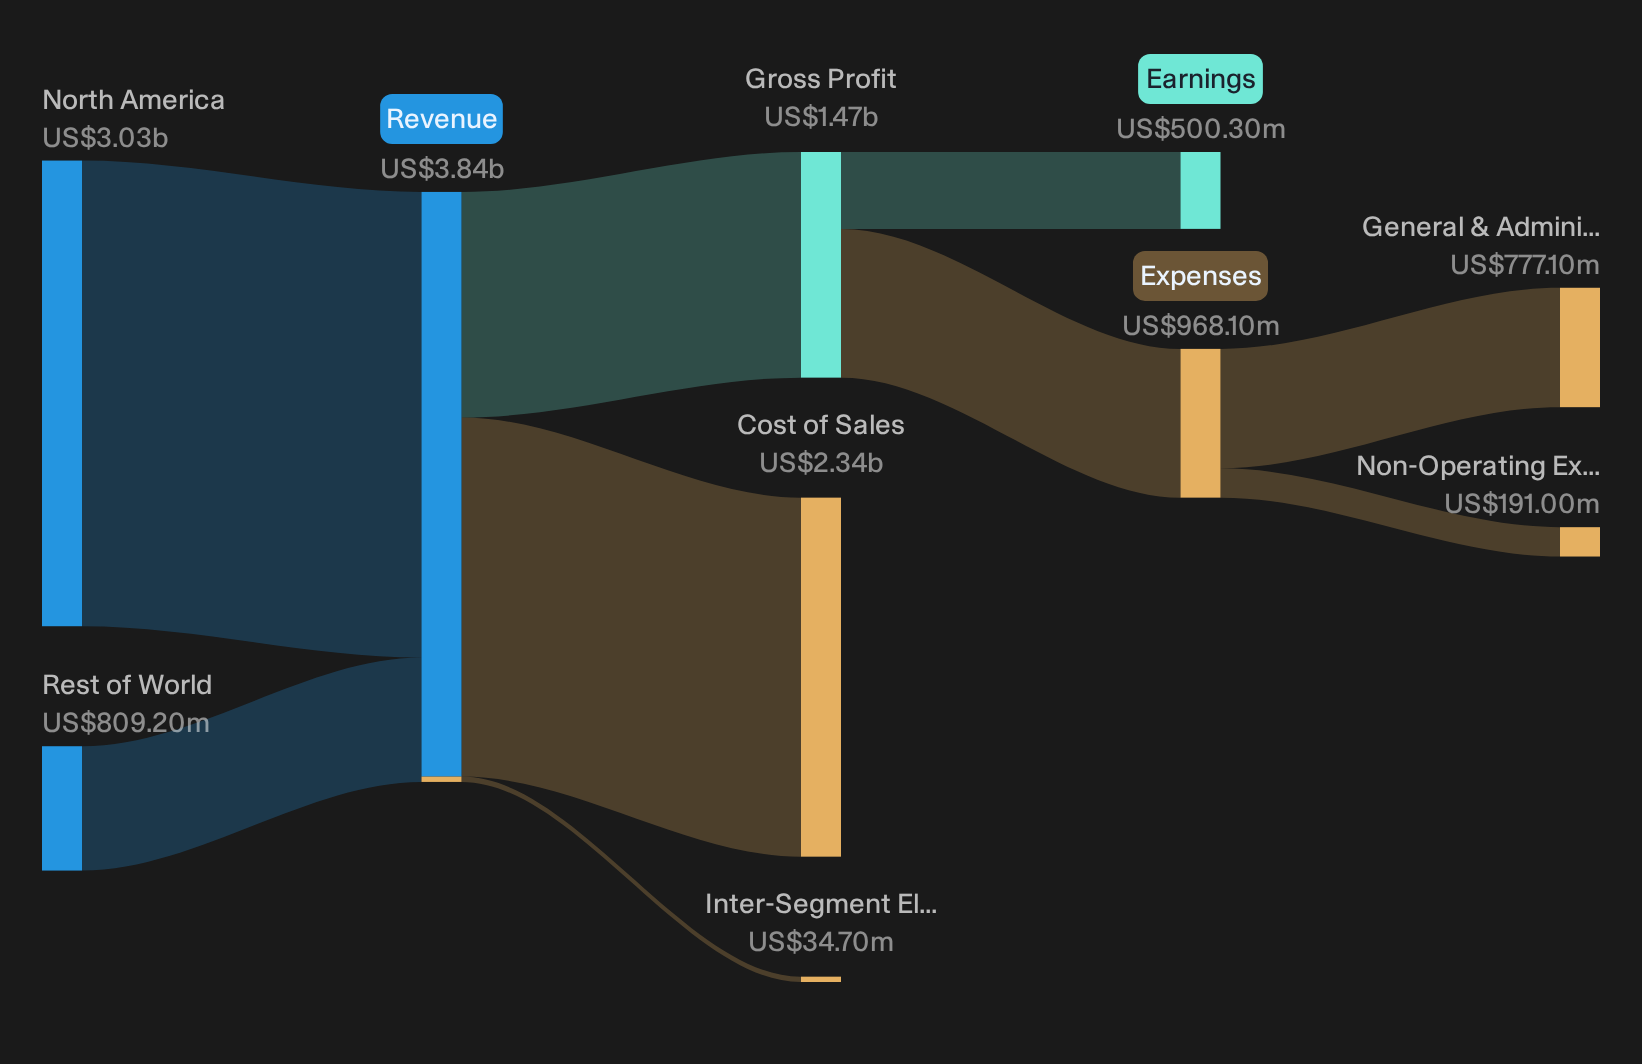
A. O. Smith sells residential and commercial water heaters, boilers, heat pumps and water treatment gear across North America, China, Europe and India, with about US$3.0b of revenue from North America and US$800 million from the Rest of World, and a market value near US$7.7b.
For dividend-focused investors, A. O. Smith offers a mix of essential equipment, recurring replacement cycles and a 2.53% yield that aligns with the screener’s emphasis on cash-generative industrials that can keep paying shareholders even when higher rates are pressuring more cyclical parts of the market.
"Increasing regulatory focus on energy efficiency and sustainability in water heating is prompting A. O. Smith to accelerate investment and launch new high-efficiency and smart products (for example, condensing boilers, tankless water heaters, IoT-connected filtration systems). This strategic product mix shift is expected to grow revenue and expand gross margins over time."
What could matter most for A. O. Smith’s dividend story now is how one less visible cost pressure interacts with that higher efficiency push to shape future margins.
That margin tug of war is exactly what the full narrative for A. O. Smith unpacks, showing where A. O. Smith’s efficiency push could be masking stronger long term cash momentum.
Seeking Fresh Alternatives Before They Fly
Markets move fast and the next breakout list does not stay under the radar for long. Scan fresh momentum pockets before the crowd catches on and act now.
- Spot income workhorses with strong cash support by running the 6 dividend fortresses while yields are still competing with higher rates and before attention fully swings back to growth.
- Track real-economy projects that may benefit from grid upgrades by scanning the 38 power grid technology and infrastructure stocks while these ideas are still quietly building momentum.
- Position ahead of the next metals upcycle by reviewing the curated 36 elite gold producer stocks before more investors start chasing the same producers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com