
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Colgate-Palmolive (CL) Could Be 31% Undervalued As Dividend Confidence Meets North America Fix
Colgate-Palmolive (CL) just reaffirmed its quarterly cash dividend at $0.53 per share, extending a dividend streak that dates back to 1895, as management works to revive a softer North America business.
The share price reaction has been muted around the dividend news, with Colgate-Palmolive slipping 0.3% over the last session and easing 3.7% over 30 days. The stock has still posted a 12.6% year to date share price gain and a 10.5% 1 year total shareholder return, which suggests momentum has cooled recently, while longer term holders have still seen meaningful returns supported by that long-running dividend stream.
Capitalize on Colgate-Palmolive’s renewed dividend focus by scanning a curated group of resilient income ideas through our 6 dividend fortresses for investors who care about consistency as much as upside.Bulls see Colgate-Palmolive’s dividend record and steady 1 year return as proof the recent wobble is a buying opportunity. Bears point to softer North America and question the price. Which side does the valuation support?
Most Popular Narrative: 1% Overvalued
On the most followed narrative, Colgate-Palmolive screens with a fair value of $86.48 against a last close of $87.47, which points to a very small premium that hinges on how you treat one large accounting hit.
The distortion runs through every derived metric. The dividend payout looks stretched at roughly 82% of GAAP EPS and is about 57% of Base Business EPS. The stock looks expensive at 35 times GAAP earnings and trades near 24 times normalised. The trailing twelve month margin carries the same contamination, because the fourth quarter of 2025 still sits inside the window.
See why 9 investors see Colgate-Palmolive as 1% overvalued.
According to rcb9, the key swing factor is whether you treat that goodwill impairment as a one off hit and focus on Base Business earnings and cash flow, or rely on GAAP figures that compress margins and inflate payout and P/E screens.
On that normalised lens the story shifts from a headline 9.7% net margin influenced by a large charge to a margin profile closer to 14% to 15%, with the narrative fair value built on 4% revenue growth, a 15% margin, a future P/E of 24x and a 7% discount rate.
That framework presents Colgate-Palmolive as a slow compounder where valuation is sensitive to small changes in growth, margin and exit multiple assumptions rather than big swings in the underlying operations.
Result: Fair Value of $86.48 (OVERVALUED)
Still, the thesis wobbles if North America stays weak or if another impairment in skin health signals deeper problems at Colgate-Palmolive’s higher margin brands.
Find out about the key risks to this Colgate-Palmolive narrative.
Another View: Colgate-Palmolive Through The SWS DCF Lens
A different lens tells a very different story for Colgate-Palmolive. Our DCF model points to a future cash flow value of $128.20 per share, while the stock changes hands at $87.47. That suggests the shares trade at a sizeable discount instead of a slim premium. The key question is which framework you trust more when earnings are distorted by large one off items.
Look into how the SWS DCF model arrives at its fair value.
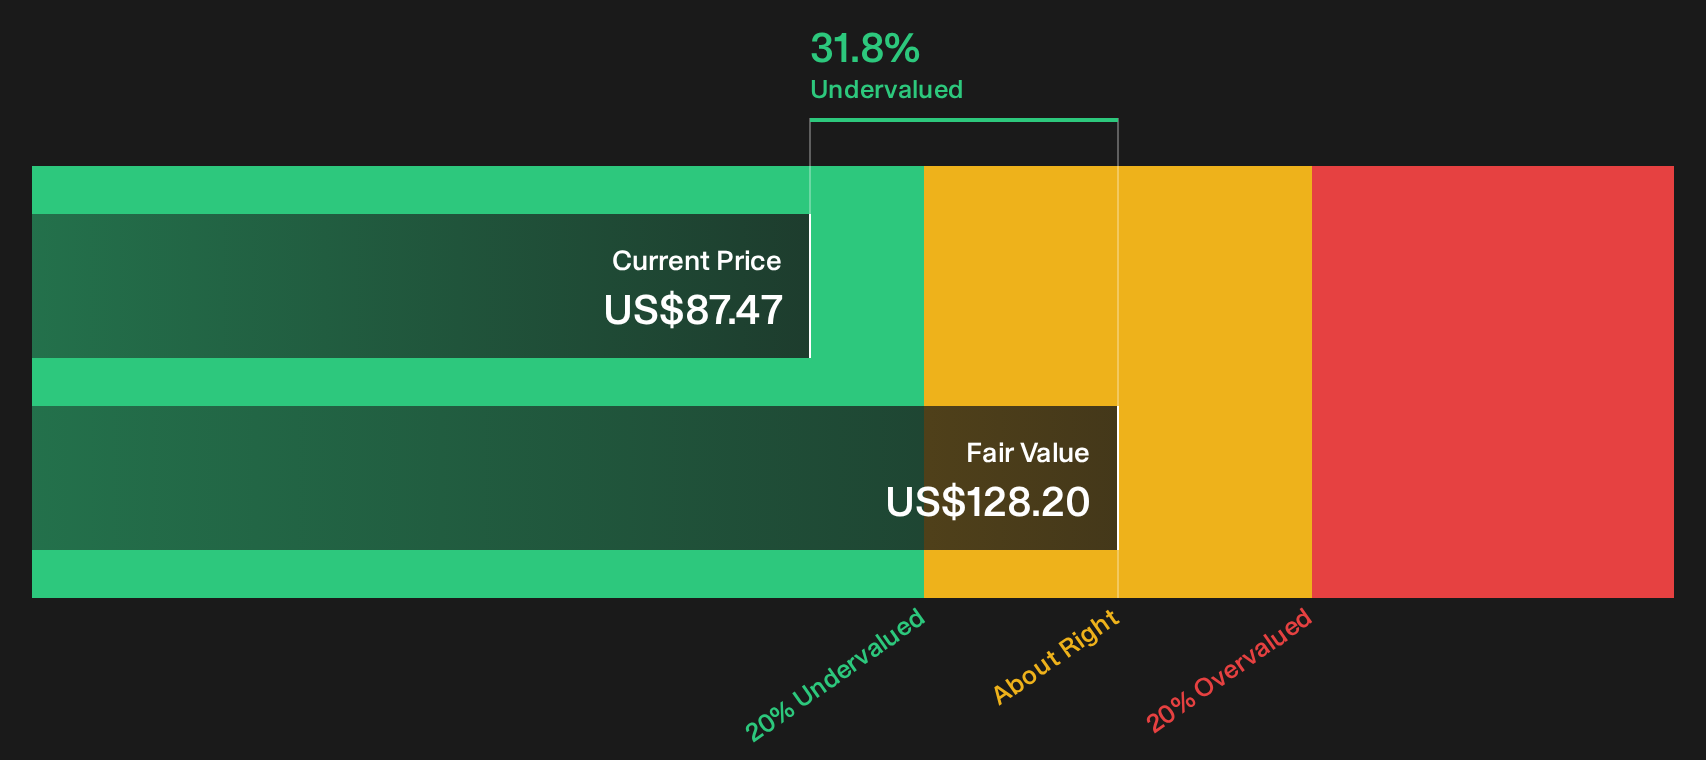
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Colgate-Palmolive for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Colgate-Palmolive can easily push you to one side or the other, so move quickly, pull up the full data set, and pressure test what matters most to you. To see both the concerns and the bright spots investors are focused on, start with our 3 key rewards and 3 important warning signs.
Looking For More Ideas Beyond Colgate-Palmolive?
Do not stop at Colgate-Palmolive. Round out your watchlist with a mix of income, value, and resilience so you are not relying on a single story.
- Target steadier income streams by reviewing a curated set of payout heavyweights through our 6 dividend fortresses.
- Hunt for price dislocations by scanning companies that look mispriced on quality and valuation using the 33 high quality undervalued stocks.
- Strengthen your downside protection by filtering for sturdier balance sheets and fundamentals via the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com