
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Put Option Volatility At F&G Annuities & Life Stock Has Changed Its Investment Story
- F&G Annuities & Life participated in the Barclays 24th Annual Global Financial Services Conference in New York, where CEO Conor Ernan Murphy and CFO Michael Bailey outlined the insurer's current positioning in annuities and life products.
- Options traders recently priced unusually high implied volatility into the October 16, 2026 $12.50 put. This points to heightened focus on F&G Annuities & Life's earnings resilience and product mix after earlier analyst estimate cuts.
- We will now look at how F&G Annuities & Life's investment narrative could be affected by this spike in options implied volatility.
Stress test your view on F&G Annuities & Life by comparing it with insurers facing similar options-market pressure, using our hand picked 30 resilient stocks with low risk scores as a starting point.
F&G Annuities & Life Investment Narrative Recap
To own F&G Annuities & Life, you need to believe the business can keep growing earnings in annuities and life products while managing pressure on revenue, margins and capital. The options market spike and cautious sentiment highlight how quickly confidence can shift around its product mix and interest rate exposure.
The key short term catalyst is execution in higher return areas like fixed indexed annuities, RILA and pension risk transfer, especially as MYGA sales and ROA compression are already in focus. The biggest risk is that competitive pricing, alternative asset volatility and large PRT or reinsurance exposures hit profitability at the same time.
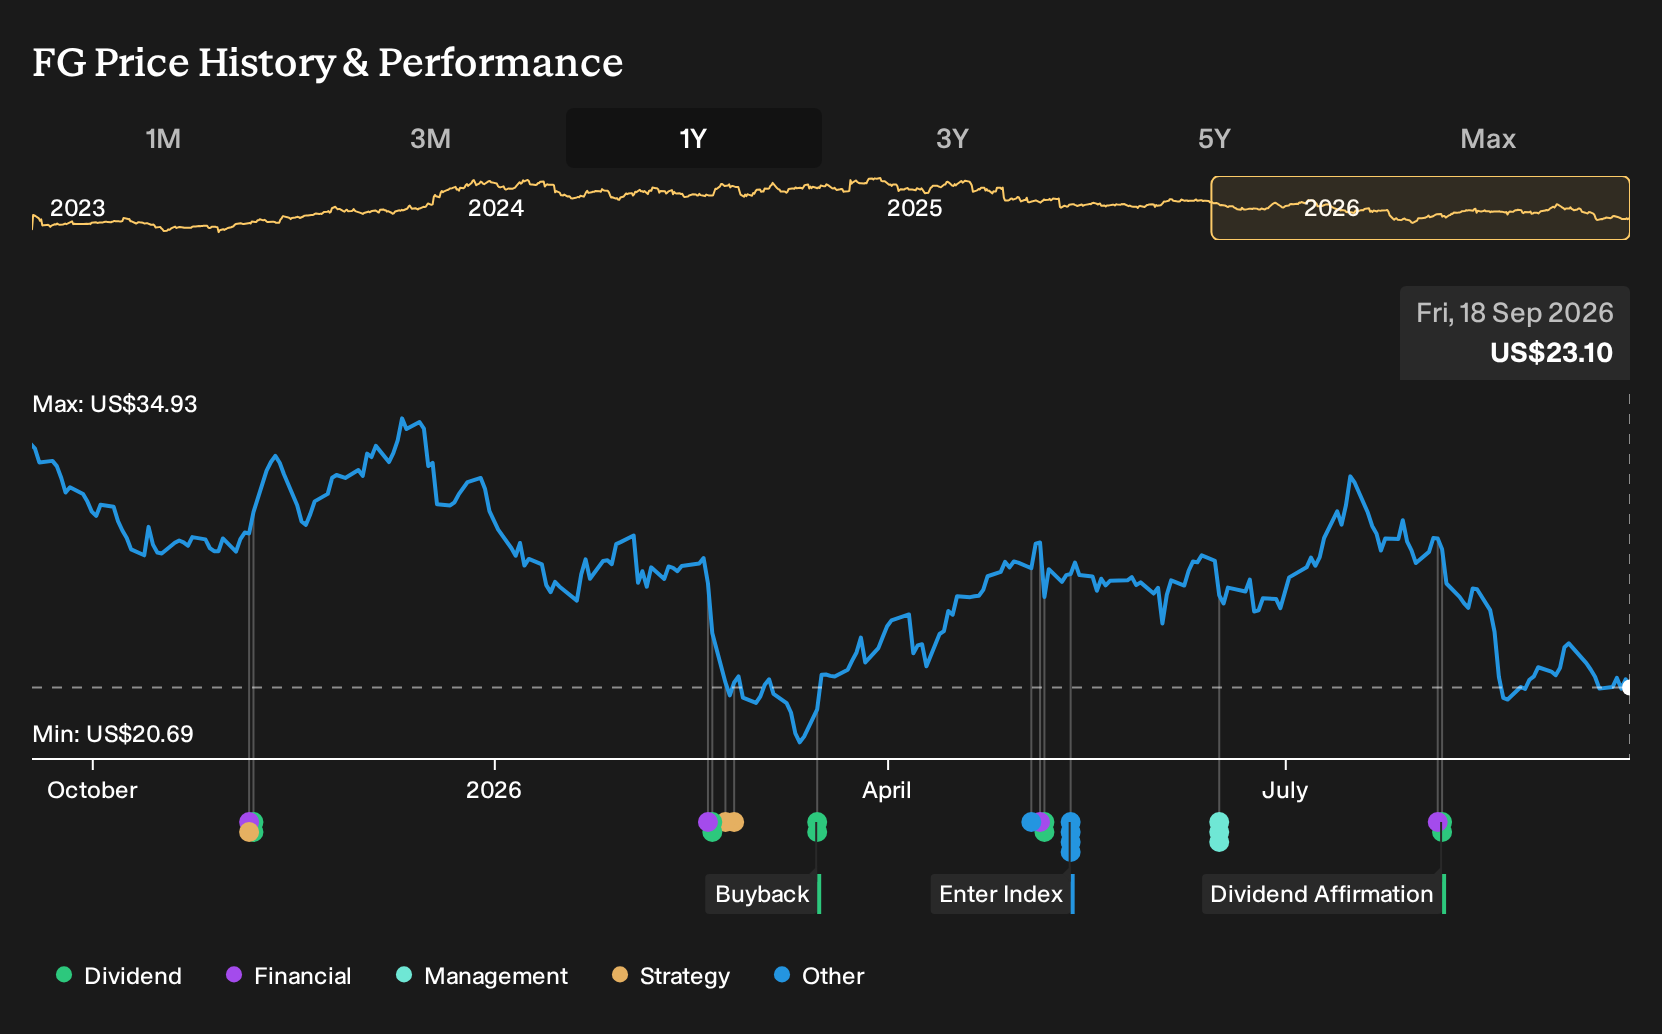
The Barclays conference appearance on 14 September 2026 is the most relevant event here. F&G Annuities & Life put CEO Conor Ernan Murphy and CFO Michael Bailey in front of institutional investors just as options traders priced in elevated implied volatility on the October 2026 $12.50 put.
That forum allows management to discuss how RILA rollout, pension risk transfer volumes, investment portfolio repositioning and capital allocation compare with execution risks and softer revenue expectations. For you, the value is whether their message convinces the market that earnings quality, funding structure and legal exposures are being managed tightly enough to support the current thesis.
What The Current F&G Annuities & Life Forecasts Assume
F&G Annuities & Life's consensus outlook ties the current options volatility back to a fairly specific earnings and revenue path. Analysts are working off an assumption that revenue declines 22.1% each year over the next three years, while profitability shifts higher as margins move from 8.6% today to 20.9% in three years. On that view, earnings sit at $517.0 million today and are projected to reach $595.5 million by 2029, which is an increase of about $78.5 million in profit. The same models anchor on a forecast for 2029 revenue of $2.8b and use that $595.5 million earnings line with a P/E of 7.1x to justify current valuation targets.
F&G Annuities & Life's narrative projects $2.8b revenue and $595.5 million earnings by 2029. This implies a 22.1% yearly revenue decline and an earnings increase of about $78.5 million from $517.0 million today.
These figures also assume that the share count shrinks by 1.61% a year over the next three years. This matters for how you think about earnings per share rather than just the total profit pool. A smaller share base means each remaining share is tied to a slightly bigger slice of those forecast 2029 earnings, even if the headline revenue line is moving lower. For an options trader trying to price that October 2026 put, the key question is whether this trade off of falling top line, higher margins and lower share count lines up with your own view of product demand and capital deployment.
Uncover how F&G Annuities & Life's fair value indicates a 17% potential upside to its current price, before the market moves to close the discount.
Exploring Other Perspectives
The Simply Wall St Community offers only two fair value estimates for F&G Annuities & Life, clustered between $27 and about $33, so even this small sample shows a wide range. You then have options pricing, a Zacks Rank #5 and recent estimate cuts pointing to caution. Treat these as competing lenses and explore several alternative viewpoints before firming up your own stance.
Explore another F&G Annuities & Life fair value estimate, including an estimate that indicates as much as 43% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your F&G Annuities & Life research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for F&G Annuities & Life. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate F&G Annuities & Life's overall financial health at a glance.
Looking for more investment ideas beyond F&G Annuities & Life?
Once you have a view on F&G Annuities & Life, it often helps to cross check that thesis against other opportunities with different risk, income and quality profiles. The Simply Wall St Screener can surface stocks that fit very specific criteria so you are not just relying on one insurer to express your outlook.
- If you want potential mispricing with quality fundamentals, start with a focused list of 33 high quality undervalued stocks and see how they compare with F&G Annuities & Life on earnings power and balance sheet strength.
- For investors who care most about resilience, you can stress test your risk tolerance by scanning a 30 resilient stocks with low risk scores and then weighing those options against the volatility now priced into F&G Annuities & Life.
- Income focused investors can contrast F&G Annuities & Life with a curated set of 6 dividend fortresses to judge whether the trade off between yield, payout consistency and business quality still feels reasonable.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com