
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did AI Revenue Growth Just Shift Amphenol (APH) Stock's Investment Narrative?
- Amphenol recently presented at Citi’s 2026 Global TMT Conference in New York, outlining how its connectors, cables, sensors, and CommScope acquisition fit into fast growing IT datacom and AI infrastructure demand.
- The standout detail is the roughly $10.5 to $11 billion AI revenue run rate, with AI related sales expanding faster than Amphenol’s broader IT datacom business.
- We will now explore how this AI driven IT datacom momentum could reshape Amphenol’s investment narrative for long term oriented investors.
Amphenol Investment Narrative Recap
Owning Amphenol means believing its position in high speed interconnects keeps it central to AI heavy IT datacom spending, while its broad end market mix helps smooth out some of the tech cycle swings. The Citi conference update on roughly US$10.5b to US$11b in AI related revenue run rate reinforces that this part of the franchise is already large.
The near term swing factor remains how “pulled forward” AI datacenter demand behaves over the next few quarters versus capacity and capex that Amphenol has lined up. The biggest risk is that lumpy customer budgets or slower orders hit volumes just as elevated investment, acquisition related integration costs, and higher debt levels keep pressure on cash generation.
The Citi 2026 Global TMT appearance sits alongside management’s recent commentary that IT datacom and AI demand is supporting updated sales expectations for the CommScope acquisition. That combination links the conference remarks directly to a concrete operational lever, namely using CommScope’s fiber assets to deepen Amphenol’s presence in data centric infrastructure.
Execution on that integration is now a key catalyst. Investors are watching whether the enlarged fiber and optical portfolio turns the current AI revenue run rate into more durable orders while still protecting margins and free cash flow. Any stumble on synergies, or a sharper than expected pause in AI data center projects, would quickly test that thesis.
Amphenol’s current analyst model points to revenues of US$50.7b and earnings of US$10.8b by 2029, based on an assumed 20.5% yearly increase in revenue and an earnings step up of about US$5.7b from US$5.1b today.
Uncover why Amphenol's fair value indicates a 28% potential upside to its current price that could narrow quickly.
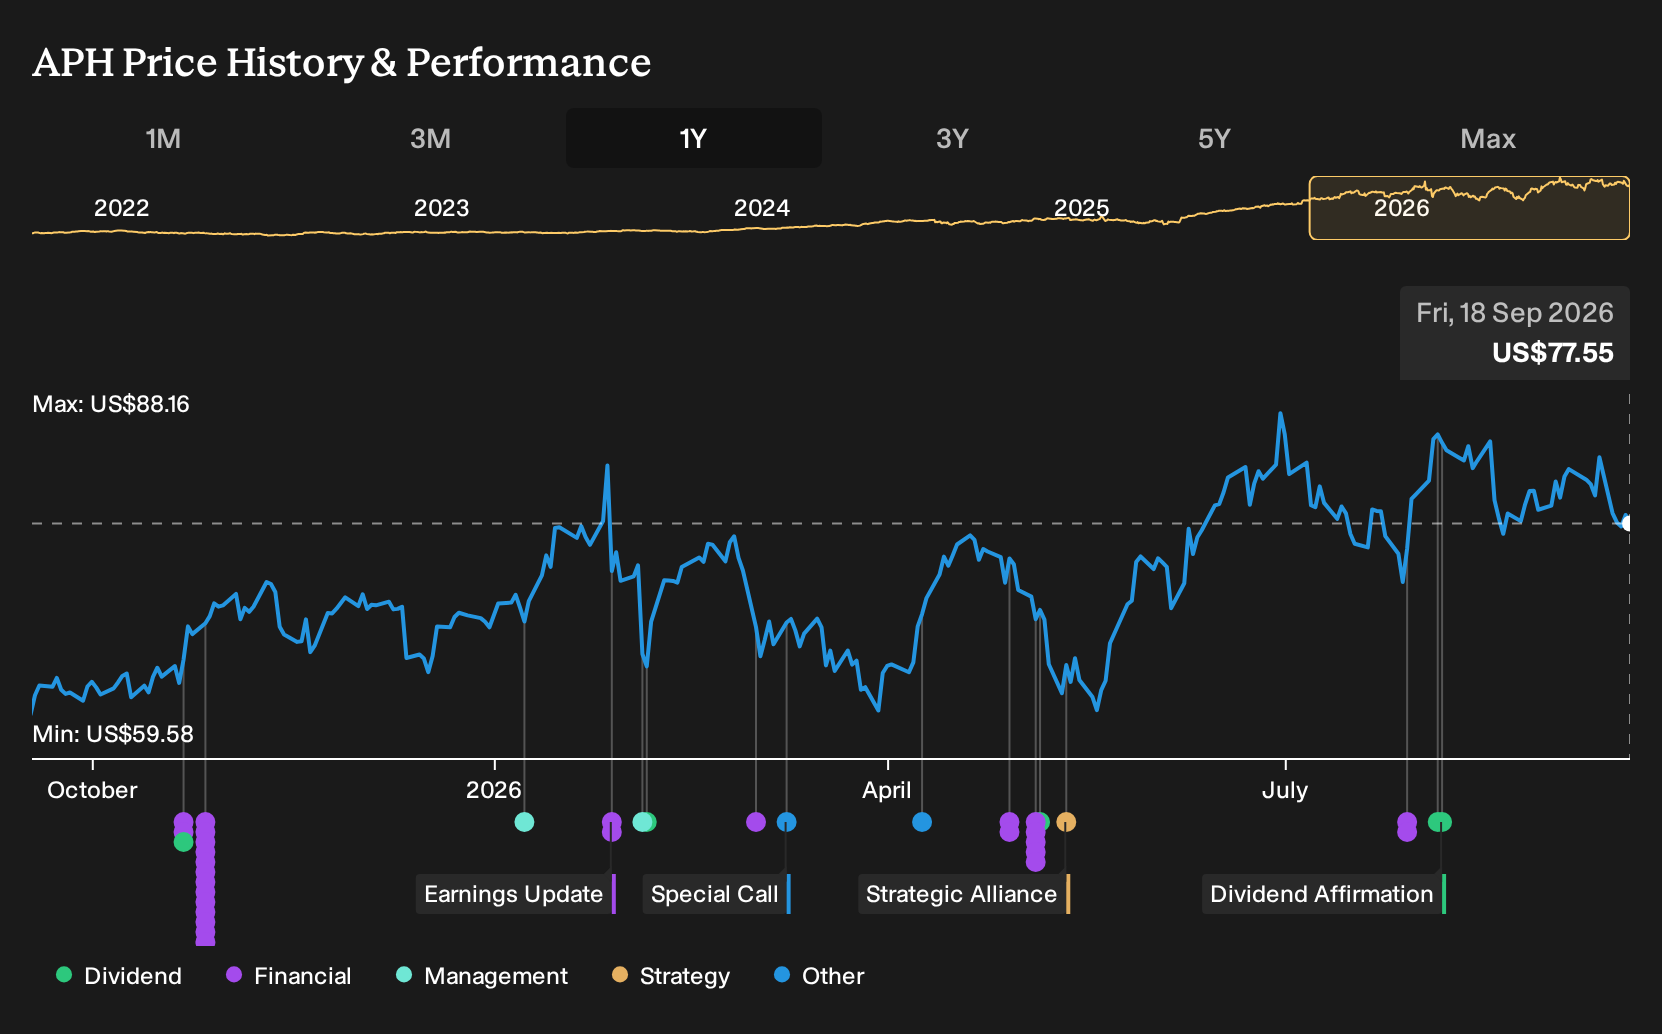
Exploring Other Perspectives
One alternative view on Amphenol leans heavily on margin pressure. The most cautious analysts were penciling in only about 15.1% annual revenue growth and earnings of roughly US$7.2b by 2029 before this conference, far below the consensus path. That gap shows how widely opinions can differ, so explore several viewpoints before deciding what this new AI update might mean.
Explore 6 other Amphenol fair value estimates, including one that suggests it could be worth just $87.55.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Amphenol research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Amphenol. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amphenol's overall financial health at a glance.
Looking For More Investment Ideas Beyond Amphenol?
If the Amphenol story has you thinking more broadly about where to put fresh capital to work, it can help to scan a wider field of opportunities that match your preferred mix of risk, return potential, and balance sheet strength.
- If you want potential upside with tighter risk controls, you can filter for companies flagged as 30 resilient stocks with low risk scores that might better suit a steadier approach.
- Income focused investors can zero in on businesses with stronger cash payouts by reviewing a curated set of 6 dividend fortresses that meet your yield and stability preferences.
- For those hunting for less crowded opportunities, consider casting a wider net across 16 high quality undiscovered gems that combine robust fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com