
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Plains All American Pipeline (PAA) Following Fresh Financing And A Basin Deal Looks Fairly Valued
Plains All American Pipeline (PAA) recently raised fresh long-term capital through fixed-to-floating rate notes maturing in 2056, while also agreeing to buy Silver Creek Midstream’s crude oil assets in the Powder River Basin.
On the market side, Plains All American Pipeline’s share price has eased over the past week, with a 7 day share price return of 2.8% and a 1 day move that was slightly negative, even as the 90 day share price return of 18.88% and year to date gain of 39.32% point to strong upward momentum. That shorter term wobble comes after a period where total shareholder return has been much stronger. The 1 year total shareholder return is 61.36% and the 5 year total shareholder return is 271.43%. This suggests investors have been steadily repricing the stock, while recent funding and acquisition news adds fresh talking points around future risk and opportunity.
Scan other midstream and energy infrastructure plays that are showing similar funding and acquisition momentum using our curated list of 38 power grid technology and infrastructure stocks
PAA has already delivered very strong multi year gains and a fresh leg higher this year. The key question now is how much upside the current valuation still leaves on the table.
Most Popular Narrative: 0% Overvalued
On the latest narrative workup, Plains All American Pipeline screens as fairly valued, with a fair value of $25.31 sitting almost on top of the last close at $25.37. That tight gap puts the focus less on a big valuation mismatch and more on how the business mix and capital spending story evolve from here.
The divestiture of the Canadian NGL business and redeployment of approximately $3 billion in proceeds will allow Plains to focus on higher-growth and higher-return U.S. crude oil assets, supporting stable throughput and cash flow, which can drive revenue and long-term earnings growth. Strong strategic positioning in the Permian Basin and the ability to acquire further interests in key pipelines (such as BridgeTex), paired with ongoing population and economic growth in North America, provide a resilient volume foundation and upward revenue trajectory.
See why 31 investors see Plains All American Pipeline as 0% overvalued.
Result: Fair Value of $25.31 (ABOUT RIGHT)
Still, if Plains All American Pipeline struggles to redeploy divestment proceeds into high returning crude projects or faces weaker recontracting terms, that fair value narrative could crack.
Find out about the key risks to this Plains All American Pipeline narrative.
Another View on Plains All American Pipeline's Value
That fair value narrative for Plains All American Pipeline bumps up against a very different signal from the SWS DCF model. On this framework, PAA at $25.37 trades at roughly a 66% discount to an estimated future cash flow value of $74.47, which frames the unit price as heavily undervalued.
For readers who want to see how that cash flow driven result is built line by line, Look into how the SWS DCF model arrives at its fair value..
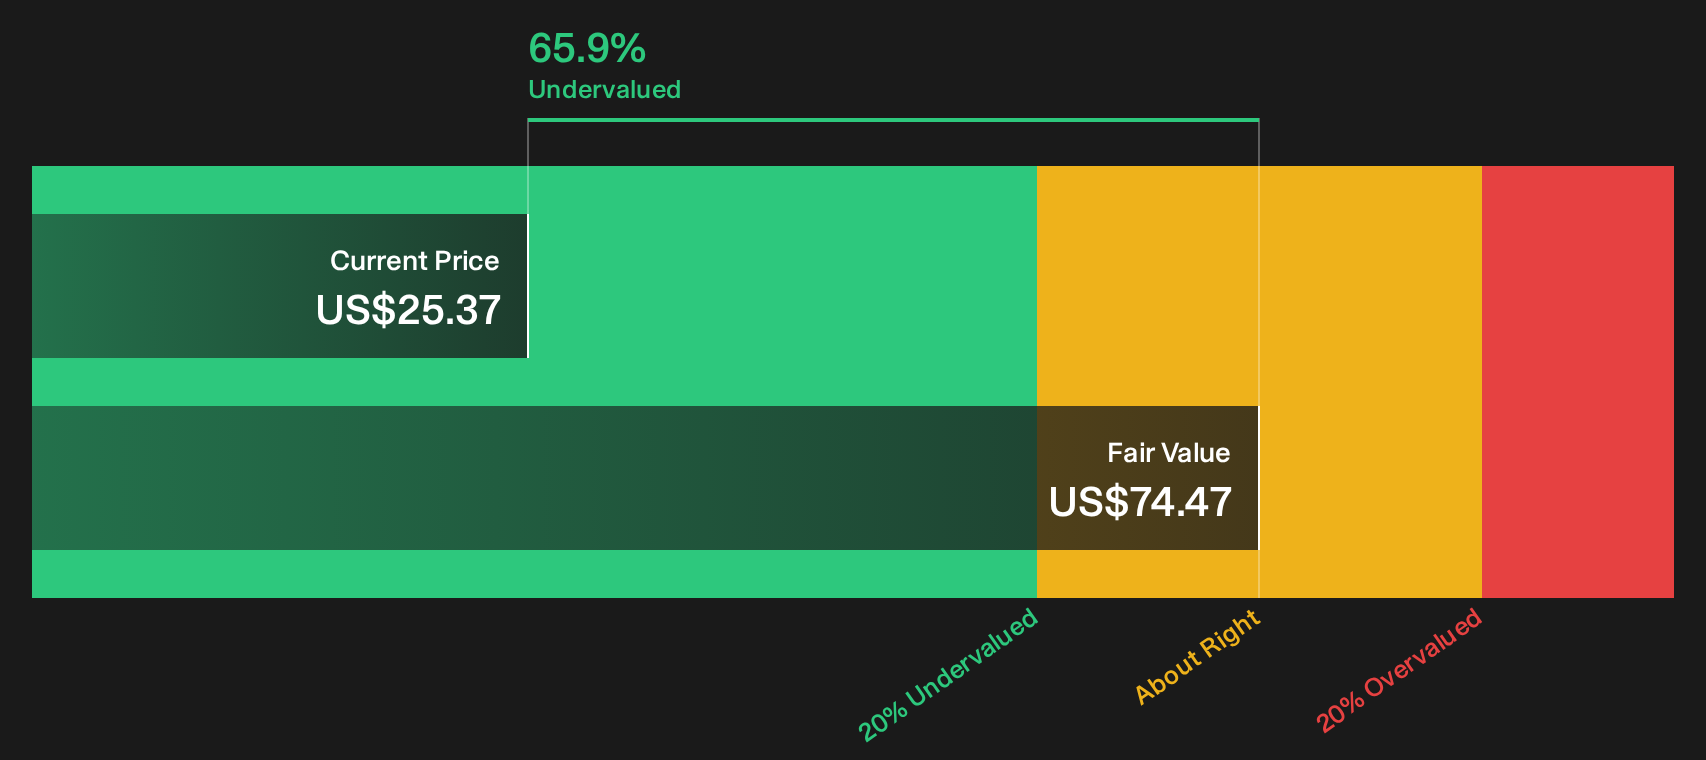
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Plains All American Pipeline for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Plains All American Pipeline is split, with clear positives and some pointed concerns. Move quickly, review the underlying data, and weigh both sides through 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Plains All American Pipeline?
If PAA has your attention, do not stop here. There are plenty of other stocks with different risk, income, and value profiles worth your time.
- Target higher income potential and stress test your yield expectations by reviewing our hand picked group of 6 dividend fortresses.
- Balance opportunity with resilience and focus on capital protection first by scanning a 30 resilient stocks with low risk scores tailored to steadier profiles.
- Hunt for quality that is not yet crowded by institutions by working through a curated set of 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com