
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Generator Orders Require Action From Cummins (CMI) Investors?
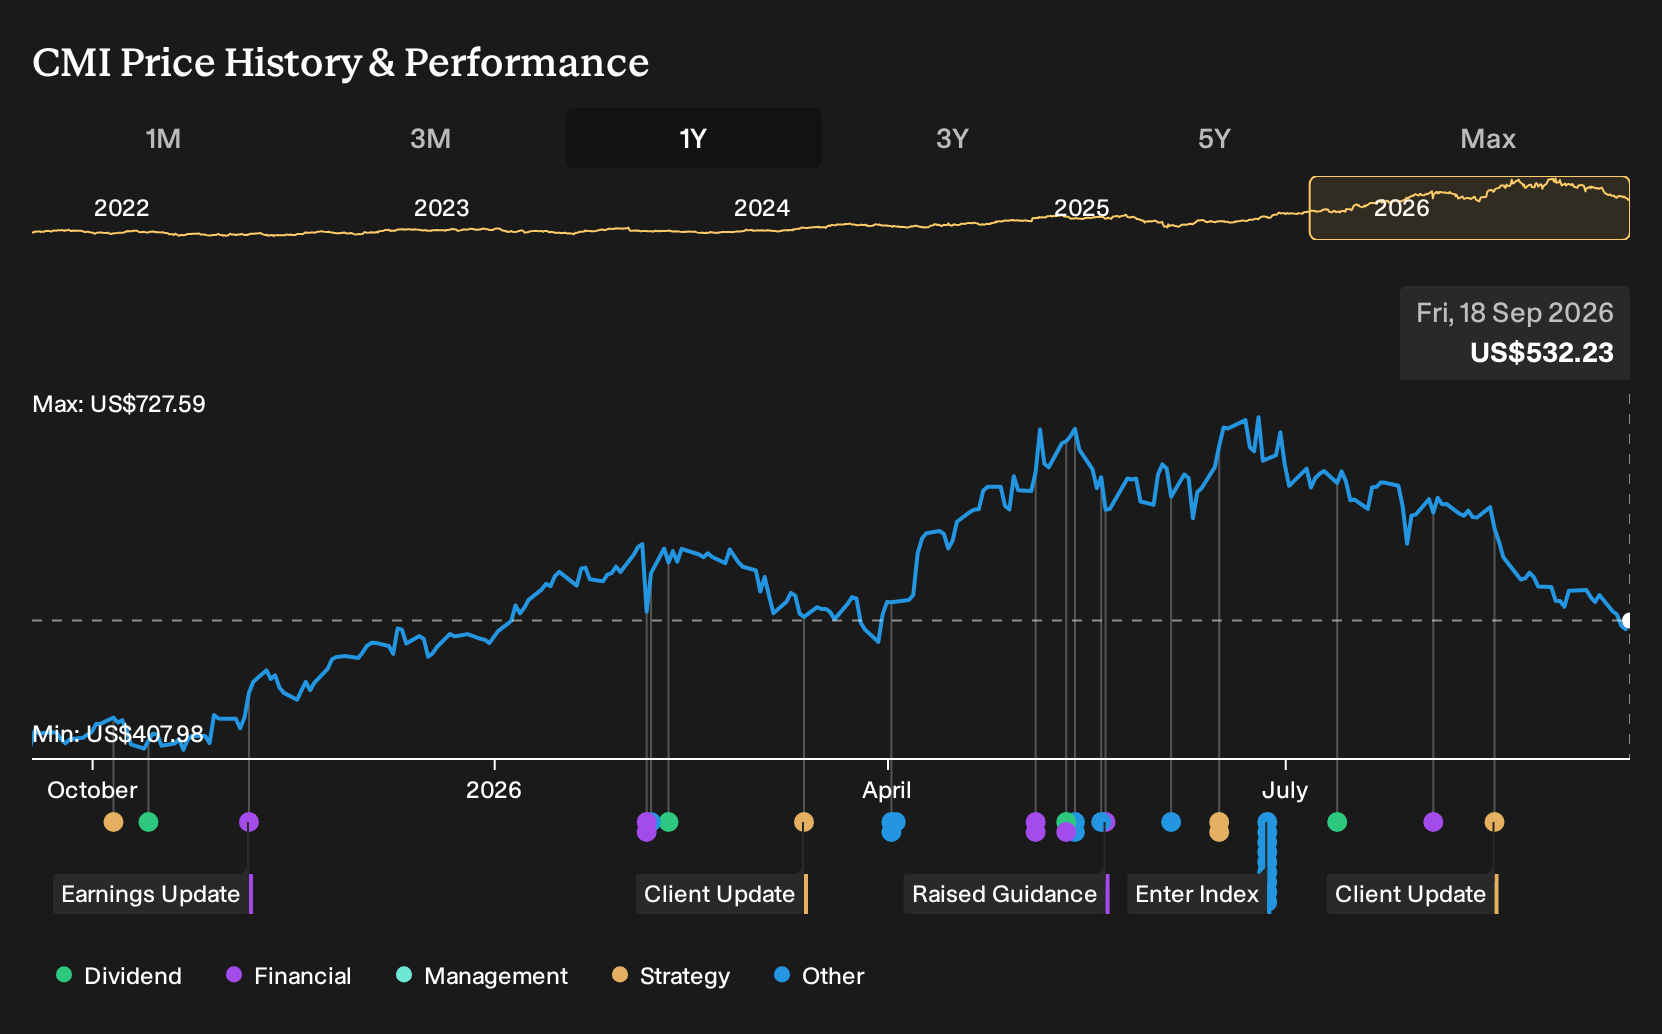
- Cummins presented at Morgan Stanley's 14th Annual Laguna Conference on 15 September 2026, outlining demand trends in North American trucking and data center power, along with capital allocation priorities.
- Management highlighted long QSK95 generator order visibility through the second half of 2028 and plans to expand data center power exposure and prime-power capacity while working to reduce losses in the Accelera business.
- We now examine how Cummins' investment narrative could shift as investors weigh extended QSK95 demand against its broader growth plans.
Scan beyond Cummins and its data center push by reviewing our hand-picked list of 89 AI infrastructure stocks that could benefit if power and compute demand remain in focus.
Cummins Investment Narrative Recap
To own Cummins, you need to be comfortable with a cyclical truck engine franchise that is increasingly tied to data center power and emissions technology. The recent conference appearance reinforced that picture. Management described solid demand in North American trucking and data center projects, with QSK95 generator orders stretching into the second half of 2028, which supports operational visibility.
In the short term, the key swing factor remains how North American heavy and medium duty truck orders evolve as fleets digest 2027 emissions rules. The largest near term risk is a deeper or longer slump in truck demand combined with ongoing losses in Accelera. The Laguna comments did not materially change that risk balance.
The detail that matters most from this event is Cummins confirming QSK95 generator orders out through late 2028 while targeting more than US$9b of data center exposure by 2030. This suggests that Power Systems and related services may carry more weight in the mix as traditional truck markets move through their cycle.
For investors, the operational question is whether the firm can execute on added prime power capacity, natural gas generation and battery storage while narrowing Accelera losses. Progress in these areas could help offset any pressure from weaker trucks or regulatory costs tied to EPA27 engines, and it ties directly into the medium term catalysts around backlog conversion and margin resilience.
Cummins' current analyst narrative points to revenues of US$44.2b and earnings of US$5.3b by 2029, implying 9.3% yearly top line growth and an earnings increase of about US$2.6b from US$2.7b today.
Uncover why Cummins' fair value indicates a 41% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The optimistic analysts look at Cummins' data center push and focus on a different catalyst. They lean into the HELM engine platforms and battery joint venture, backing revenue of about US$49.7b and earnings near US$6.2b by 2029. That is far above consensus, and these views may shift as the Laguna updates sink in.
Explore 3 other Cummins fair value estimates, including one that suggests as much as 69% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cummins research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Cummins. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cummins' overall financial health at a glance.
Looking For More Ideas Beyond Cummins?
If Cummins has sharpened your focus on where capital could work harder, the next step is to widen the lens and compare it with other opportunities that fit your risk and income preferences.
- If you want potential mispricing with quality fundamentals, scan our 33 high quality undervalued stocks and see which companies line up with your return and risk expectations.
- For investors who care most about resilience, focus on the 30 resilient stocks with low risk scores that can help anchor a more defensive part of your portfolio.
- When income reliability matters, use the 6 dividend fortresses to find candidates that might complement Cummins in a yield focused strategy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com