
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Japanese Bank Stocks That Could Benefit From Gradual BOJ Rate Hikes
Japan’s inflation surprise and the prospect of gradual Bank of Japan rate hikes have pushed interest rate expectations back into the spotlight, and the stocks most exposed to that shift are suddenly front of mind. Investors who ignore this turn in policy risk missing where the market quietly re-prices earnings power. This article breaks down three Japanese banks and financials from our screener, showing how each might respond to this new rate path.
The three examples below are only a starting sample, and the full screen surfaced 12 more Japanese banks and financials with equally compelling narratives that are not covered here. To identify and analyze the highest conviction rate beneficiaries directly, head straight into the Japanese Banks and Financials Benefiting from Gradual BOJ Rate Hikes screener.
Hirogin Holdings (TSE:7337)
Hirogin Holdings is the holding company for Hiroshima Bank, a traditional lender that fits the rate-beneficiary theme. Its banking unit generates about ¥183.1b in revenue, leasing contributes roughly ¥23.4b, and other services add ¥40.6b, on a market value of roughly ¥712.5b.
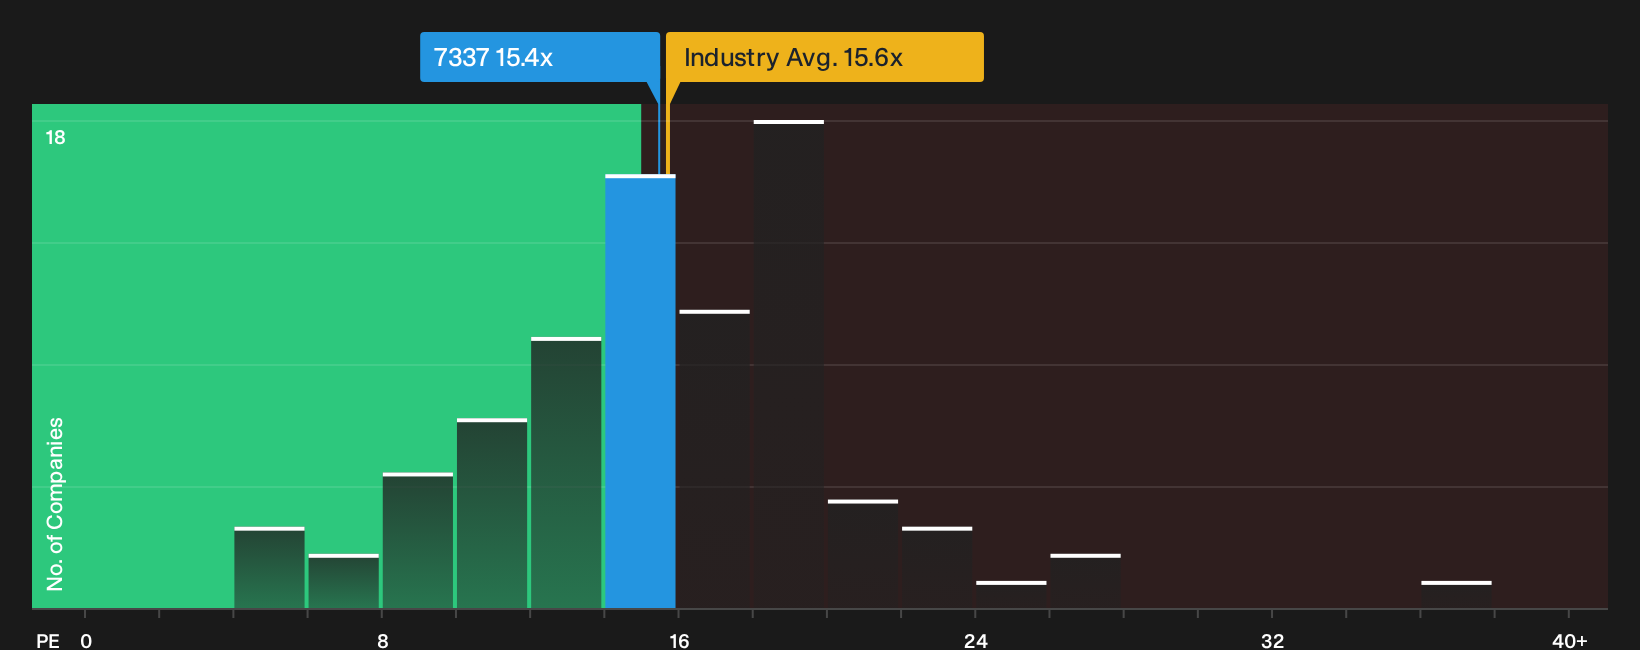
Hirogin Holdings is closely linked to the gradual BOJ rate story because its core Hiroshima Bank franchise depends on plain-vanilla lending in Japan, where higher policy rates can widen interest spreads. A P/E below domestic bank peers and existing earnings growth forecasts may influence how investor sentiment develops depending on how one unseen pressure plays out.
That unseen pressure deserves a closer look through the 4 key rewards and 2 important warning signs to see how Hirogin Holdings’ rate upside compares with the potential drag.
Chugin Financial GroupInc (TSE:5832)
Chugin Financial GroupInc is a regional Japanese banking group whose lending and deposit franchise is closely tied to domestic interest rates as BOJ policy slowly normalizes. With a market value of about ¥649.5b it sits firmly in the mid sized bank bracket.
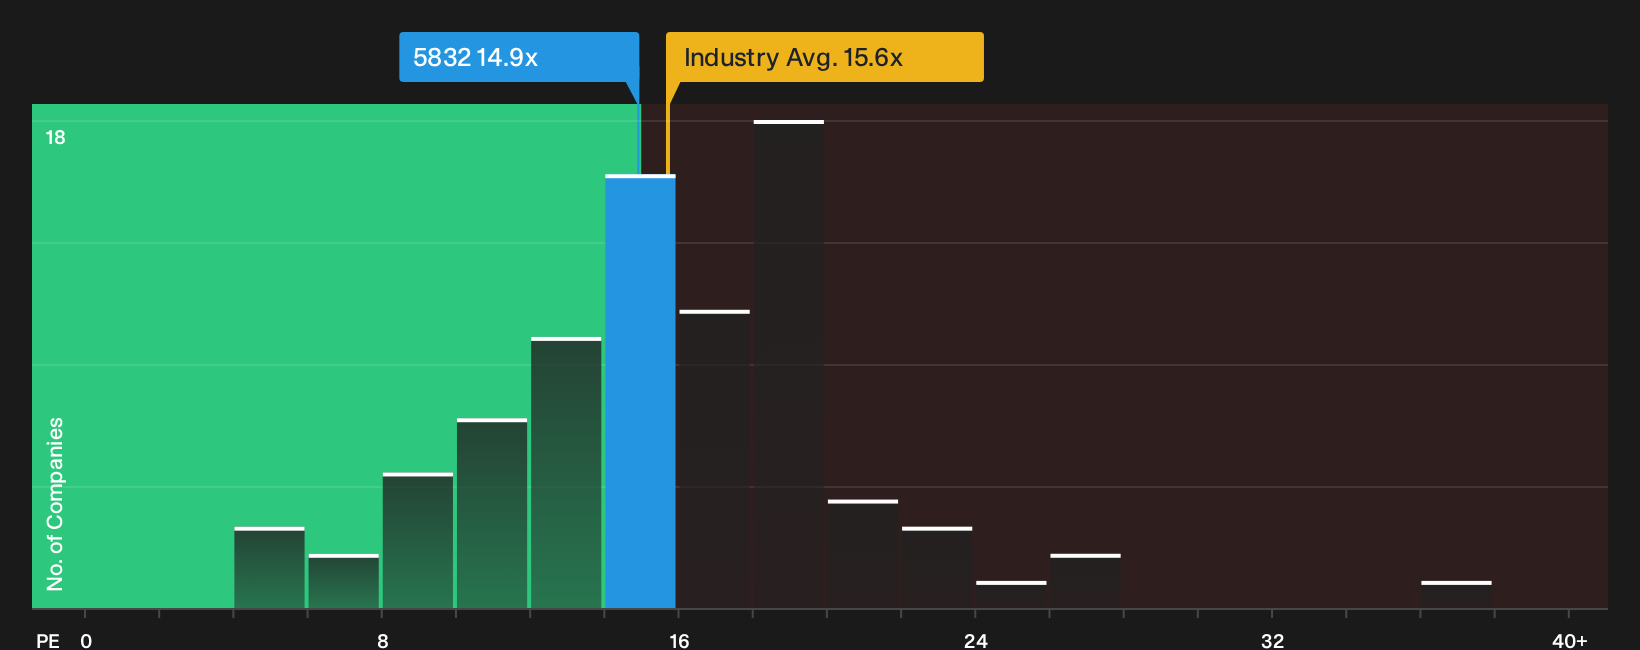
Chugin Financial GroupInc lines up closely with the rate theme, with a regional loan and deposit book that is sensitive to BOJ moves, a P/E of 14.9x that sits just under the broader banks group, and double digit earnings forecasts that leave plenty hinging on what happens when funding costs and credit reserves start to shift.
That leaves the real question hanging over where that earnings path and valuation might meet, so step into the 5 key rewards and 1 important warning sign to explore what could be driving the next rerating.
Okinawa Financial Group (TSE:7350)
Okinawa Financial Group is a ¥170b Japanese financial holding company that fits the BOJ rate normalization theme through its mix of traditional banking and fee businesses. Banking generates about ¥55.5b in revenue, leasing adds roughly ¥12.7b, with smaller contributions from other services.
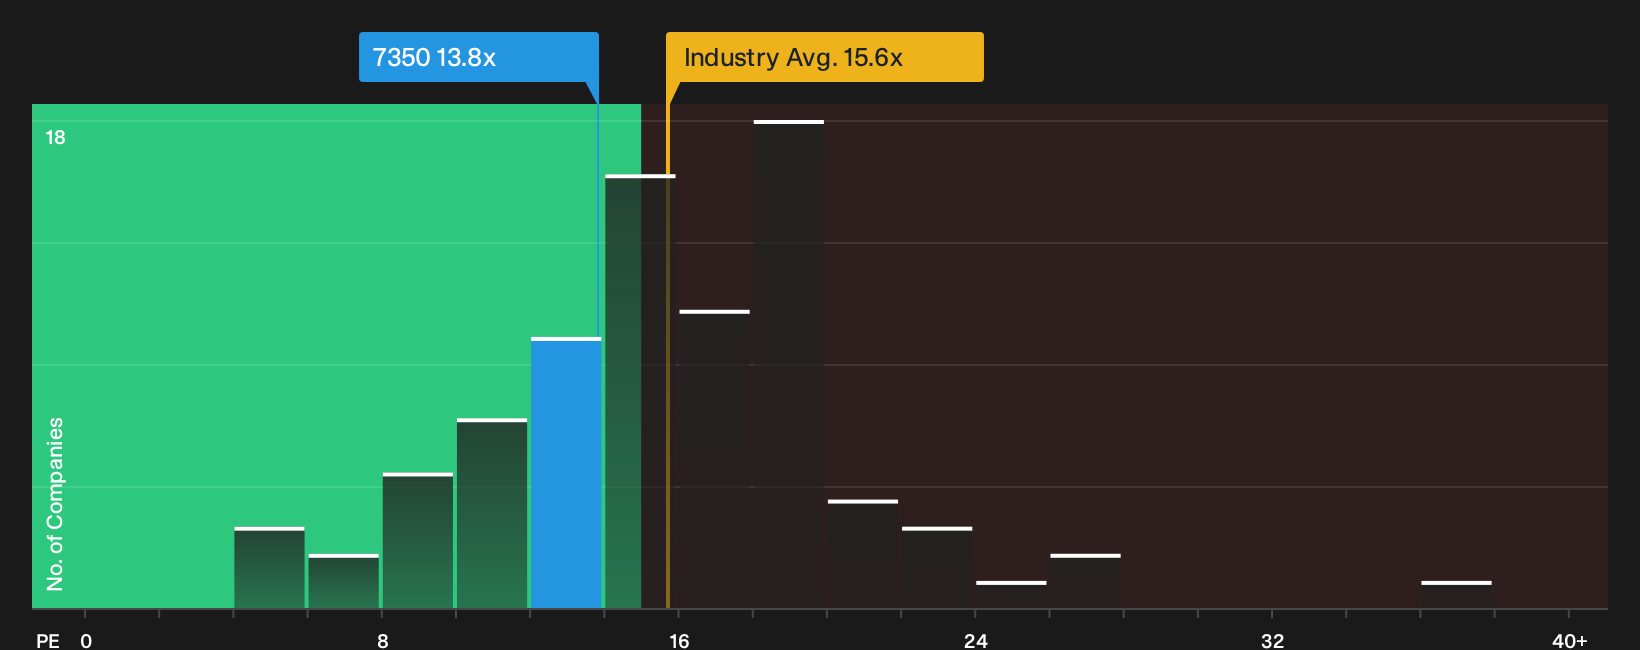
Okinawa Financial Group ties into this rate focused screen through its domestic loan and deposit engine, a P/E of 13.8x below the Japan banks average of 15.8x, and revenue that is expected to grow around 9% a year. Improving net margin at 18.8% and a 2.51% dividend yield put more weight on what happens when one unseen pressure shifts in the background.
That shifting pressure is exactly where the 5 key rewards and 1 important warning sign could show whether Okinawa Financial Group’s earnings engine is quietly accelerating or masking a bigger swing.
Curious About Your Next Big Alternative?
Fresh ideas move first. Breakout themes, building momentum, and under the radar stocks can get caught once everyone notices. Scan what others miss while it matters and aim to act while opportunities are still emerging.
- Target cash generative businesses with strong balance sheets before attention floods in by running the list of solid balance sheet and fundamentals (20 results).
- Explore long term compounding income by checking out the 14 dividend fortresses that focuses on higher yielding companies designed to support ongoing payouts.
- Prepare for potential shifts in infrastructure spending by reviewing the curated 38 power grid technology and infrastructure stocks filtering for companies linked to grid upgrades and electrification.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com