
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Adidas (XTRA:ADS) Could Be 30% Undervalued On Its Fitness Growth Story
The field hockey equipment market is projected to reach $2.7b by 2035, and adidas (XTRA:ADS) features among the key global participants, drawing fresh attention to its broader sports gear and footwear business.
Recent trading tells a more cautious story. adidas shares trade at €142.25 and the 90 day share price return has fallen 18.67%, while the 1 year total shareholder return is down 19.2%. This points to fading momentum even as field hockey and wider sports demand continue to shape expectations for the business.
Scan beyond adidas and benchmark it against a curated group of sports and consumer brands in the 179 high quality undervalued stocks to see where the market might be underrating underlying fundamentals.
Bulls see adidas as a global sports brand trading at a discount, while bears point to the share price slide and fading momentum. Which side does the current valuation maths lean toward?
Most Popular Narrative: 30% Undervalued
On the most followed view, adidas is priced below an estimated fair value of €202.72, compared with the latest close at €142.25. This puts the focus squarely on how durable its earnings and brand strength really are.
The accelerating global health and fitness movement is driving strong demand for adidas' performance and athleisure product categories, as demonstrated by double-digit growth in key segments like Running (+25%), Training (+20%), and Basketball. This is positioning the company for sustained volume expansion and recurring sales growth (impacts revenue and earnings).
See why 90 investors see adidas as 30% undervalued.
Result: Fair Value of €202.72 (UNDERVALUED)
Still, higher import tariffs in key sourcing countries and a more promotional U.S. market could pressure adidas margins and challenge the 30% undervaluation story.
Find out about the key risks to this adidas narrative.
Another View: What adidas’ P/E Ratio Is Telling You
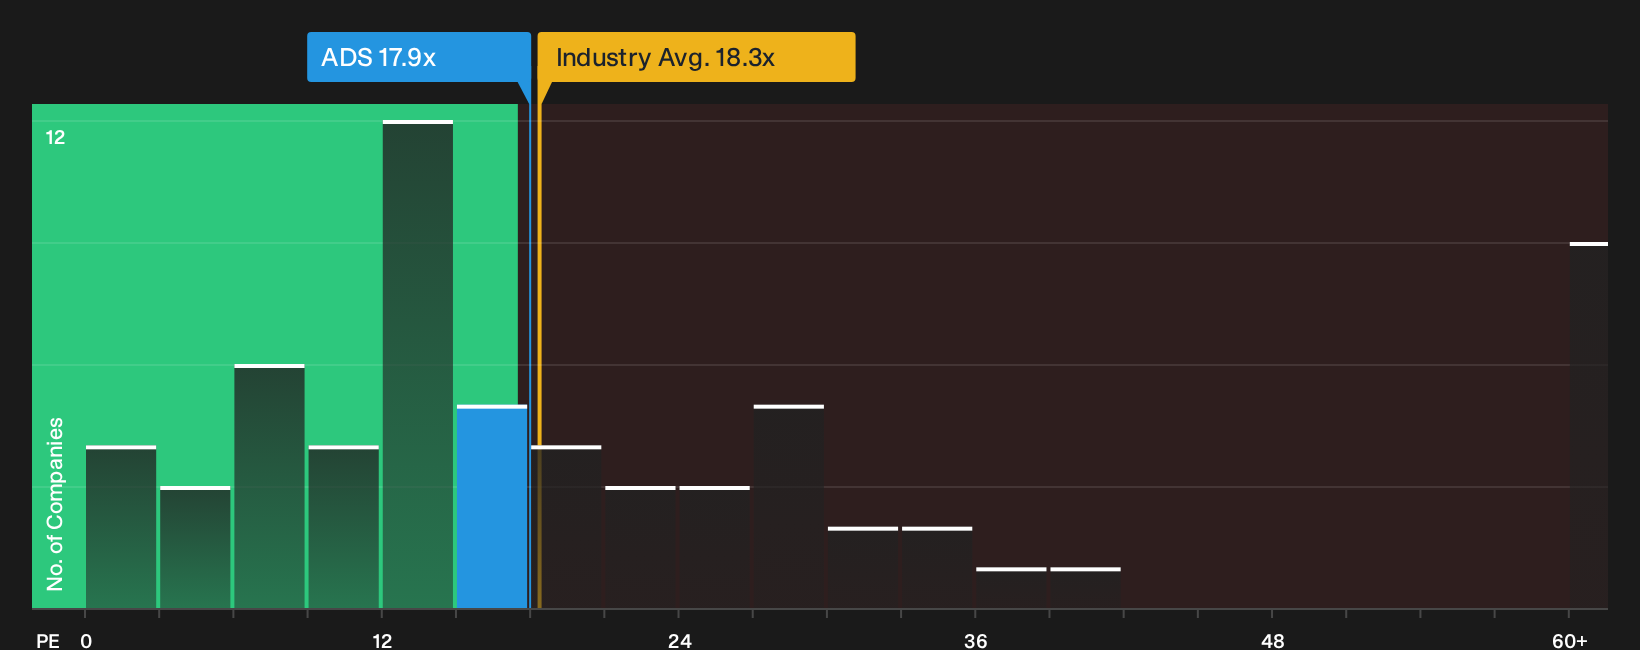
The story looks different when the adidas share price is lined up against earnings instead of fair value estimates. At a P/E of 17.9x, the stock trades above its own fair ratio of 13.8x and above peer averages of 12.5x, while only roughly in line with the wider European luxury group on 18.3x.
That mix points to a valuation that already bakes in a fair amount of optimism, even with recent share price weakness. This raises a simple question for investors weighing adidas today: Is the potential upside worth paying a richer multiple than both the fair ratio and closer peers suggest?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on adidas so far, right? Step in while sentiment is divided, review the numbers for yourself, then weigh up the 4 key rewards and 1 important warning sign.
Ready to act on your next move beyond adidas?
Do not stop your research with adidas. Use focused screens to spot fresh opportunities quickly, compare quality, and avoid missing ideas that fit your style.
- Target potential mispricing and hunt for quality at a discount with the 179 high quality undervalued stocks.
- Build a steadier income stream by zeroing in on companies screened as 155 dividend fortresses.
- Prioritise resilience and sleep-better-at-night holdings using the 227 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com