
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Deposit Growth At StoneCo Stock Has Changed Its Investment Story
- StoneCo recently reported 4% growth in Total Payment Volume and a 22% rise in retail deposits, while rolling out a renewed brand as "the bank for entrepreneurs" that leans on disciplined credit expansion and government-backed programs in a high interest rate setting.
- The combination of rising deposits, a focused push into banking and credit, and maintained full year guidance indicates that StoneCo is leaning further into higher margin financial services to deepen client engagement and support its operating model.
- We will now look at how this banking-focused push, particularly the jump in retail deposits, could reshape StoneCo's investment narrative.
Scan for other payment and fintech stocks that are focusing on banking and deposit growth with disciplined credit by running the curated 16 high quality undiscovered gems alongside your view on StoneCo.
StoneCo Investment Narrative Recap
To own StoneCo, you need to be comfortable with a payments and fintech player that is reallocating toward higher margin banking and credit, while dealing with slower Total Payment Volume growth and a tougher rate backdrop. The latest update, with 4% TPV growth and 22% higher retail deposits, reinforces that the near term story hinges on execution in financial services rather than pure volume gains.
The key short term catalyst is whether StoneCo can keep scaling deposits and credit without a jump in loss provisions or funding costs, especially with interest payments already not well covered by earnings. The biggest risk is that slower TPV and rising competition compress pricing before the banking push delivers enough recurring income. The recent figures do not materially change that risk reward balance, but they sharpen the focus on credit quality.
The most relevant piece of recent news for this is StoneCo leaning into its refreshed positioning as "the bank for entrepreneurs" and delivering 22% growth in retail deposits. That operational shift matters for catalysts because it directly relates to one of the main levers investors are watching: the mix toward deposit funded banking income and credit yields instead of just transaction volume.
Deposit traction, paired with maintained full year guidance, provides more concrete data to judge whether the firm can support higher margin services while keeping risk controlled in a high rate setting. Execution will be judged on credit performance, funding costs, and how efficiently those deposits are recycled into government backed and other loan programs, especially with consensus still expecting earnings to decline on average over the next few years.
StoneCo's current earnings are R$3.5b, with analysts forecasting earnings of R$2.8b by 2029 and revenue of R$17.4b. This implies annual revenue growth of 8.7% and an earnings decline of R$0.7b from today.
Uncover why StoneCo's fair value indicates a 60% potential upside to its current price, a gap that could narrow quickly.
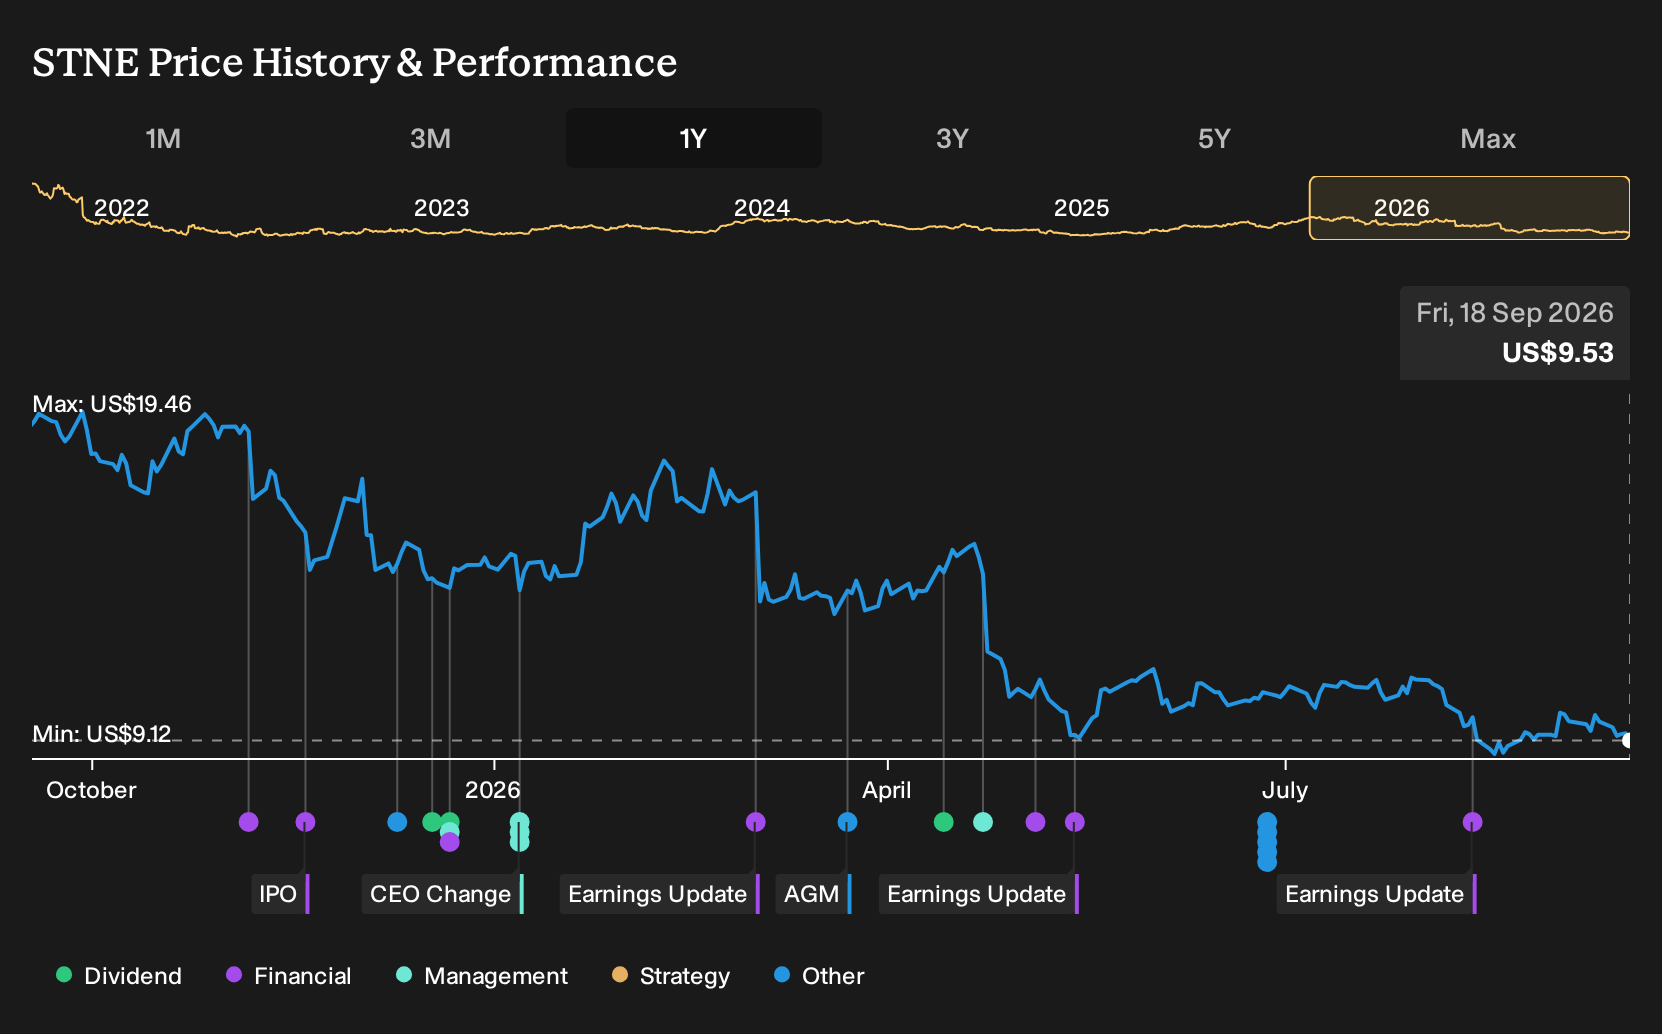
Exploring Other Perspectives
Some of the most optimistic analysts were already treating deposit growth and full banking integration as the real swing factor for StoneCo. Before this latest update, that group was modeling R$19.9b in 2029 revenue and R$3.7b in earnings. You can now ask whether the 22% deposit jump nudges those bullish narratives even further or forces a rethink.
Explore 4 other StoneCo fair value estimates, including one that suggests potential upside of up to 449% from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your StoneCo research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for StoneCo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate StoneCo's overall financial health at a glance.
Looking for more StoneCo investment ideas?
If the latest StoneCo update has sharpened your thinking, it can help to put it alongside other businesses with different risk and return profiles.
- For investors who want quality and value in the same place, scan a curated set of companies trading below what their fundamentals might justify using the 33 high quality undervalued stocks.
- If capital preservation comes first for you, filter for businesses with stronger financial resilience and steadier risk profiles through the 30 resilient stocks with low risk scores.
- To cast the net wider and look beyond well known tickers, broaden your research with a targeted 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com