
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Mirum Stock In Focus Ahead Of Rare Disease Drug Decision
- Mirum Pharmaceuticals recently appointed hepatologist Rob Myers, M.D., as Chief Medical Officer, succeeding Joanne Quan, M.D., following his prior leadership roles at OrsoBio and Gilead Sciences.
- The upcoming FDA decision on zilurgisertib for fibrodysplasia ossificans progressiva highlights that Mirum's rare disease focus now extends beyond liver disorders.
- This article examines how Mirum Pharmaceuticals' investment narrative could be influenced by the incoming CMO and the pending zilurgisertib ruling.
Mirum Pharmaceuticals Investment Narrative Recap
To own Mirum Pharmaceuticals, you need to believe in a rare disease platform that can broaden beyond Livmarli and liver disorders into a wider set of ultra-orphan conditions. The key near term swing factor is the FDA ruling on zilurgisertib for fibrodysplasia ossificans progressiva, which could add a new dimension to the portfolio if approved or leave the story more concentrated if it is not.
At the same time, Livmarli remains central to Mirum Pharmaceuticals, with exposure to competition, pricing pressure and complex reimbursement, especially outside the US. Heavy R&D and commercial spend, combined with current losses and negative shareholders' equity, keep execution risk high if new indications or products are delayed or smaller than hoped.
The most relevant operational update is the appointment of Rob Myers as Chief Medical Officer, stepping in after his prior roles at OrsoBio and Gilead Sciences. His background in hepatology, cholestatic liver disease and endocrine related disorders aligns closely with Mirum Pharmaceuticals' existing focus on Livmarli and cholestatic programs, as well as its push into adjacent rare conditions.
For you as an investor, the question is whether this leadership change improves the odds of delivering on upcoming clinical and regulatory catalysts, including the pending zilurgisertib decision. The hire does not remove core risks such as revenue concentration, high R&D intensity, potential dilution and pressure on orphan drug pricing, but it may help execution across multiple late stage trials and new indication launches.
What The Current Mirum Pharmaceuticals Forecast Really Implies
Mirum Pharmaceuticals' narrative projects US$1.2b revenue and US$285.7 million earnings by 2029. This assumes 24.9% yearly revenue growth and an earnings swing of about US$1.1b from a loss of US$860.2 million today to the forecast profit.
Uncover why Mirum Pharmaceuticals' fair value indicates a 51% potential upside to its current price, which could narrow quickly if sentiment turns.
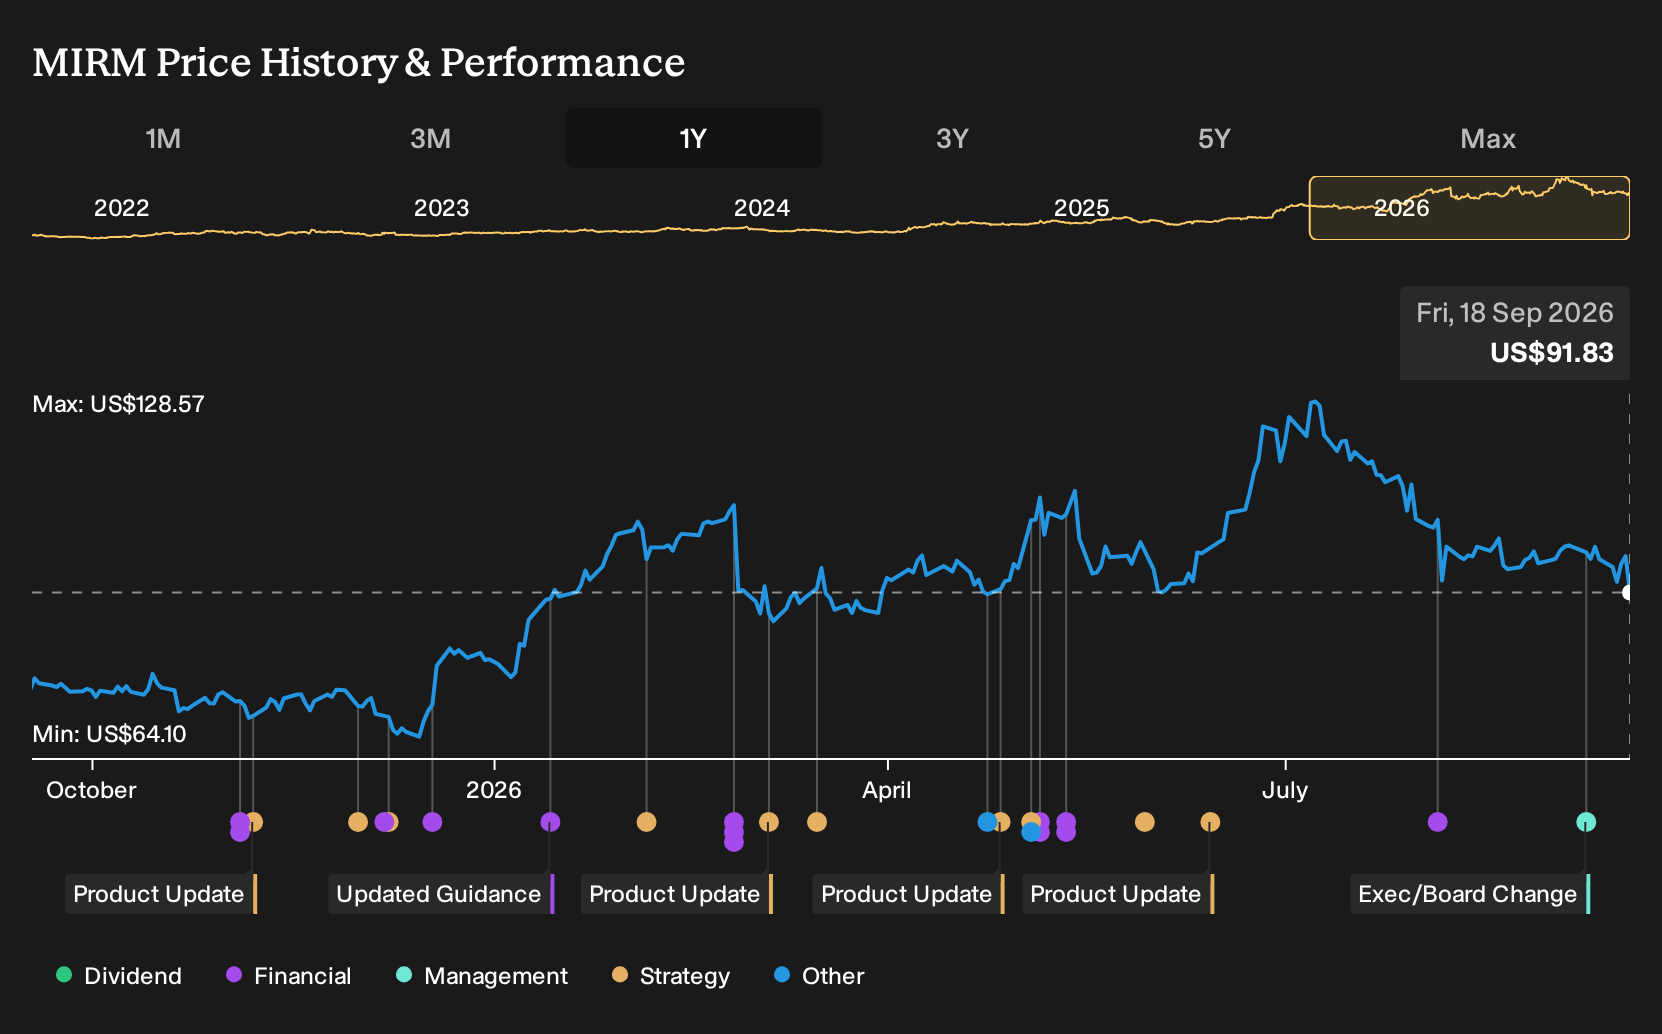
Exploring Other Perspectives
One alternative story around Mirum Pharmaceuticals puts drug pricing pressure at the center. The most cautious analysts, using data from before Rob Myers joined and before the zilurgisertib decision, were only looking for about US$1.0b of revenue and US$81.7 million of earnings by 2029. That is a much more restrained outlook than consensus. It shows how far opinions can stretch. Use those gaps as a prompt to explore several different scenarios for the business rather than anchoring on a single forecast.
Explore 2 other Mirum Pharmaceuticals fair value estimates, including one that suggests it could be worth just $118.11!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Mirum Pharmaceuticals research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Mirum Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mirum Pharmaceuticals' overall financial health at a glance.
Looking For More Ideas Beyond Mirum Pharmaceuticals?
Once you have a view on Mirum Pharmaceuticals, it can help to compare that thesis with other opportunities that fit different risk and return profiles. The Simply Wall St Screener lets you filter the market quickly so you can spend more time weighing the trade offs and less time trawling through tickers.
- If you want potential upside with tightly defined criteria, start with a focused group of 30 resilient stocks with low risk scores that score well on resilience and risk controls.
- For investors who care most about balance sheet strength, scan a list of solid balance sheet and fundamentals (23 results) that pairs financial stability with solid underlying fundamentals.
- When you are hunting for future Mirum style stories early, look through a 16 high quality undiscovered gems that the wider market may not be paying much attention to yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com