
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Positive BEAM 302 Data At Beam Therapeutics (BEAM) Has Changed Its Investment Story
- Beam Therapeutics reported updated Phase 1/2 data for BEAM-302 in alpha-1 antitrypsin deficiency, with a single 60 mg dose showing acceptable tolerability, sustained functional AAT levels above the 11 µM protective threshold, and marked reductions in toxic Z-AAT and Z-polymers across lung and liver disease cohorts.
- The plan to seek an accelerated FDA approval pathway for BEAM-302, using AAT biomarker changes over 12 months and expanding the ongoing open-label trial with about 50 additional patients, directly links Beam Therapeutics' base editing platform to a potentially registrational program in liver-targeted genetic disease.
- This development may influence how investors view Beam Therapeutics' broader genetic medicine pipeline, with a particular focus on the implications of the push for accelerated BEAM-302 approval.
Beam Therapeutics Investment Narrative Recap
For an investor to own Beam Therapeutics, belief needs to center on base editing translating into approved therapies in hematology and liver disease. The BEAM-302 update matters because it moves the lead liver program closer to a potential BLA path and gives the in vivo editing story more real-world data, not just preclinical promise.
In the near term, the key swing factor is whether BEAM-302 can progress smoothly through the expanded pivotal cohort and into an accelerated approval filing. The biggest risk still sits with clinical setbacks or safety concerns across the portfolio, combined with an unprofitable profile that keeps funding needs and dilution very much on the table.
The BEAM-302 Phase 1/2 data and FDA feedback now sit alongside a broader industry backdrop where in vivo gene editing is expected to expand. That context matters because Beam Therapeutics operates in a field where multiple players are pushing programs into the clinic, and where clinical execution tends to move sentiment quickly when data emerge.
For catalysts, the BEAM-302 accelerated approval effort sits next to progress in BEAM-101 and the ESCAPE conditioning work. Together they concentrate operational focus on two franchises. That concentration cuts both ways. Success in these areas could reshape the business, while delays, additional safety flags, or slower recruitment would likely keep earnings under pressure and financing needs elevated.
Beam Therapeutics' current analyst narrative points to forecast revenue of US$207.3 million and projected earnings of US$39.3 million by 2029. That view assumes revenue growth of 8.1% per year and an earnings swing of about US$105.3 million from an earnings loss of US$66.0 million today.
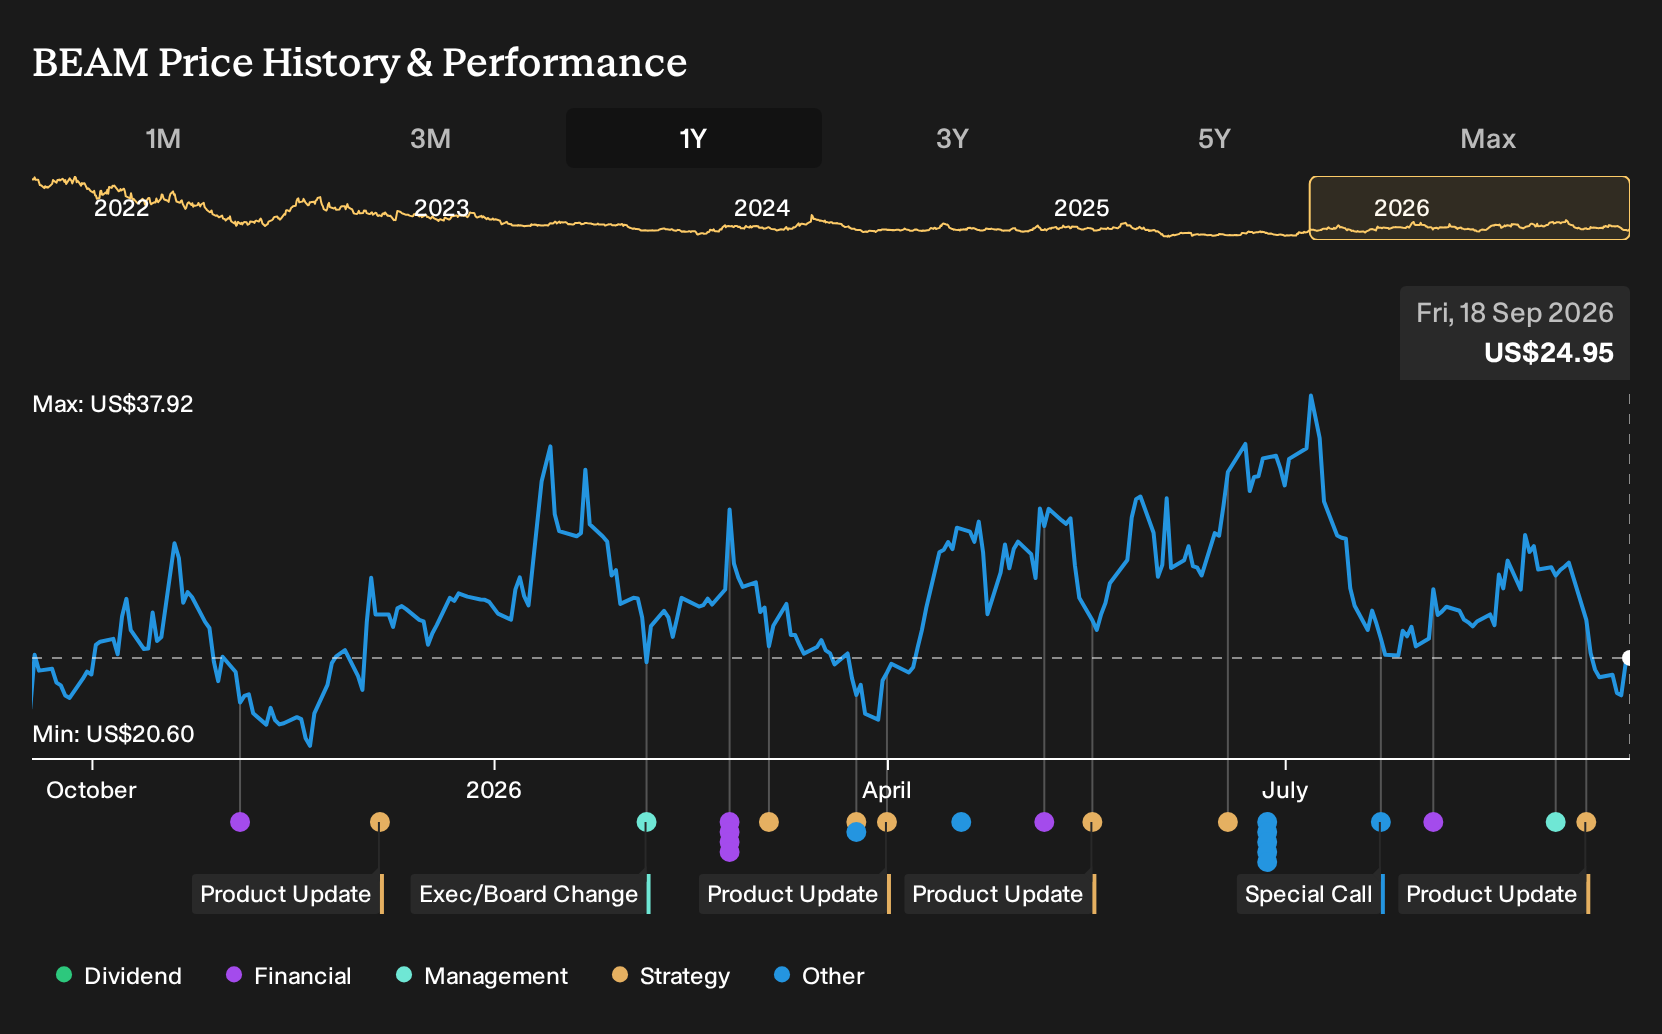
Discover how Beam Therapeutics' fair value indicates a 105% potential upside to its current price, which may not last much longer.
Exploring Other Perspectives
One alternate angle for Beam Therapeutics leans hard into platform risk. The most bearish analysts were working off revenue of about US$34.5 million and earnings of roughly US$6.5 million by 2029, far below consensus. That view treats complex programs like BEAM-302 as slower to translate; yet this new data could push opinions to evolve.
Explore 5 other Beam Therapeutics fair value estimates, including one that suggests as much as 50% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Beam Therapeutics research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Beam Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Beam Therapeutics' overall financial health at a glance.
Looking for more Beam Therapeutics-style investment ideas?
If the Beam Therapeutics story has you thinking about what else might be hiding in plain sight, the Simply Wall St Screener can help you widen the search without losing focus on quality and risk.
- For investors who want stability first and volatility second, consider a 30 resilient stocks with low risk scores that still offer meaningful exposure to equity upside.
- If balance sheet strength is non negotiable for you, filter for companies with robust finances using our list of solid balance sheet and fundamentals (23 results).
- When you want to get ahead of the crowd, scan for underfollowed opportunities with strong fundamentals through our 16 high quality undiscovered gems
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com