
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Dual Gene Silencing Data Will Impact Arrowhead Pharmaceuticals Stock Investors
- Arrowhead Pharmaceuticals reported interim Phase 1/2a data for ARO-DIMER-PA, showing single-dose dual gene silencing of PCSK9 by 72% and APOC3 by 88%, with no drug related serious adverse events in adults with mixed hyperlipidemia.
- The result that one RNAi molecule achieved deep and durable silencing of two cardiometabolic genes positions ARO-DIMER-PA as a differentiated asset in Arrowhead Pharmaceuticals' broader RNA interference pipeline.
- This development may influence how investors view Arrowhead Pharmaceuticals' narrative in cardiometabolic disease, given the dual PCSK9 and APOC3 silencing milestone.
Arrowhead Pharmaceuticals Investment Narrative Recap
To own Arrowhead Pharmaceuticals, you need to believe in RNA interference as a repeatable drug creation engine, not just a one product story. The big near term focus sits on advancing late stage cardiometabolic programs like plozasiran and zodasiran while keeping R&D and SG&A spend aligned with a still loss making income statement. Interim ARO DIMER PA data adds depth to the cardiometabolic pitch but does not change that central equation yet.
The most important near term swing factor remains regulatory progress and potential approvals for late stage assets, paired with execution on the first commercial rollout. The largest risk is that rising trial and commercial costs, together with reliance on partner milestones, strain the cash runway if key programs hit delays or partners slow commitments.
In that context, Arrowhead Pharmaceuticals highlighting plans to file for severe hypertriglyceridemia approval for REDEMPLO by year end ties directly into the catalyst stack investors are watching. Progress toward a potential second quarter 2027 SHTG launch, alongside the existing rollout, helps frame whether the current spend on sales infrastructure and late stage trials can transition into recurring product revenue over time.
For anyone following the ARO DIMER PA update, that REDEMPLO and plozasiran path is where operational execution will likely feel most visible. Regulatory timing, payer traction, and uptake in severe hypertriglyceridemia could influence how much flexibility Arrowhead Pharmaceuticals has to keep funding earlier programs like ARO DIMER PA without leaning further on collaboration payments or higher cost capital.
Arrowhead Pharmaceuticals' scenario work points to US$1.0b in revenue and US$176.0 million in earnings by 2029, based on analyst forecasts. That profile assumes 15.7% yearly revenue growth and an earnings move of roughly US$496.0 million from a loss of US$320.0 million today to the projected 2029 level.
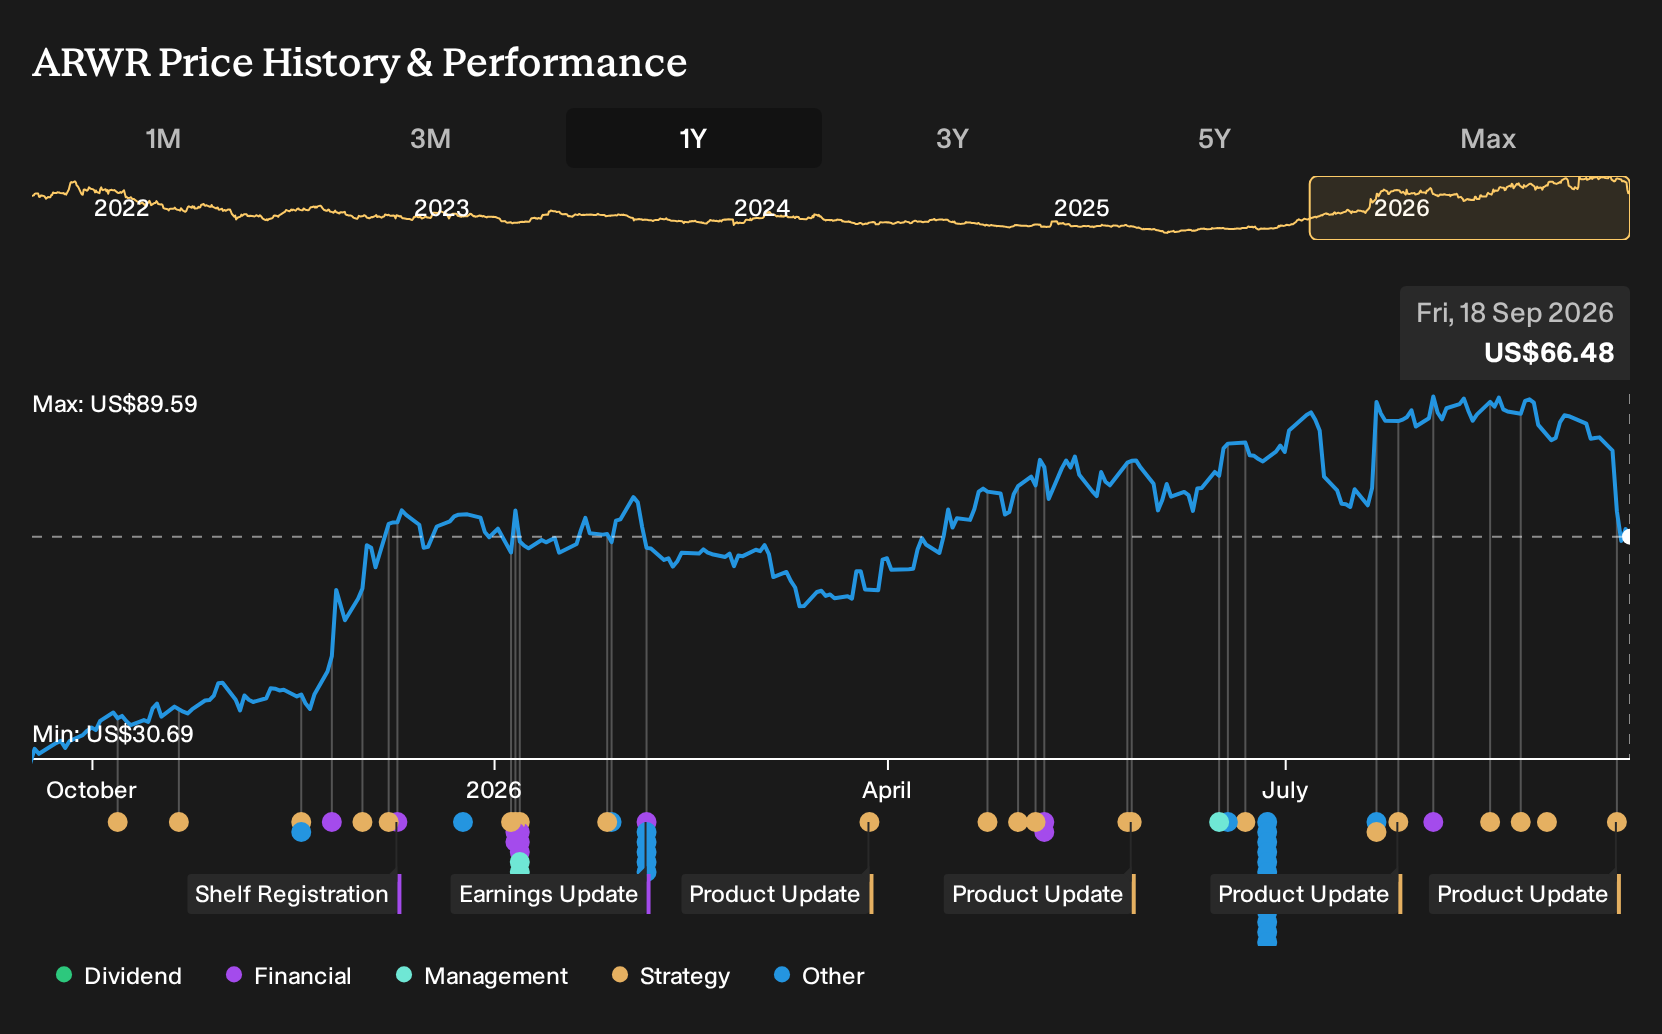
Uncover why Arrowhead Pharmaceuticals' fair value indicates a 66% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses less on Arrowhead Pharmaceuticals’ science and more on future pricing pressure. The most cautious analysts expected revenue of about US$403.8 million and earnings of roughly US$71.8 million by 2029, with a very high implied P/E. They were already wary before this ARO-DIMER-PA data, which could eventually reshape those expectations.
Explore 2 other Arrowhead Pharmaceuticals fair value estimates, including one that suggests it could be worth just $110.18!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Arrowhead Pharmaceuticals research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Arrowhead Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Arrowhead Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Arrowhead Pharmaceuticals?
If Arrowhead Pharmaceuticals has sharpened your interest in cardiometabolic science and data driven healthcare, it can help to broaden your watchlist with other clear, fundamentals based ideas sourced through the Simply Wall St Screener.
- For investors who want potential upside with strict financial discipline, scan through 16 high quality undiscovered gems that pair strong balance sheets with under followed stories and solid underlying metrics.
- If capital preservation sits higher on your checklist, focus on stability first and sort the market using the 30 resilient stocks with low risk scores that filters for resilient businesses with lower assessed risk scores.
- Income focused readers who care about cash returns as much as headlines can review the 6 dividend fortresses to see which companies combine 5%+ yields with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com