
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did High Court Appeal Bid Just Shift AGL Energy's (ASX:AGL) Investment Narrative?
- The Australian Energy Regulator has sought special leave to appeal to the High Court after the Full Federal Court backed AGL Energy in a dispute over Centrepay billing practices affecting Centrelink customers.
- This legal step revives regulatory and compliance uncertainty around AGL Energy’s customer billing controls, with potential implications for remediation processes, internal costs and future oversight.
- We will now explore how AGL Energy's investment narrative interacts with renewed regulatory scrutiny over Centrepay billing compliance.
Scan other regulated utilities facing similar oversight pressure and identify which ones still pass strict balance sheet and cash flow checks across our hand picked 7 resilient stocks with low risk scores.
AGL Energy Investment Narrative Recap
To be comfortable as a shareholder in AGL Energy, you need to believe the retail and generation businesses can absorb heavy investment in batteries, firming assets and digital systems without permanently squeezing free cash flow. The key near term swing factor is how effectively AGL Energy converts that spend into steady earnings while managing wholesale price volatility and competitive pressure in electricity and gas.
The High Court leave application on Centrepay goes straight to that belief in execution and controls. If the case results in broader remediation or tighter rules, it may lift compliance costs and add noise around customer operations. At this stage, the main energy transition and capex story is still the core driver. Unless the legal outcome materially changes cash outflows, the long term thesis is mostly intact.
Recent commentary around earnings forecasts and valuation is closely tied to this. Analysts expect revenue to edge up only modestly and for earnings to decline on average over the next few years. That slow profile sits against AGL Energy’s heavy capital program and existing debt load, which already raises questions about dividend coverage and balance sheet flexibility.
Those same forecasts underpin an estimate that the shares trade below some models of future cash flow value and on a relatively low P/E versus peers. For you, the Centrepay case adds another layer to weigh. Execution on decarbonisation, batteries and digital transformation remains the big operational catalyst. The regulatory process around customer billing is now an extra risk checkpoint when thinking about earnings quality and future cash generation.
AGL Energy Forecasts and Valuation Checkpoints
AGL Energy's consensus narrative points to revenue of A$13.5b and earnings of A$442.8m by 2029. That path assumes a 1.1% yearly decline in revenue and an earnings decrease of about A$313.2m from A$756.0m today.
Discover how AGL Energy's fair value indicates a 17% potential upside to its current price that could close sooner than many investors expect.
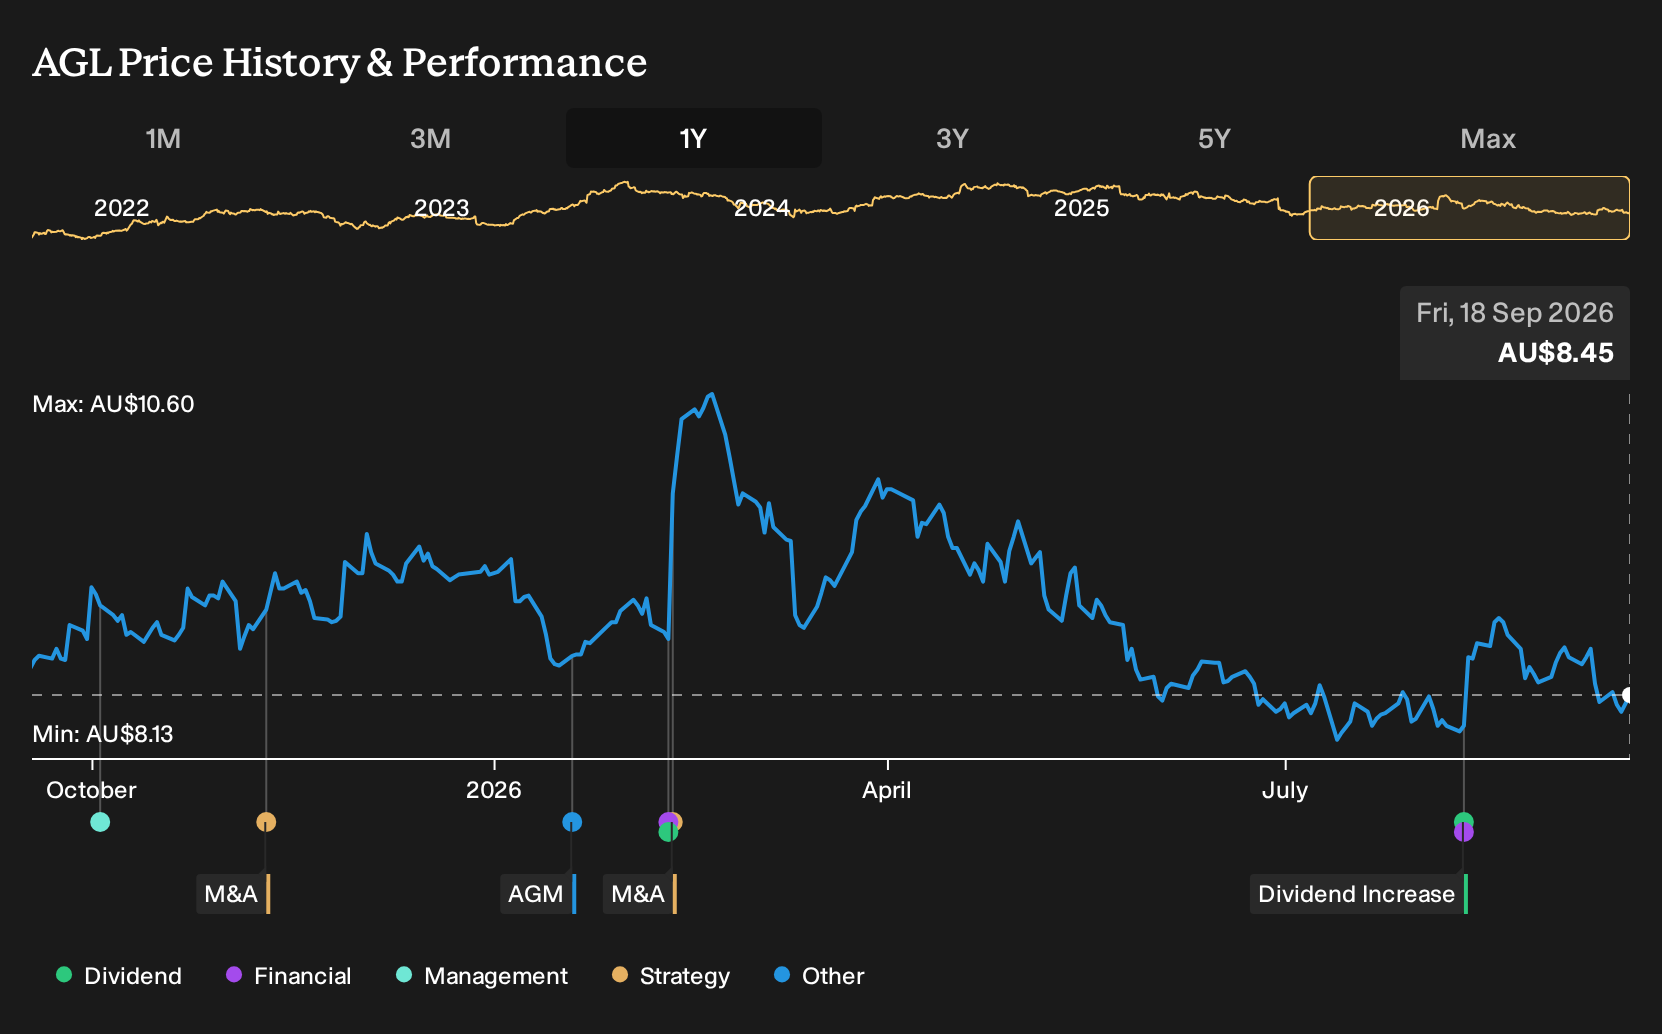
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between A$9.91 and A$16.34, which leaves plenty of room for disagreement on where AGL Energy should trade. Those opinions pre date the High Court leave application and heavy capex and margin pressure, so treat them as starting points and compare multiple perspectives before committing capital.
Explore 2 other AGL Energy fair value estimates, including one that suggests it could be worth just A$9.91.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AGL Energy research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for AGL Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AGL Energy's overall financial health at a glance.
Looking for more AGL Energy sized investment ideas?
If the AGL Energy story has you thinking about position sizing, risk and balance sheet strength, it can help to widen the lens and compare it with other listed businesses that share similar financial traits.
- For investors who care most about capital preservation and smoother rides through market swings, focus on companies with resilient finances and low risk profiles through our 7 resilient stocks with low risk scores.
- If income is a priority and you want potential yield alongside balance sheet discipline, check out businesses that qualify as 3 dividend fortresses.
- When you are hunting for opportunities that have not yet drawn broad attention but still show solid fundamentals, start with our 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com