
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
NetScout Systems (NTCT) Tests Its Valuation Case On ESOP Shelf Filing
NetScout Systems (NTCT) has filed a US$280.8m shelf registration covering 7,500,000 common shares for an employee stock ownership plan related offering, a move that could influence the future supply of the stock.
The shelf registration lands after a strong run for NetScout Systems, with the share price up 42.31% year to date and a 1 year total shareholder return of 47.93%. However, the 90 day share price return declined 3.68%, which suggests momentum has cooled recently as investors reassess risk and future potential around corporate actions such as this ESOP related offering.
Scan how NetScout Systems compares to other potential breakout opportunities across 33 high quality undervalued stocks with resilient balance sheets and healthier cash generation profiles.
NetScout Systems has rallied hard this year, then cooled just as the ESOP shelf appeared. Should investors act now or wait for a cleaner entry based on what the valuation indicates?
Most Popular Narrative: 8% Undervalued
On the latest estimates, the most followed narrative pegs NetScout Systems at a fair value of $41.71 compared with the recent close of $38.21, which frames the ESOP shelf against a stock that screens as modestly discounted on fundamentals.
Market optimism appears to be driven by strong recent growth in NetScout's cybersecurity segment, underpinned by customers prioritizing spending to counter increasingly complex and expanding cyber threats, which could lead investors to expect above-trend long-term revenue and earnings growth.
There is a narrative that NetScout's integration of AI-driven capabilities (like Omnis AI Insights and AI-backed enhancements in DDoS defense) positions the company as a differentiated leader in an expanding observability and cybersecurity market, potentially prompting unrealistic expectations for sustained margin expansion and premium revenue multiples.
See why 3 investors see NetScout Systems as 8% undervalued.
Result: Fair Value of $41.71 (UNDERVALUED)
Still, the NetScout Systems story could be knocked off course if cloud migration weakens legacy offerings or if customers consolidate tools faster than expected.
Find out about the key risks to this NetScout Systems narrative.
Another View on NetScout Systems Valuation
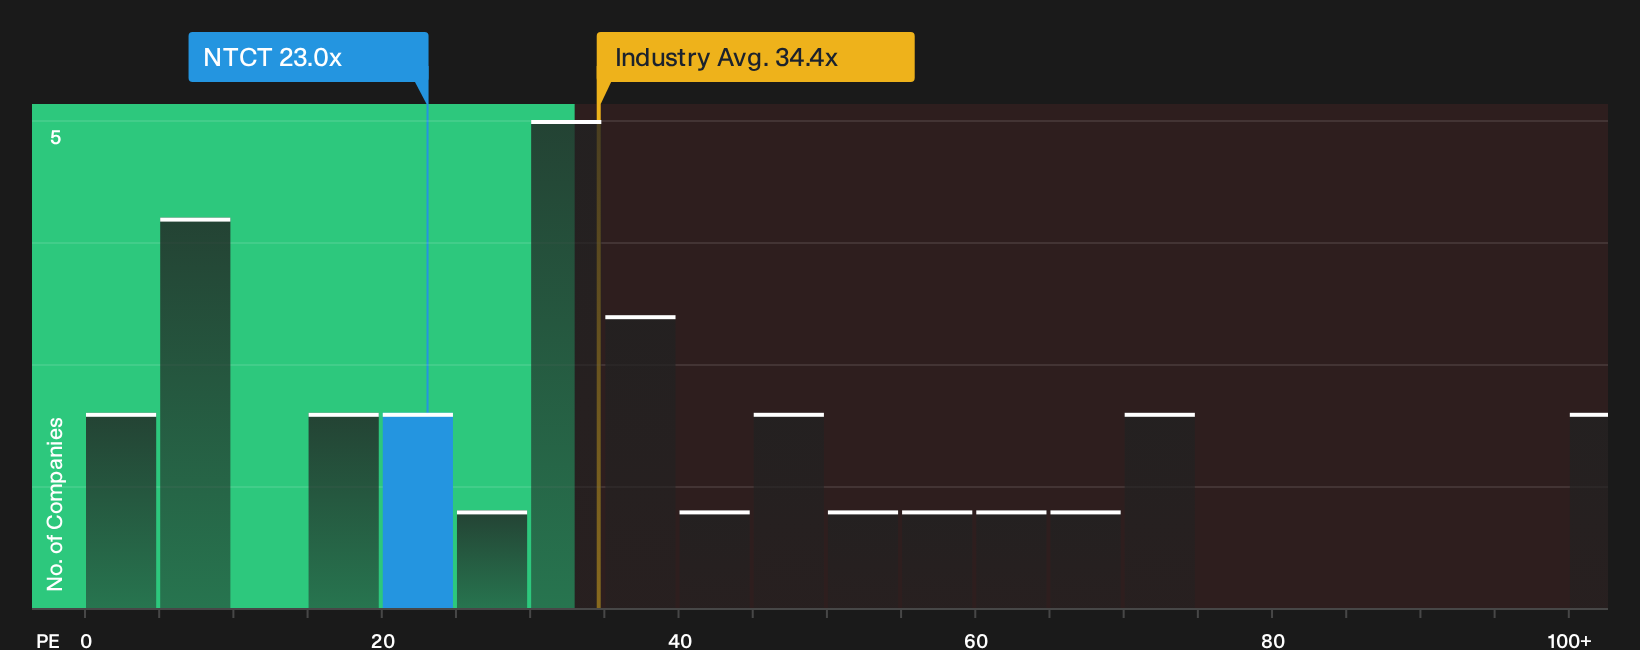
The first narrative leans on growth expectations and analyst targets. A different lens comes from earnings multiples. NetScout Systems trades on a P/E of 23x, while the fair ratio is 17.9x and the US Communications industry sits at 34.4x with peers at 53.6x. That mix signals both relative value and fair ratio risk. Which way do you think the multiple drifts next?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on NetScout Systems is mixed, with both risk flags and upside drivers in play. Move quickly, review the underlying data, and weigh the 2 key rewards and 1 important warning sign.
Looking for more NetScout Systems style investment ideas?
Do not stop with NetScout Systems. Fresh opportunities keep emerging, and casting a wider net now can help you spot candidates that better fit your risk and return goals.
- Target resilient performers by scanning our 30 resilient stocks with low risk scores that aim to balance downside protection with steadier return potential.
- Hunt for quality at a discount using the 16 high quality undiscovered gems that may not yet be widely followed by the broader market.
- Strengthen your core holdings by reviewing the list of solid balance sheet and fundamentals (23 results) so you stay focused on companies with healthier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com